



US open: Futures tumble on hotter than expected inflation
US CPI and core cpi both came in ahead of forecasts, pouring cold water on any hopes of a less hawkish stance coming from the Fed.
Share this:

US futures
Dow futures -1.7% at 31820
S&P futures -2.2% at 4085
Nasdaq futures -2.4% at 12380
In Europe
FTSE -1% at 7450
Dax -1.12% at 13325
Euro Stoxx -1.3% at 3870
Rally built on false hopes reverses
US stocks are set to open sharply lower after US inflation was hotter than expected. CPI rose 8.3% YoY, down from 8.5% in July but short of the 8.1% forecast.
Core CPI, which strips out more volatile items such as food and fuel rose to 6.3%, up from 5.9% in July.
The market, which had been rallying over recent sessions on hopes of inflation cooling significantly, has had a reality check. With core inflation rising strongly, there seems little chance of the Fed taking its foot off the gas anytime soon.
The data will be a concern for the Fed, which is due to announce its interest rate decision next week. While the market was getting carried away that there was a possibility of a 50 basis point hike, the data is suggesting that a 100 basis point hike is more likely than 50!
The data is showing that the cooling in inflation is going to be a long slow process. This is the second time that the market has gotten ahead of itself in hope that the Fed could be arriving at a crossroads where a less hawkish approach was called for. This probably won’t be the last time, either.
Reflecting the hotter-than-expected inflation print and higher for longer rate expectations, US stocks are falling, Gold has tumbled, and the USD has reversed the 5-day selloff, charging back towards 109.00. We could expect the US stocks to reverse the last 4-day rally, which it appears was constructed on false pretences.
Corporate news:
Oracle rises after reporting solid Q1 revenues thanks to robust demand for its cloud services and as it starts to reap the benefits of buying IT firm Cerner.
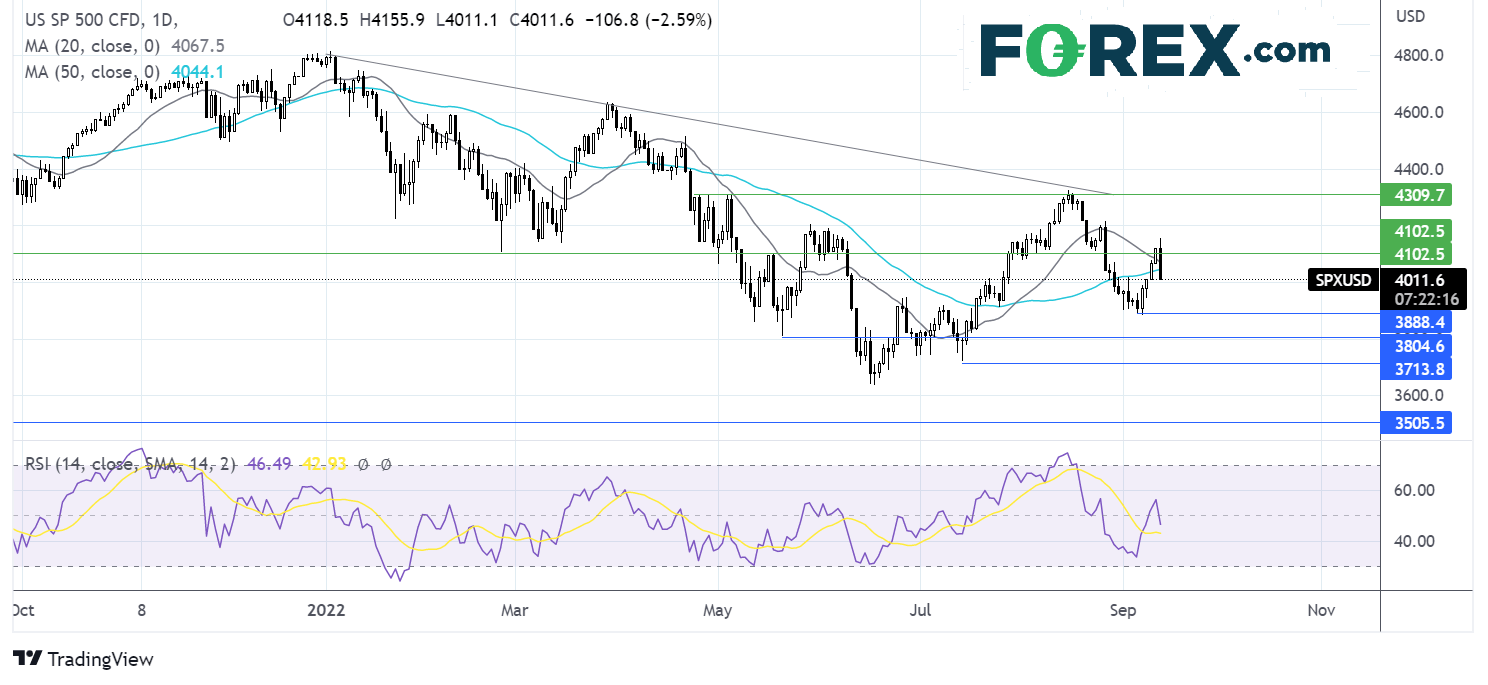
Where next for the S&P500?
FX markets – USD rallies, EUR rises
The USD is rising after the hotter than forecast inflation. Expectations of more rate hikes are lifting the greenback.
EUR/USD is falling on US strength and after dire German economic sentiment data. The ZEW German economic sentiment fell to -61.9 in September, showing that investors are more pessimistic regarding the outlook of the German economy. This was down from -55.3 in August.
GBP/USD is falling after a mixed bag from the labour report. The UK unemployment rate fell to 3.6%, its lowest level since 1974, as more people left the workforce. However, signs of weakness are also emerging, with vacancies falling by the most since the summer 2020 and employment rising by just 40,000, below the 120,00. Wages also rose to 5.2%
Oil edges higher
Oil prices are rising for a fourth straight day as the market struggles to shake off tight supply fears which are overshadowing concerns over the demand outlook. China continues with its strict zero-COVID rules and as central banks across the globe continue hiking interest rates.
In the US SPR emergency reserves fell by 8.4 million to 434.1 million barrels, marking the lowest level since October 1984. The Biden administration pledged to release 1 million barrels a day from the SPR reserves over 6 months in order to bring fuel prices lower.
Elsewhere, the prospect of the revival of the Iran nuclear deal dimed, offering support to oil prices. Germany said it was disappointed by Tehran’s response to the European proposal for the 2015 agreement.
WTI crude trades +0.6% at $87.00
Brent trades +0.7% at $93.20
Looking ahead
21:30 API oil stockpiles
US futures
Dow futures -1.7% at 31820
S&P futures -2.2% at 4085
Nasdaq futures -2.4% at 12380
In Europe
FTSE -1% at 7450
Dax -1.12% at 13325
Euro Stoxx -1.3% at 3870
Rally built on false hopes reverses
US stocks are set to open sharply lower after US inflation was hotter than expected. CPI rose 8.3% YoY, down from 8.5% in July but short of the 8.1% forecast.
Core CPI, which strips out more volatile items such as food and fuel rose to 6.3%, up from 5.9% in July.
The market, which had been rallying over recent sessions on hopes of inflation cooling significantly, has had a reality check. With core inflation rising strongly, there seems little chance of the Fed taking its foot off the gas anytime soon.
The data will be a concern for the Fed, which is due to announce its interest rate decision next week. While the market was getting carried away that there was a possibility of a 50 basis point hike, the data is suggesting that a 100 basis point hike is more likely than 50!
The data is showing that the cooling in inflation is going to be a long slow process. This is the second time that the market has gotten ahead of itself in hope that the Fed could be arriving at a crossroads where a less hawkish approach was called for. This probably won’t be the last time, either.
Reflecting the hotter-than-expected inflation print and higher for longer rate expectations, US stocks are falling, Gold has tumbled, and the USD has reversed the 5-day selloff, charging back towards 109.00. We could expect the US stocks to reverse the last 4-day rally, which it appears was constructed on false pretences.
Corporate news:
Oracle rises after reporting solid Q1 revenues thanks to robust demand for its cloud services and as it starts to reap the benefits of buying IT firm Cerner.
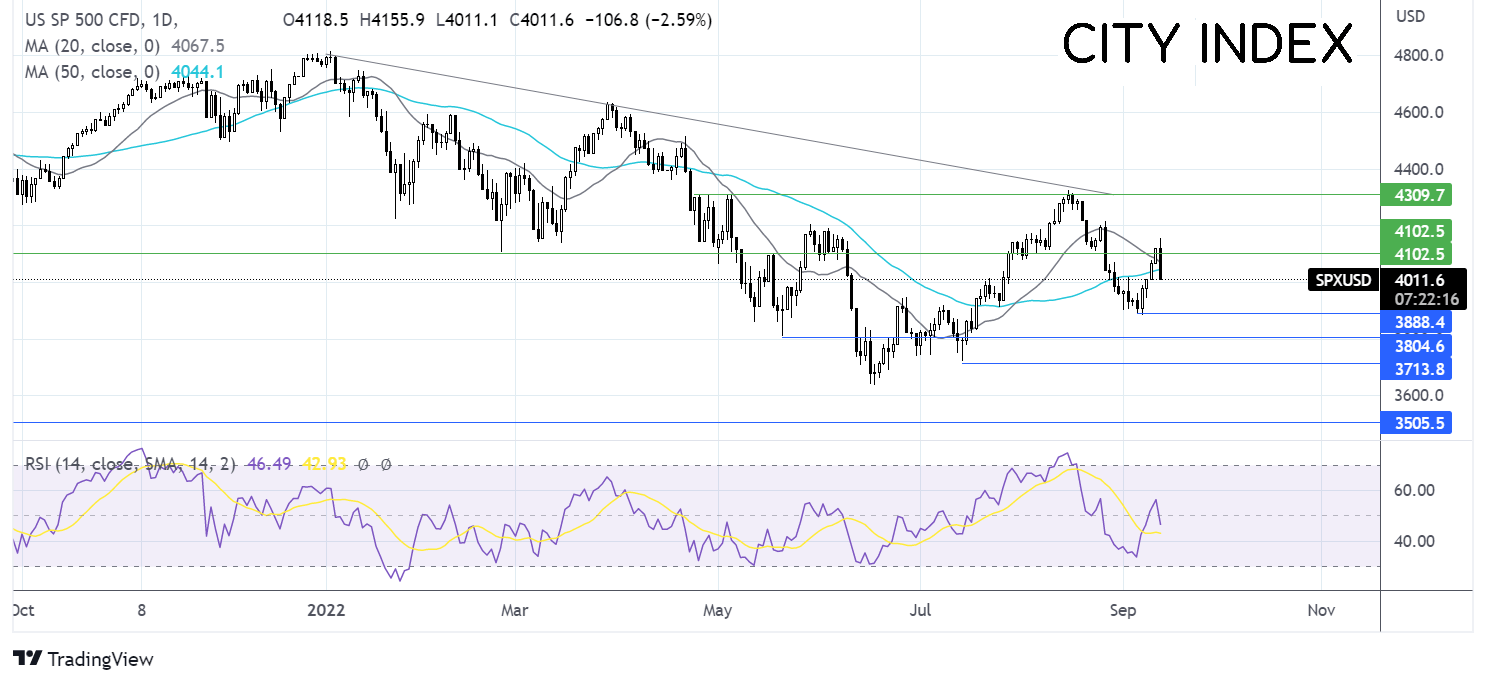
Where next for the S&P500?
FX markets – USD rallies, EUR falls
The USD is rising after the hotter than forecast inflation. Expectations of more rate hikes are lifting the greenback.
EUR/USD is falling on US strength and after dire German economic sentiment data. The ZEW German economic sentiment fell to -61.9 in September, showing that investors are more pessimistic regarding the outlook of the German economy. This was down from -55.3 in August.
GBP/USD is falling after a mixed bag from the labour report. The UK unemployment rate fell to 3.6%, its lowest level since 1974, as more people left the workforce. However, signs of weakness are also emerging, with vacancies falling by the most since the summer 2020 and employment rising by just 40,000, below the 120,00. Wages also rose to 5.2%
Oil edges higher
Oil prices are rising for a fourth straight day as the market struggles to shake off tight supply fears which are overshadowing concerns over the demand outlook. China continues with its strict zero-COVID rules and as central banks across the globe continue hiking interest rates.
In the US SPR emergency reserves fell by 8.4 million to 434.1 million barrels, marking the lowest level since October 1984. The Biden administration pledged to release 1 million barrels a day from the SPR reserves over 6 months in order to bring fuel prices lower.
Elsewhere, the prospect of the revival of the Iran nuclear deal dimed, offering support to oil prices. Germany said it was disappointed by Tehran’s response to the European proposal for the 2015 agreement.
WTI crude trades +0.6% at $87.00
Brent trades +0.7% at $93.20
Learn more about trading oil here.
Looking ahead
21:30 API oil stockpiles
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.