



US open: Stocks steady as corporate earnings move to centre stage
Stocks are set to open muted as corporate earnings step up a gear.
Share this:

US futures
Dow futures -0.01 % at 34580
S&P futures -0.02% at 4437
Nasdaq futures -0.08% at 13906
In Europe
FTSE -0.24% at 7594
Dax +0.11% at 14077
Euro Stoxx -0.25% at 3822
Learn more about trading indices
Corporate earnings and housing data
US stocks are set for a muted start to trade with earnings in focus and a quiet economic calendar after a quiet session on Monday.
US indices have been on the back foot across recent weeks amid rising expectations of a more hawkish Federal Reserve and amid uncertainty surrounding the Ukraine war, which appears to have entered a new phase with Russia attacking hard in the east.
Investors will now focus on corporate earnings to see whether the concerns in the market are being translated into weakness in quarterly results.
On the economic calendar, US housing data suggested that the US housing market remained solid with building permits rising to 1.873 million, ahead of forecasts and housing starts rose 1.793 million, also ahead of expectations.
In corporate news:
Earnings seasons ramp up a gear today with Johnson & Johnson, Hasbro, and the Travelers Companies reporting earnings ahead of the open.
Netflix is due to report after the close and comes after weak subscriber growth forecasts last quarter and as attention shifts to content spending as competition heats up. Data released today in the UK showed that streaming subscription cancellations were rising as the squeeze on disposable income mounts.
Where next for the S&P500?
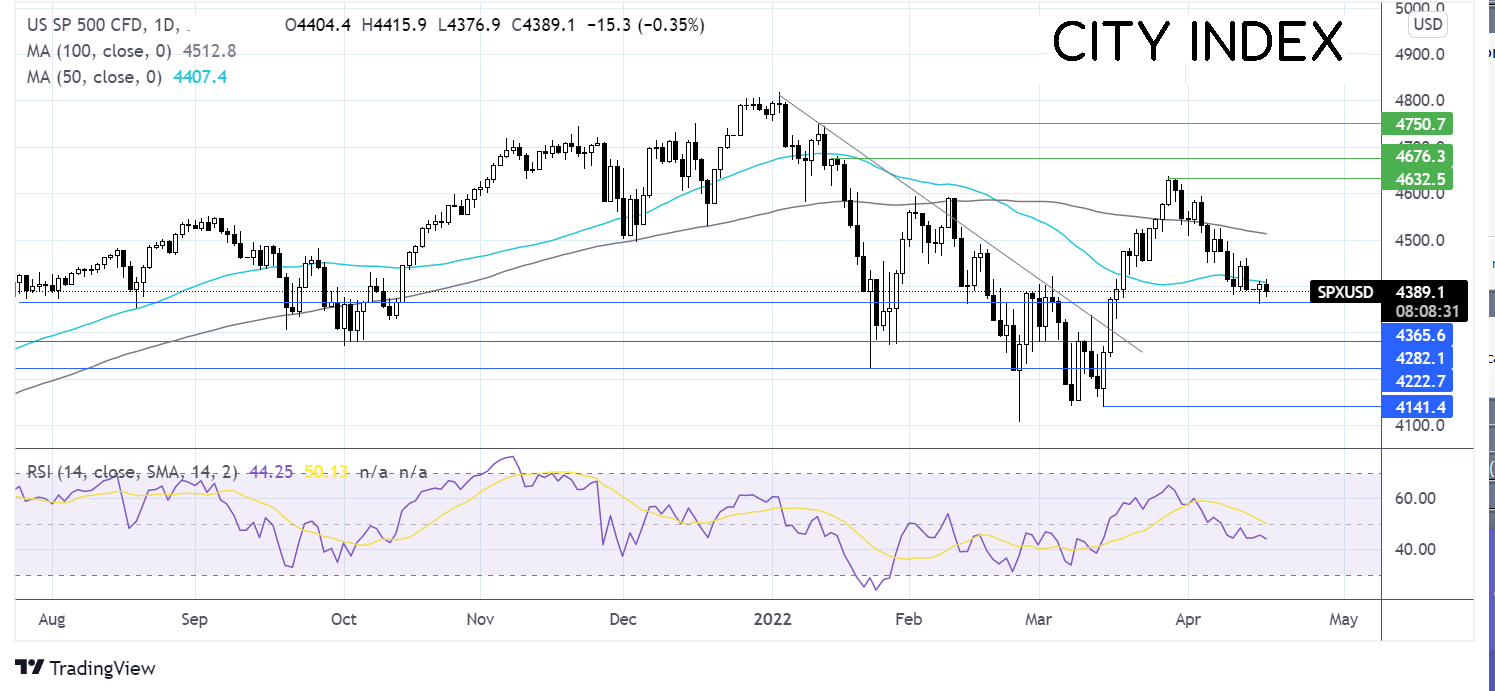
The S&P500 ran into resistance at 4623 and rebounded lower falling below the 50 & 100 sma. The losses appear to have run out of steam and the price is consolidating between 4360 last week’s low and 4410 the 50 sma. The RSI is also just south of 50 suggesting consolidation. Buyers will want to see a move over 4410 to expose the 100 sma and round number at 4500. Sellers will look for a move below 4360 to open the door to 4285.
FX markets USD pares gains, JPY crumbles
USD is holding steady, paring earlier gains. US dollar index had rallied earlier extending gains from yesterday after Fed James Bullard talked of a rate hike of 75 bp as a possibility for May but not a base case scenario.
USD/JPY rose to a 20-year high above 128.00 on central bank divergence as the BoJ remains firmly dovish. Rising energy costs are also hurting the outlook for Japan.
EUR/USD is edging higher back towards 1.08 in quiet trade. The USD is driving the pair in otherwise quiet trade with not high-impacting EZ data.
GBP/USD +0.03% at 1.3011
EUR/USD -0.14% at 1.0874
Oil remains volatile
Oil prices edge lower after gains yesterday as volatility in the oil market shows no signs of easing. Concerns over Russian supply remain, and the outage in Libya are keeping prices supported above $100 per barrel. China remains in lockdown, with some signs of easing in restrictions.
However, the GDP downward revision from the World Bank by almost 1% and expectations that the IMF will follow suit is hurting the demand outlook today, dragging on prices. Weak global growth would mean weaker demand.
WTI crude trades -2.27% at $104.98
Brent trades -2.5% at $109.74
Learn more about trading oil here.
US futures
Dow futures -0.01 % at 34580
S&P futures -0.02% at 4437
Nasdaq futures -0.08% at 13906
In Europe
FTSE -0.24% at 7594
Dax +0.11% at 14077
Euro Stoxx -0.25% at 3822
Corporate earnings and housing data
US stocks are set for a muted start to trade with earnings in focus and a quiet economic calendar after a quiet session on Monday.
US indices have been on the back foot across recent weeks amid rising expectations of a more hawkish Federal Reserve and amid uncertainty surrounding the Ukraine war, which appears to have entered a new phase with Russia attacking hard in the east.
Investors will now focus on corporate earnings to see whether the concerns in the market are being translated into weakness in quarterly results.
On the economic calendar, US housing data suggested that the US housing market remained solid with building permits rising to 1.873 million, ahead of forecasts and housing starts rose 1.793 million, also ahead of expectations.
In corporate news:
Earnings seasons ramp up a gear today with Johnson & Johnson, Hasbro, and the Travelers Companies reporting earnings ahead of the open.
Netflix is due to report after the close and comes after weak subscriber growth forecasts last quarter and as attention shifts to content spending as competition heats up. Data released today in the UK showed that streaming subscription cancellations were rising as the squeeze on disposable income mounts.
Where next for the S&P500?
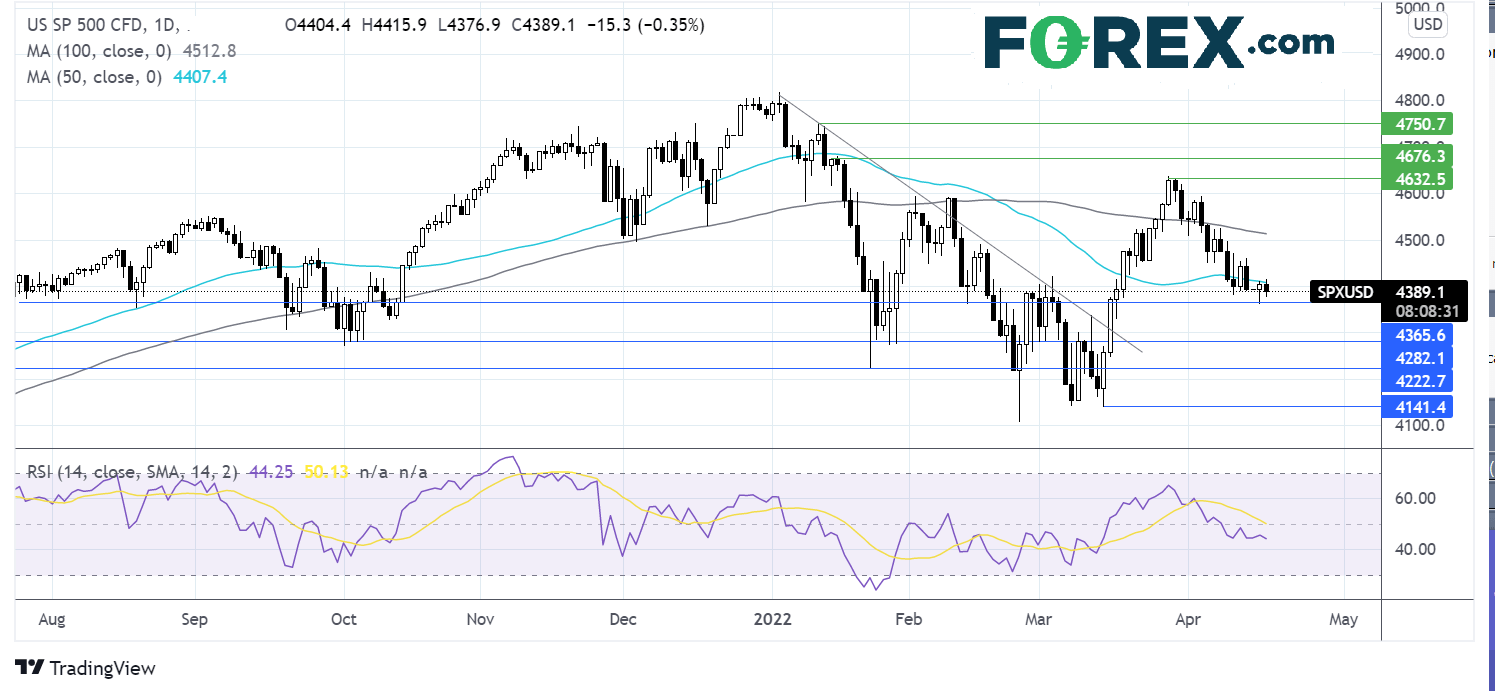
The S&P500 ran into resistance at 4623 and rebounded lower falling below the 50 & 100 sma. The losses appear to have run out of steam and the price is consolidating between 4360 last week’s low and 4410 the 50 sma. The RSI is also just south of 50 suggesting consolidation. Buyers will want to see a move over 4410 to expose the 100 sma and round number at 4500. Sellers will look for a move below 4360 to open the door to 4285.
FX markets USD pares gains, JPY crumbles
USD is holding steady, paring earlier gains. US dollar index had rallied earlier extending gains from yesterday after Fed James Bullard talked of a rate hike of 75 bp as a possibility for May but not a base case scenario.
USD/JPY rose to a 20-year high above 128.00 on central bank divergence as the BoJ remains firmly dovish. Rising energy costs are also hurting the outlook for Japan.
EUR/USD is edging higher back towards 1.08 in quiet trade. The USD is driving the pair in otherwise quiet trade with not high-impacting EZ data.
GBP/USD +0.03% at 1.3011
EUR/USD +0.14% at 1.0790
Oil remains volatile
Oil prices edge lower after gains yesterday as volatility in the oil market shows no signs of easing. Concerns over Russian supply remain, and the outage in Libya are keeping prices supported above $100 per barrel. China remains in lockdown, with some signs of easing in restrictions.
However, the GDP downward revision from the World Bank by almost 1% and expectations that the IMF will follow suit is hurting the demand outlook today, dragging on prices. Weak global growth would mean weaker demand.
WTI crude trades -2.27% at $104.98
Brent trades -2.5% at $109.74
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.