




What the Labour Budget could mean for the market?
On October 30th, Chancellor Rachel Reeves will unveil her first Budget of the new Labour government. Here we look at what this might include and how it could impact the markets, looking at the pound as well as specific sectors in the FTSE.
Share this:

When is the UK budget?
The UK budget will be announced on October 30th around 12:30 GMT.
What we know & what to expect
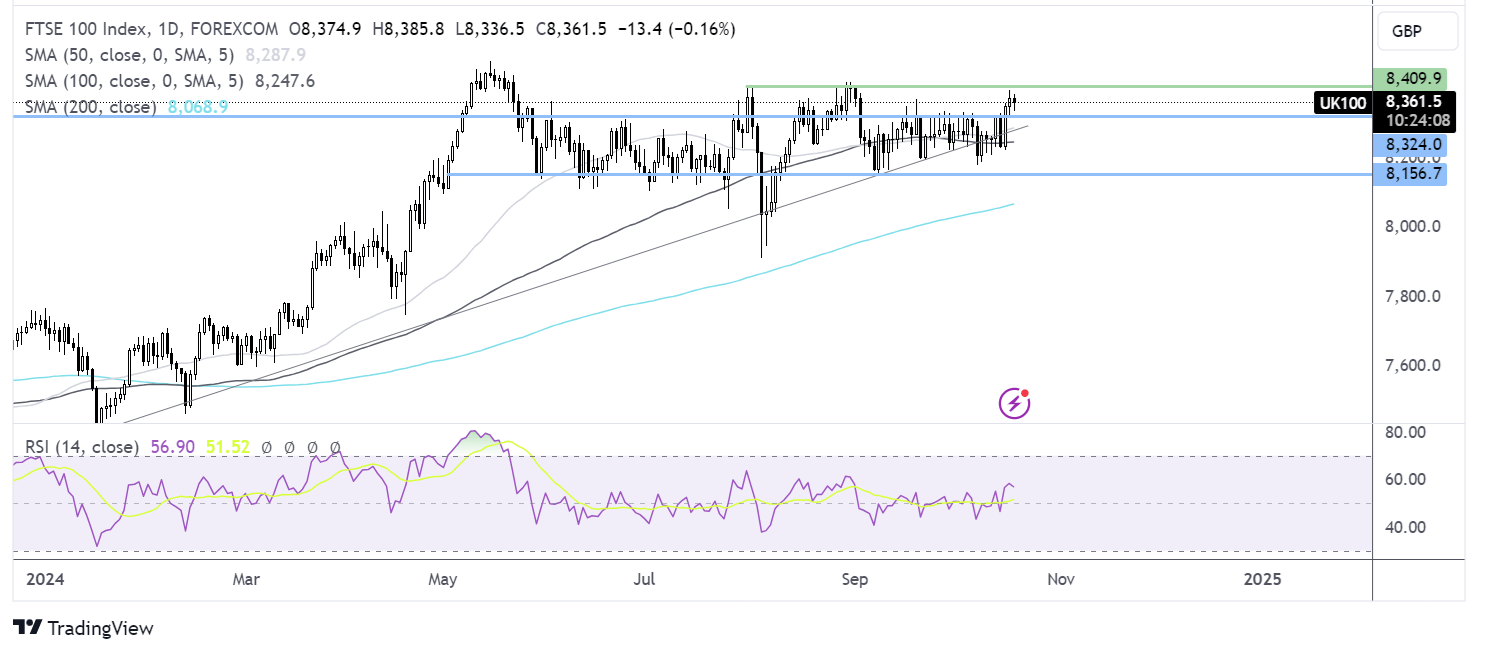
Prime Minister Kier Starmer has been vocal in warning that the Autumn Budget will be painful. With two weeks until the announcement, the UK stock market has been moving sideways in cautious trade. Meanwhile, the pound is hovering around 1.30, a two-month low, as the market raises BoE rate cut expectations.
UK economic data is looking more encouraging heading towards the announcement, which will no doubt please Chancellor Rachel Reeves. Of course, this is the first Budget from a Labour government for over a decade, so Reeves will be keen to set the right tone and avoid the fateful mistakes of Liz Truss two years earlier.
With GDP recovering to 0.2% MoM in August after two months of stagnation, Reeves will hope for stronger growth projections from the Office of Budget Responsibility. This would reduce the need to raise taxes and cut spending to fill the £40 billion pot that Reeves is looking for to not only plug the £22 billion black hole in public finances but also to protect key government departments.
This £40 billion will likely be covered in part by changes to the fiscal rules, cuts to spending in some areas, and, of course, tax increases. These potentially include an employer increase in National Insurance on pension contributions. Capital gains and inheritance tax increases are also possible, although Labour ruled out income tax and VAT increases in their manifesto. Changes to fuel duty, stamp duty, and a levy on e-cigarettes could also be on the cards.
What could this mean for the market?
Gilts & GBP
The latest headlines suggest that Rachel Reeves plans to make significant cuts across some departments, which could contradict the idea of generating growth. Mounting an industrial recovery strategy or any other recovery strategy amid deep department cuts could be very difficult.
The Gilt market will also be watching the government borrowing levels closely. The IMF has warned that the UK is one of a handful of countries where debt to GDP is in danger of rising further. However, we are not expecting the Chancellor to announce anything that would cause the market to question the fiscal credibility that the UK has experienced in recent years since Truss, especially as one of the pledges made by the new government was to deliver economic stability to Brits.
As long as the Chancellor doesn’t lean too far into cuts or borrowing, the pound may remain more focused on the BoE’s easing cycle.
Sectors to watch:
Consumer discretionary
Regarding tax raises, the Chancellor has said that workers won’t see tax increases. This, combined with lower inflation and ongoing BoE rate cuts, could benefit consumer discretionary stocks. Within this sector, high-street retailers may also benefit from a reform in business rates.
Housebuilders
Meanwhile, housebuilders have already benefited from government plans such as commitments to remove red tape and the acceleration of home-building programs. Any further announcements to support the mortgage market or first-time buyers could further boost the sector. Such announcements coming at the same time that the BoE is cutting rates could be a boon for the sector. On the other side of the fence, an end to the stamp duty discount could negatively impact the market.
Infrastructure & engineering
Following on from the Investment summit, Labour has been clear about its aim to prioritize investment and growth in the UK. With this in mind, the Chancellor could announce major investments in infrastructure developments, boosting infrastructure stocks and civil engineering firms.
Gambling stocks
On the downside, gambling stocks have already fallen sharply amid reports that the Chancellor could double tax on online gambling firms. This could wipe out profitability for some firms in the UK. Should the government press ahead with dramatic tax hikes in the sector, the share price could fall further.
More broadly speaking, the FTSE 250 could see more impact than the FTSE 100 given the more domestic nature of the FTSE 250 compared to the FTSE 100 which is more internationally focused.
Conclusion
This is the new government's first Labour budget, so Rachel Reeve will want to strike the right tone while maintaining fiscal credibility. She will need to balance tax increases and spending cuts while maintaining the government's mission to grow the economy and create jobs. It's not an easy task, but with growth showing signs of improving and the BoE expected to continue cutting rates, the macro backdrop is on her side for now.




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
What UK GDP Means for GBP/AUD After a Key Resistance Break
The GBP/AUD breakout follows a Reserve Bank of Australia rate hike paired with a signal of a prolonged pause, draining support from the Aussie.

Pound forecast: GBP/USD and GBP/AUD in focus ahead of UK GDP
The GBP/USD fell below the 1.33 handle today as the dollar gained further ground against most major currencies. The GBP has remained supported against other currencies, thanks to a hawkish BoE and high UK interest rates.
GBP/USD Forecast: BoE Caution Leaves the Pound Searching for Direction
Although GBP/USD has gained close to 0.5% over the last three trading sessions, reflecting a period of relative strength for the British pound, today's session has started to show a more neutral tone and the bullish momentum seen earlier in the week has begun to slow.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.