



04 09 EU PRE OPEN
European stocks report | Berkeley Group | Vonovia | Suez | Caixabank...
Share this:
INDICES
Yesterday, European stocks were broadly lower. The Stoxx Europe 600 Index retreated 1.0%, Germany's DAX 30 slid 1.4%, France's CAC 40 fell 0.4% and the U.K.'s FTSE 100 was down 1.5%.
EUROPE ADVANCE/DECLINE
70% of STOXX 600 constituents traded lower or unchanged yesterday.
41% of the shares trade above their 20D MA vs 56% Wednesday (below the 20D moving average).
52% of the shares trade above their 200D MA vs 54% Wednesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 2.4pts to 29.01, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Autos
3mths relative low: none
Europe Best 3 sectors
automobiles & parts, travel & leisure, food & beverage
Europe worst 3 sectors
technology, basic resources, industrial goods & services
INTEREST RATE
The 10yr Bund yield fell 5bps to -0.47% (below its 20D MA). The 2yr-10yr yield spread rose 1bp to -21bps (below its 20D MA).
ECONOMIC DATA
GE 07:00: Jul Factory Orders MoM, exp.: 27.9%
FR 07:45: Jul Budget Balance, exp.: E-124.88B
FR 07:45: Jul Current Account, exp.: E-8.4B
EC 08:30: Aug Construction PMI, exp.: 48.9
FR 08:30: Aug Construction PMI, exp.: 49.4
GE 08:30: Aug Construction PMI, exp.: 47.1
UK 09:00: Aug New Car Sales YoY, exp.: 11.3%
UK 09:30: Aug Construction PMI, exp.: 58.1
EC 16:00: ECB Lane speech
MORNING TRADING
In Asian trading hours, EUR/USD was broadly flat at 1.1848 while GBP/USD edged up to 1.3283. USD/JPY was steady above the 106.00 level. AUD/USD was little changed at 0.7270. This morning, official data showed that Australia's retail sales grew 3.2% on month in July (+3.3% expected).
Spot gold rebounded to $1,936 an ounce.
#UK - IRELAND#
Berkeley Group, a property developer, released a trading update covering the period from May 1 to August 31: "Berkeley's trading has been resilient over this period and supports our existing guidance of £500 million of pre-tax profit for the full year and our commitment to our shareholder returns programme of £280 million per annum. (...) We now anticipate a more even split of profit between the first and second halves of the year, reflecting levels of production that have been better than initially anticipated and our decision not to furlough staff. (...) The value of underlying sales reservations for the first four months of the year is around 20% below the annualised run rate for last year, which is supportive of forward sales remaining around the year-end position of above £1.8 billion. This is a strong position, providing good visibility over the next two years of earnings."
#GERMANY#
Vonovia, a real estate company, said it will launch a cash capital increase via an accelerated bookbuilding process with a volume of about 1 billion euros. The company added: "The liquidity from this capital increase will be used to repay upcoming debt maturities in the fourth quarter of 2020. The additional proceeds from the issue are to be used for future growth opportunities that arise in the current environment and which Vonovia intends to pursue in line with its investment criteria." From a technical point of view, the previous upward breakout of 56 has triggered a new upmove. Furthermore, prices are supported by the 50-day simple moving average. Above 56, look for 67.

Source: GAIN Capital, TradingView
#FRANCE#
Suez's, an utility company, board has suggested CEO Bertrand Camus to seek alternative offers to Veolia's takeover approach, according to Chairman Philippe Varin cited by BFM Business television.
Pernod Ricard, an alcoholic beverages producer, was downgraded to "neutral" from "buy" at Citigroup.
#SPAIN#
Caixabank, a Spanish bank, reported that it is currently in talks with its peers Bankia to discuss an all-share merger between both institutions.
#FINLAND#
Sampo, a Finnish financial company, was upgraded to "buy" from "hold" at HSBC.
Yesterday, European stocks were broadly lower. The Stoxx Europe 600 Index retreated 1.0%, Germany's DAX 30 slid 1.4%, France's CAC 40 fell 0.4% and the U.K.'s FTSE 100 was down 1.5%.
EUROPE ADVANCE/DECLINE
70% of STOXX 600 constituents traded lower or unchanged yesterday.
41% of the shares trade above their 20D MA vs 56% Wednesday (below the 20D moving average).
52% of the shares trade above their 200D MA vs 54% Wednesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 2.4pts to 29.01, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Autos
3mths relative low: none
Europe Best 3 sectors
automobiles & parts, travel & leisure, food & beverage
Europe worst 3 sectors
technology, basic resources, industrial goods & services
INTEREST RATE
The 10yr Bund yield fell 5bps to -0.47% (below its 20D MA). The 2yr-10yr yield spread rose 1bp to -21bps (below its 20D MA).
ECONOMIC DATA
GE 07:00: Jul Factory Orders MoM, exp.: 27.9%
FR 07:45: Jul Budget Balance, exp.: E-124.88B
FR 07:45: Jul Current Account, exp.: E-8.4B
EC 08:30: Aug Construction PMI, exp.: 48.9
FR 08:30: Aug Construction PMI, exp.: 49.4
GE 08:30: Aug Construction PMI, exp.: 47.1
UK 09:00: Aug New Car Sales YoY, exp.: 11.3%
UK 09:30: Aug Construction PMI, exp.: 58.1
EC 16:00: ECB Lane speech
MORNING TRADING
In Asian trading hours, EUR/USD was broadly flat at 1.1848 while GBP/USD edged up to 1.3283. USD/JPY was steady above the 106.00 level. AUD/USD was little changed at 0.7270. This morning, official data showed that Australia's retail sales grew 3.2% on month in July (+3.3% expected).
Spot gold rebounded to $1,936 an ounce.
#UK - IRELAND#
Berkeley Group, a property developer, released a trading update covering the period from May 1 to August 31: "Berkeley's trading has been resilient over this period and supports our existing guidance of £500 million of pre-tax profit for the full year and our commitment to our shareholder returns programme of £280 million per annum. (...) We now anticipate a more even split of profit between the first and second halves of the year, reflecting levels of production that have been better than initially anticipated and our decision not to furlough staff. (...) The value of underlying sales reservations for the first four months of the year is around 20% below the annualised run rate for last year, which is supportive of forward sales remaining around the year-end position of above £1.8 billion. This is a strong position, providing good visibility over the next two years of earnings."
#GERMANY#
Vonovia, a real estate company, said it will launch a cash capital increase via an accelerated bookbuilding process with a volume of about 1 billion euros. The company added: "The liquidity from this capital increase will be used to repay upcoming debt maturities in the fourth quarter of 2020. The additional proceeds from the issue are to be used for future growth opportunities that arise in the current environment and which Vonovia intends to pursue in line with its investment criteria." From a technical point of view, the previous upward breakout of 56 has triggered a new upmove. Furthermore, prices are supported by the 50-day simple moving average. Above 56, look for 67.
Source: GAIN Capital, TradingView
#FRANCE#
Suez's, an utility company, board has suggested CEO Bertrand Camus to seek alternative offers to Veolia's takeover approach, according to Chairman Philippe Varin cited by BFM Business television.
Pernod Ricard, an alcoholic beverages producer, was downgraded to "neutral" from "buy" at Citigroup.
#SPAIN#
Caixabank, a Spanish bank, reported that it is currently in talks with its peers Bankia to discuss an all-share merger between both institutions.
#FINLAND#
Sampo, a Finnish financial company, was upgraded to "buy" from "hold" at HSBC.
INDICES
Yesterday, European stocks were broadly lower. The Stoxx Europe 600 Index retreated 1.0%, Germany's DAX 30 slid 1.4%, France's CAC 40 fell 0.4% and the U.K.'s FTSE 100 was down 1.5%.
EUROPE ADVANCE/DECLINE
70% of STOXX 600 constituents traded lower or unchanged yesterday.
41% of the shares trade above their 20D MA vs 56% Wednesday (below the 20D moving average).
52% of the shares trade above their 200D MA vs 54% Wednesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 2.4pts to 29.01, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Autos
3mths relative low: none
Europe Best 3 sectors
automobiles & parts, travel & leisure, food & beverage
Europe worst 3 sectors
technology, basic resources, industrial goods & services
INTEREST RATE
The 10yr Bund yield fell 5bps to -0.47% (below its 20D MA). The 2yr-10yr yield spread rose 1bp to -21bps (below its 20D MA).
ECONOMIC DATA
GE 07:00: Jul Factory Orders MoM, exp.: 27.9%
FR 07:45: Jul Budget Balance, exp.: E-124.88B
FR 07:45: Jul Current Account, exp.: E-8.4B
EC 08:30: Aug Construction PMI, exp.: 48.9
FR 08:30: Aug Construction PMI, exp.: 49.4
GE 08:30: Aug Construction PMI, exp.: 47.1
UK 09:00: Aug New Car Sales YoY, exp.: 11.3%
UK 09:30: Aug Construction PMI, exp.: 58.1
EC 16:00: ECB Lane speech
MORNING TRADING
In Asian trading hours, EUR/USD was broadly flat at 1.1848 while GBP/USD edged up to 1.3283. USD/JPY was steady above the 106.00 level. AUD/USD was little changed at 0.7270. This morning, official data showed that Australia's retail sales grew 3.2% on month in July (+3.3% expected).
Spot gold rebounded to $1,936 an ounce.
#UK - IRELAND#
Berkeley Group, a property developer, released a trading update covering the period from May 1 to August 31: "Berkeley's trading has been resilient over this period and supports our existing guidance of £500 million of pre-tax profit for the full year and our commitment to our shareholder returns programme of £280 million per annum. (...) We now anticipate a more even split of profit between the first and second halves of the year, reflecting levels of production that have been better than initially anticipated and our decision not to furlough staff. (...) The value of underlying sales reservations for the first four months of the year is around 20% below the annualised run rate for last year, which is supportive of forward sales remaining around the year-end position of above £1.8 billion. This is a strong position, providing good visibility over the next two years of earnings."
#GERMANY#
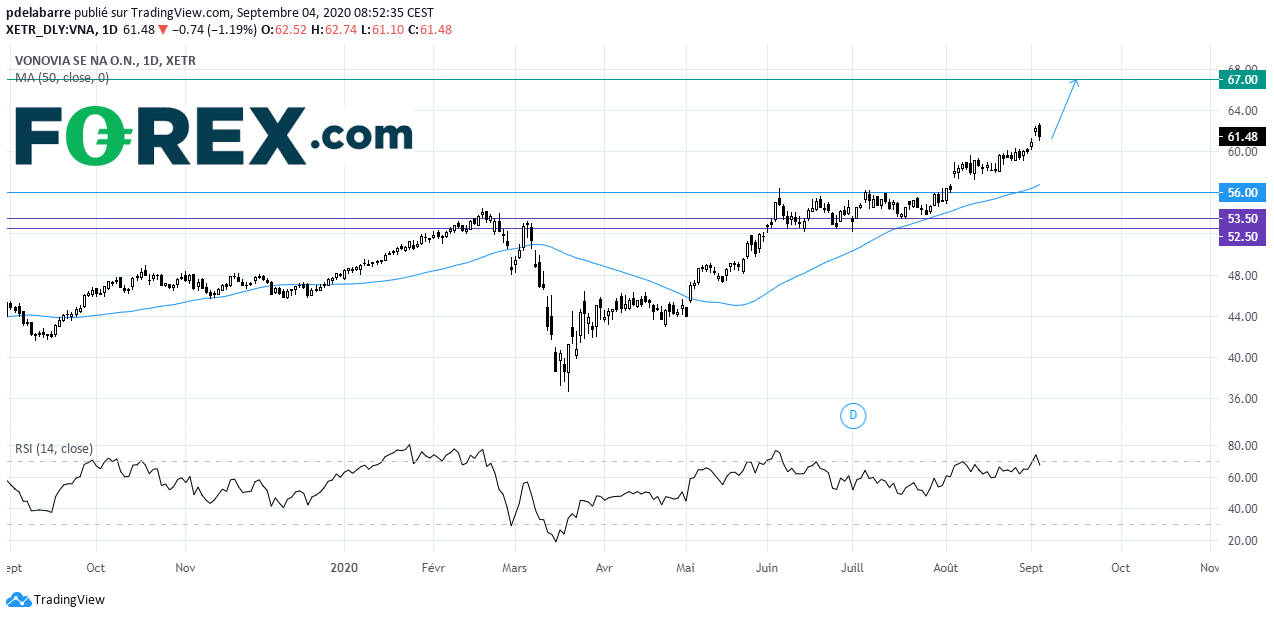
Vonovia, a real estate company, said it will launch a cash capital increase via an accelerated bookbuilding process with a volume of about 1 billion euros. The company added: "The liquidity from this capital increase will be used to repay upcoming debt maturities in the fourth quarter of 2020. The additional proceeds from the issue are to be used for future growth opportunities that arise in the current environment and which Vonovia intends to pursue in line with its investment criteria." From a technical point of view, the previous upward breakout of 56 has triggered a new upmove. Furthermore, prices are supported by the 50-day simple moving average. Above 56, look for 67.
Source: GAIN Capital, TradingView
#FRANCE#
Suez's, an utility company, board has suggested CEO Bertrand Camus to seek alternative offers to Veolia's takeover approach, according to Chairman Philippe Varin cited by BFM Business television.
Pernod Ricard, an alcoholic beverages producer, was downgraded to "neutral" from "buy" at Citigroup.
#SPAIN#
Caixabank, a Spanish bank, reported that it is currently in talks with its peers Bankia to discuss an all-share merger between both institutions.
#FINLAND#
Sampo, a Finnish financial company, was upgraded to "buy" from "hold" at HSBC.
Yesterday, European stocks were broadly lower. The Stoxx Europe 600 Index retreated 1.0%, Germany's DAX 30 slid 1.4%, France's CAC 40 fell 0.4% and the U.K.'s FTSE 100 was down 1.5%.
EUROPE ADVANCE/DECLINE
70% of STOXX 600 constituents traded lower or unchanged yesterday.
41% of the shares trade above their 20D MA vs 56% Wednesday (below the 20D moving average).
52% of the shares trade above their 200D MA vs 54% Wednesday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 2.4pts to 29.01, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Autos
3mths relative low: none
Europe Best 3 sectors
automobiles & parts, travel & leisure, food & beverage
Europe worst 3 sectors
technology, basic resources, industrial goods & services
INTEREST RATE
The 10yr Bund yield fell 5bps to -0.47% (below its 20D MA). The 2yr-10yr yield spread rose 1bp to -21bps (below its 20D MA).
ECONOMIC DATA
GE 07:00: Jul Factory Orders MoM, exp.: 27.9%
FR 07:45: Jul Budget Balance, exp.: E-124.88B
FR 07:45: Jul Current Account, exp.: E-8.4B
EC 08:30: Aug Construction PMI, exp.: 48.9
FR 08:30: Aug Construction PMI, exp.: 49.4
GE 08:30: Aug Construction PMI, exp.: 47.1
UK 09:00: Aug New Car Sales YoY, exp.: 11.3%
UK 09:30: Aug Construction PMI, exp.: 58.1
EC 16:00: ECB Lane speech
MORNING TRADING
In Asian trading hours, EUR/USD was broadly flat at 1.1848 while GBP/USD edged up to 1.3283. USD/JPY was steady above the 106.00 level. AUD/USD was little changed at 0.7270. This morning, official data showed that Australia's retail sales grew 3.2% on month in July (+3.3% expected).
Spot gold rebounded to $1,936 an ounce.
#UK - IRELAND#
Berkeley Group, a property developer, released a trading update covering the period from May 1 to August 31: "Berkeley's trading has been resilient over this period and supports our existing guidance of £500 million of pre-tax profit for the full year and our commitment to our shareholder returns programme of £280 million per annum. (...) We now anticipate a more even split of profit between the first and second halves of the year, reflecting levels of production that have been better than initially anticipated and our decision not to furlough staff. (...) The value of underlying sales reservations for the first four months of the year is around 20% below the annualised run rate for last year, which is supportive of forward sales remaining around the year-end position of above £1.8 billion. This is a strong position, providing good visibility over the next two years of earnings."
#GERMANY#
Vonovia, a real estate company, said it will launch a cash capital increase via an accelerated bookbuilding process with a volume of about 1 billion euros. The company added: "The liquidity from this capital increase will be used to repay upcoming debt maturities in the fourth quarter of 2020. The additional proceeds from the issue are to be used for future growth opportunities that arise in the current environment and which Vonovia intends to pursue in line with its investment criteria." From a technical point of view, the previous upward breakout of 56 has triggered a new upmove. Furthermore, prices are supported by the 50-day simple moving average. Above 56, look for 67.
Source: GAIN Capital, TradingView
#FRANCE#
Suez's, an utility company, board has suggested CEO Bertrand Camus to seek alternative offers to Veolia's takeover approach, according to Chairman Philippe Varin cited by BFM Business television.
Pernod Ricard, an alcoholic beverages producer, was downgraded to "neutral" from "buy" at Citigroup.
#SPAIN#
Caixabank, a Spanish bank, reported that it is currently in talks with its peers Bankia to discuss an all-share merger between both institutions.
#FINLAND#
Sampo, a Finnish financial company, was upgraded to "buy" from "hold" at HSBC.
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.