



15 09 EU PRE OPEN
European stocks report | Ocado | Daimler | Ferrovial | Hennes & Mauritz...
Share this:
INDICES
Yesterday, European stocks were mixed. The Stoxx Europe 600 Index was up 0.15%, France's CAC 40 advanced 0.35%, while Germany's DAX 30 eased 0.07% and the U.K.'s FTSE 100 declined 0.10%.
EUROPE ADVANCE/DECLINE
52% of STOXX 600 constituents traded higher yesterday.
55% of the shares trade above their 20D MA vs 53% Friday (below the 20D moving average).
57% of the shares trade above their 200D MA vs 55% Friday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.16pt to 22.57, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Pers. & House. Goods
3mths relative low: Utilities, Energy
Europe Best 3 sectors
travel & leisure, technology, banks
Europe worst 3 sectors
energy, utilities, insurance
INTEREST RATE
The 10yr Bund yield fell 5bps to -0.48% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -22bps (above its 20D MA).
ECONOMIC DATA
UK 07:00: Jun Employment chg, exp.: -220K
UK 07:00: Jul Average Earnings excl. Bonus, exp.: -0.2%
UK 07:00: Jul Average Earnings incl. Bonus, exp.: -1.2%
UK 07:00: Jul Unemployment Rate, exp.: 3.9%
UK 07:00: Aug Claimant Count chg, exp.: 94.4K
FR 07:45: Aug Inflation Rate YoY final, exp.: 0.8%
FR 07:45: Aug Inflation Rate MoM final, exp.: 0.4%
FR 07:45: Aug Harmonised Inflation Rate YoY final, exp.: 0.9%
FR 07:45: Aug Harmonised Inflation Rate MoM final, exp.: 0.4%
FR 09:00: IEA Oil Market Report
EC 10:00: Q2 Labour Cost Idx YoY, exp.: 3.4%
EC 10:00: Q2 Wage Growth YoY, exp.: 3.4%
EC 10:00: Sep ZEW Economic Sentiment Idx, exp.: 64
GE 10:00: Sep ZEW Current Conditions, exp.: -81.3
GE 10:00: Sep ZEW Economic Sentiment Idx, exp.: 71.5
MORNING TRADING
In Asian trading hours, EUR/USD rose further to 1.1881 while GBP/USD was little changed at 1.2843. USD/JPY remained subdued at 105.64. AUD/USD climbed to 0.7309, lifted by better-than-expected Chinese data. This morning, official data showed that China's industrial production rose 5.6% on year in August (+5.1% expected) and retail sales grew 0.5% (flat expected).
Spot gold advanced to $1,965 an ounce.
#UK - IRELAND#
Ocado, a British online supermarket, posted a 3Q trading statement: "Retail Revenue grew 52% as channel shift to online grocery in UK continues. (...) Retail sales grew faster compared to Q2 as demand remained high versus a seasonally softer quarter in Q3 2019. (...) While uncertainties remain over the scale, and duration, of the ongoing impact of social distancing restrictions in the UK, the strong trading performance of Ocado Retail in the first three quarters of the year, combined with the impact of operational leverage in the retail business, suggest, given current trends, a full year EBITDA result for Ocado Group of at least £40m."
AstraZeneca's, a pharmaceutical giant, coronavirus vaccine trial in the U.S. remains on hold as regulators are still examining the serious side effect on the British patient, according to Reuters.
FirstGroup, a transport group, released a trading update for the period from April 1 to August 31: "The Group is now expecting to deliver a small adjusted operating profit for the seasonally weaker first half of the financial year, ahead of our expectations earlier this summer."
Rio Tinto, a giant miner, was upgraded to "overweight" from "neutral" at JPMorgan.
BHP Group, a multinational mining group, was upgraded to "buy" from "neutral" at Goldman Sachs.
#GERMANY#
Daimler, a vehicle manufacturer, and the U.S. regulators have reached a 1.5 billion dollars settlement, resolving alleged violations of the Clean Air Act and California law associated with emissions cheating in Mercedes-Benz diesel vehicles, according to the U.S. Department of Justice.
From a daily point of view, the share remains supported by a rising trend line drawn since March. The share has broken above the resistance area between 43.5E (previous top of August) and 45E (horizontal resistance of February), releasing a new upside potential. above the overlap threshold at 41E look for the horizontal resistance of November 2019 at 54.4E and 60E in extension.

Source: GAIN Capital, TradingView
#FRANCE#
Bureau Veritas, an inspection and certification company, was upgraded to "buy" from "hold" at HSBC.
#SPAIN#
Ferrovial, an infrastructure group, announced that it has agreed to sell its 49% stake in Portugal's Norte Litoral highway and its 48% stake in the Via do Infante highway to a fund managed by DIF Capital Partners a total consideration of 171 million euros.
#ITALY#
Leonardo, an aerospace and defence, was upgraded to "buy" from "hold" at Societe Generale.
#SWITZERLAND#
SGS, a testing and certification services provider, was upgraded to "hold" from "reduce" at HSBC.
#SWEDEN#
Hennes & Mauritz, a clothing-retail company, announced that 3Q net sales declined 19% on year (-16% in local currencies) to 50.87 billion Swedish krona. The company said the group's recovery is "better than expected" and "preliminary results show profit before tax of approximately SEK 2 billion".
Yesterday, European stocks were mixed. The Stoxx Europe 600 Index was up 0.15%, France's CAC 40 advanced 0.35%, while Germany's DAX 30 eased 0.07% and the U.K.'s FTSE 100 declined 0.10%.
EUROPE ADVANCE/DECLINE
52% of STOXX 600 constituents traded higher yesterday.
55% of the shares trade above their 20D MA vs 53% Friday (below the 20D moving average).
57% of the shares trade above their 200D MA vs 55% Friday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.16pt to 22.57, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Pers. & House. Goods
3mths relative low: Utilities, Energy
Europe Best 3 sectors
travel & leisure, technology, banks
Europe worst 3 sectors
energy, utilities, insurance
INTEREST RATE
The 10yr Bund yield fell 5bps to -0.48% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -22bps (above its 20D MA).
ECONOMIC DATA
UK 07:00: Jun Employment chg, exp.: -220K
UK 07:00: Jul Average Earnings excl. Bonus, exp.: -0.2%
UK 07:00: Jul Average Earnings incl. Bonus, exp.: -1.2%
UK 07:00: Jul Unemployment Rate, exp.: 3.9%
UK 07:00: Aug Claimant Count chg, exp.: 94.4K
FR 07:45: Aug Inflation Rate YoY final, exp.: 0.8%
FR 07:45: Aug Inflation Rate MoM final, exp.: 0.4%
FR 07:45: Aug Harmonised Inflation Rate YoY final, exp.: 0.9%
FR 07:45: Aug Harmonised Inflation Rate MoM final, exp.: 0.4%
FR 09:00: IEA Oil Market Report
EC 10:00: Q2 Labour Cost Idx YoY, exp.: 3.4%
EC 10:00: Q2 Wage Growth YoY, exp.: 3.4%
EC 10:00: Sep ZEW Economic Sentiment Idx, exp.: 64
GE 10:00: Sep ZEW Current Conditions, exp.: -81.3
GE 10:00: Sep ZEW Economic Sentiment Idx, exp.: 71.5
MORNING TRADING
In Asian trading hours, EUR/USD rose further to 1.1881 while GBP/USD was little changed at 1.2843. USD/JPY remained subdued at 105.64. AUD/USD climbed to 0.7309, lifted by better-than-expected Chinese data. This morning, official data showed that China's industrial production rose 5.6% on year in August (+5.1% expected) and retail sales grew 0.5% (flat expected).
Spot gold advanced to $1,965 an ounce.
#UK - IRELAND#
Ocado, a British online supermarket, posted a 3Q trading statement: "Retail Revenue grew 52% as channel shift to online grocery in UK continues. (...) Retail sales grew faster compared to Q2 as demand remained high versus a seasonally softer quarter in Q3 2019. (...) While uncertainties remain over the scale, and duration, of the ongoing impact of social distancing restrictions in the UK, the strong trading performance of Ocado Retail in the first three quarters of the year, combined with the impact of operational leverage in the retail business, suggest, given current trends, a full year EBITDA result for Ocado Group of at least £40m."
AstraZeneca's, a pharmaceutical giant, coronavirus vaccine trial in the U.S. remains on hold as regulators are still examining the serious side effect on the British patient, according to Reuters.
FirstGroup, a transport group, released a trading update for the period from April 1 to August 31: "The Group is now expecting to deliver a small adjusted operating profit for the seasonally weaker first half of the financial year, ahead of our expectations earlier this summer."
Rio Tinto, a giant miner, was upgraded to "overweight" from "neutral" at JPMorgan.
BHP Group, a multinational mining group, was upgraded to "buy" from "neutral" at Goldman Sachs.
#GERMANY#
Daimler, a vehicle manufacturer, and the U.S. regulators have reached a 1.5 billion dollars settlement, resolving alleged violations of the Clean Air Act and California law associated with emissions cheating in Mercedes-Benz diesel vehicles, according to the U.S. Department of Justice.
From a daily point of view, the share remains supported by a rising trend line drawn since March. The share has broken above the resistance area between 43.5E (previous top of August) and 45E (horizontal resistance of February), releasing a new upside potential. above the overlap threshold at 41E look for the horizontal resistance of November 2019 at 54.4E and 60E in extension.
Source: GAIN Capital, TradingView
#FRANCE#
Bureau Veritas, an inspection and certification company, was upgraded to "buy" from "hold" at HSBC.
#SPAIN#
Ferrovial, an infrastructure group, announced that it has agreed to sell its 49% stake in Portugal's Norte Litoral highway and its 48% stake in the Via do Infante highway to a fund managed by DIF Capital Partners a total consideration of 171 million euros.
#ITALY#
Leonardo, an aerospace and defence, was upgraded to "buy" from "hold" at Societe Generale.
#SWITZERLAND#
SGS, a testing and certification services provider, was upgraded to "hold" from "reduce" at HSBC.
#SWEDEN#
Hennes & Mauritz, a clothing-retail company, announced that 3Q net sales declined 19% on year (-16% in local currencies) to 50.87 billion Swedish krona. The company said the group's recovery is "better than expected" and "preliminary results show profit before tax of approximately SEK 2 billion".
INDICES
Yesterday, European stocks were mixed. The Stoxx Europe 600 Index was up 0.15%, France's CAC 40 advanced 0.35%, while Germany's DAX 30 eased 0.07% and the U.K.'s FTSE 100 declined 0.10%.
EUROPE ADVANCE/DECLINE
52% of STOXX 600 constituents traded higher yesterday.
55% of the shares trade above their 20D MA vs 53% Friday (below the 20D moving average).
57% of the shares trade above their 200D MA vs 55% Friday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.16pt to 22.57, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Pers. & House. Goods
3mths relative low: Utilities, Energy
Europe Best 3 sectors
travel & leisure, technology, banks
Europe worst 3 sectors
energy, utilities, insurance
INTEREST RATE
The 10yr Bund yield fell 5bps to -0.48% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -22bps (above its 20D MA).
ECONOMIC DATA
UK 07:00: Jun Employment chg, exp.: -220K
UK 07:00: Jul Average Earnings excl. Bonus, exp.: -0.2%
UK 07:00: Jul Average Earnings incl. Bonus, exp.: -1.2%
UK 07:00: Jul Unemployment Rate, exp.: 3.9%
UK 07:00: Aug Claimant Count chg, exp.: 94.4K
FR 07:45: Aug Inflation Rate YoY final, exp.: 0.8%
FR 07:45: Aug Inflation Rate MoM final, exp.: 0.4%
FR 07:45: Aug Harmonised Inflation Rate YoY final, exp.: 0.9%
FR 07:45: Aug Harmonised Inflation Rate MoM final, exp.: 0.4%
FR 09:00: IEA Oil Market Report
EC 10:00: Q2 Labour Cost Idx YoY, exp.: 3.4%
EC 10:00: Q2 Wage Growth YoY, exp.: 3.4%
EC 10:00: Sep ZEW Economic Sentiment Idx, exp.: 64
GE 10:00: Sep ZEW Current Conditions, exp.: -81.3
GE 10:00: Sep ZEW Economic Sentiment Idx, exp.: 71.5
MORNING TRADING
In Asian trading hours, EUR/USD rose further to 1.1881 while GBP/USD was little changed at 1.2843. USD/JPY remained subdued at 105.64. AUD/USD climbed to 0.7309, lifted by better-than-expected Chinese data. This morning, official data showed that China's industrial production rose 5.6% on year in August (+5.1% expected) and retail sales grew 0.5% (flat expected).
Spot gold advanced to $1,965 an ounce.
#UK - IRELAND#
Ocado, a British online supermarket, posted a 3Q trading statement: "Retail Revenue grew 52% as channel shift to online grocery in UK continues. (...) Retail sales grew faster compared to Q2 as demand remained high versus a seasonally softer quarter in Q3 2019. (...) While uncertainties remain over the scale, and duration, of the ongoing impact of social distancing restrictions in the UK, the strong trading performance of Ocado Retail in the first three quarters of the year, combined with the impact of operational leverage in the retail business, suggest, given current trends, a full year EBITDA result for Ocado Group of at least £40m."
AstraZeneca's, a pharmaceutical giant, coronavirus vaccine trial in the U.S. remains on hold as regulators are still examining the serious side effect on the British patient, according to Reuters.
FirstGroup, a transport group, released a trading update for the period from April 1 to August 31: "The Group is now expecting to deliver a small adjusted operating profit for the seasonally weaker first half of the financial year, ahead of our expectations earlier this summer."
Rio Tinto, a giant miner, was upgraded to "overweight" from "neutral" at JPMorgan.
BHP Group, a multinational mining group, was upgraded to "buy" from "neutral" at Goldman Sachs.
#GERMANY#
Daimler, a vehicle manufacturer, and the U.S. regulators have reached a 1.5 billion dollars settlement, resolving alleged violations of the Clean Air Act and California law associated with emissions cheating in Mercedes-Benz diesel vehicles, according to the U.S. Department of Justice.
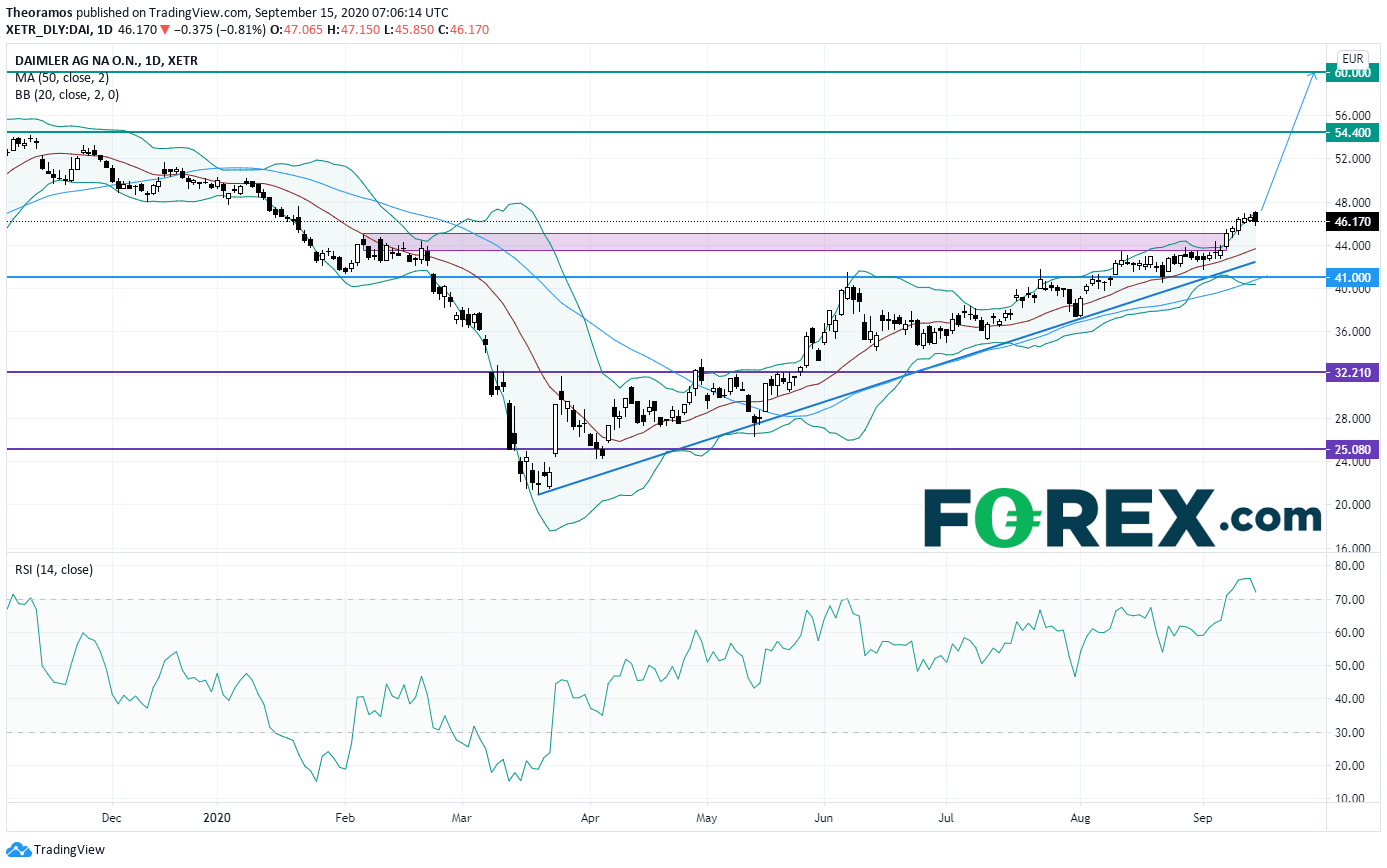
From a daily point of view, the share remains supported by a rising trend line drawn since March. The share has broken above the resistance area between 43.5E (previous top of August) and 45E (horizontal resistance of February), releasing a new upside potential. above the overlap threshold at 41E look for the horizontal resistance of November 2019 at 54.4E and 60E in extension.
Source: GAIN Capital, TradingView
#FRANCE#
Bureau Veritas, an inspection and certification company, was upgraded to "buy" from "hold" at HSBC.
#SPAIN#
Ferrovial, an infrastructure group, announced that it has agreed to sell its 49% stake in Portugal's Norte Litoral highway and its 48% stake in the Via do Infante highway to a fund managed by DIF Capital Partners a total consideration of 171 million euros.
#ITALY#
Leonardo, an aerospace and defence, was upgraded to "buy" from "hold" at Societe Generale.
#SWITZERLAND#
SGS, a testing and certification services provider, was upgraded to "hold" from "reduce" at HSBC.
#SWEDEN#
Hennes & Mauritz, a clothing-retail company, announced that 3Q net sales declined 19% on year (-16% in local currencies) to 50.87 billion Swedish krona. The company said the group's recovery is "better than expected" and "preliminary results show profit before tax of approximately SEK 2 billion".
Yesterday, European stocks were mixed. The Stoxx Europe 600 Index was up 0.15%, France's CAC 40 advanced 0.35%, while Germany's DAX 30 eased 0.07% and the U.K.'s FTSE 100 declined 0.10%.
EUROPE ADVANCE/DECLINE
52% of STOXX 600 constituents traded higher yesterday.
55% of the shares trade above their 20D MA vs 53% Friday (below the 20D moving average).
57% of the shares trade above their 200D MA vs 55% Friday (above the 20D moving average).
The Euro Stoxx 50 Volatility index eased 1.16pt to 22.57, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Pers. & House. Goods
3mths relative low: Utilities, Energy
Europe Best 3 sectors
travel & leisure, technology, banks
Europe worst 3 sectors
energy, utilities, insurance
INTEREST RATE
The 10yr Bund yield fell 5bps to -0.48% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -22bps (above its 20D MA).
ECONOMIC DATA
UK 07:00: Jun Employment chg, exp.: -220K
UK 07:00: Jul Average Earnings excl. Bonus, exp.: -0.2%
UK 07:00: Jul Average Earnings incl. Bonus, exp.: -1.2%
UK 07:00: Jul Unemployment Rate, exp.: 3.9%
UK 07:00: Aug Claimant Count chg, exp.: 94.4K
FR 07:45: Aug Inflation Rate YoY final, exp.: 0.8%
FR 07:45: Aug Inflation Rate MoM final, exp.: 0.4%
FR 07:45: Aug Harmonised Inflation Rate YoY final, exp.: 0.9%
FR 07:45: Aug Harmonised Inflation Rate MoM final, exp.: 0.4%
FR 09:00: IEA Oil Market Report
EC 10:00: Q2 Labour Cost Idx YoY, exp.: 3.4%
EC 10:00: Q2 Wage Growth YoY, exp.: 3.4%
EC 10:00: Sep ZEW Economic Sentiment Idx, exp.: 64
GE 10:00: Sep ZEW Current Conditions, exp.: -81.3
GE 10:00: Sep ZEW Economic Sentiment Idx, exp.: 71.5
MORNING TRADING
In Asian trading hours, EUR/USD rose further to 1.1881 while GBP/USD was little changed at 1.2843. USD/JPY remained subdued at 105.64. AUD/USD climbed to 0.7309, lifted by better-than-expected Chinese data. This morning, official data showed that China's industrial production rose 5.6% on year in August (+5.1% expected) and retail sales grew 0.5% (flat expected).
Spot gold advanced to $1,965 an ounce.
#UK - IRELAND#
Ocado, a British online supermarket, posted a 3Q trading statement: "Retail Revenue grew 52% as channel shift to online grocery in UK continues. (...) Retail sales grew faster compared to Q2 as demand remained high versus a seasonally softer quarter in Q3 2019. (...) While uncertainties remain over the scale, and duration, of the ongoing impact of social distancing restrictions in the UK, the strong trading performance of Ocado Retail in the first three quarters of the year, combined with the impact of operational leverage in the retail business, suggest, given current trends, a full year EBITDA result for Ocado Group of at least £40m."
AstraZeneca's, a pharmaceutical giant, coronavirus vaccine trial in the U.S. remains on hold as regulators are still examining the serious side effect on the British patient, according to Reuters.
FirstGroup, a transport group, released a trading update for the period from April 1 to August 31: "The Group is now expecting to deliver a small adjusted operating profit for the seasonally weaker first half of the financial year, ahead of our expectations earlier this summer."
Rio Tinto, a giant miner, was upgraded to "overweight" from "neutral" at JPMorgan.
BHP Group, a multinational mining group, was upgraded to "buy" from "neutral" at Goldman Sachs.
#GERMANY#
Daimler, a vehicle manufacturer, and the U.S. regulators have reached a 1.5 billion dollars settlement, resolving alleged violations of the Clean Air Act and California law associated with emissions cheating in Mercedes-Benz diesel vehicles, according to the U.S. Department of Justice.
From a daily point of view, the share remains supported by a rising trend line drawn since March. The share has broken above the resistance area between 43.5E (previous top of August) and 45E (horizontal resistance of February), releasing a new upside potential. above the overlap threshold at 41E look for the horizontal resistance of November 2019 at 54.4E and 60E in extension.
Source: GAIN Capital, TradingView
#FRANCE#
Bureau Veritas, an inspection and certification company, was upgraded to "buy" from "hold" at HSBC.
#SPAIN#
Ferrovial, an infrastructure group, announced that it has agreed to sell its 49% stake in Portugal's Norte Litoral highway and its 48% stake in the Via do Infante highway to a fund managed by DIF Capital Partners a total consideration of 171 million euros.
#ITALY#
Leonardo, an aerospace and defence, was upgraded to "buy" from "hold" at Societe Generale.
#SWITZERLAND#
SGS, a testing and certification services provider, was upgraded to "hold" from "reduce" at HSBC.
#SWEDEN#
Hennes & Mauritz, a clothing-retail company, announced that 3Q net sales declined 19% on year (-16% in local currencies) to 50.87 billion Swedish krona. The company said the group's recovery is "better than expected" and "preliminary results show profit before tax of approximately SEK 2 billion".
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USDJPY Forecast Intervention Fears Clash with Dollar Strength
Recent trading sessions have produced mixed results for the Japanese yen. By the end of last week, USD/JPY had fallen by more than 1.00%, reflecting a modest recovery in the yen. However, the start of this week has seen the pair move slightly back in favor of the U.S. dollar, posting gains of around 0.04%.
AUD/USD forecast: Currency Pair of the Week | September 28, 2026
The week has started with stocks, gold, silver and bitcoin all falling, as crude oil rebounded and bond yields pushed further higher. Trump refusing to agree to Tehran’s proposal to re-open the Strait of Hormuz has left the markets disappointed. Still, reports that mediators are expected to hold talks with the two sides on an amended version of the 7-day proposal that Iran presented, keeps hopes alive that we may see some progress.


EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.