

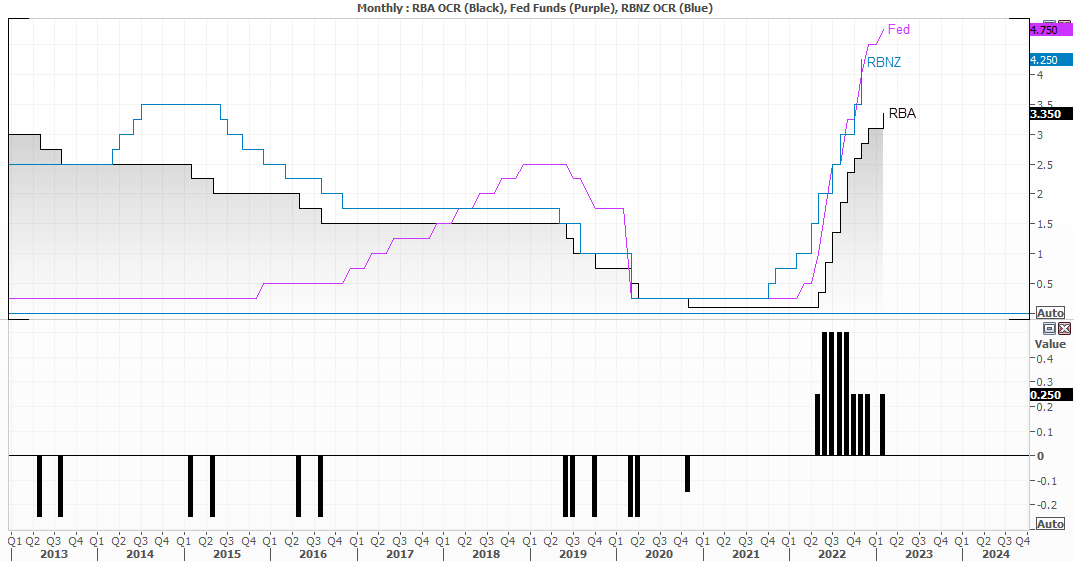


Another 25bp hawkish hike from the RBA
The RBA hiked the overnight cash rate by 25bp to 3.35% - its highest level since September 2012 – and warned of further increases in the months ahead.
Share this:

Summary of the RBA’s February 2023 statement:
- The RBA hiked the cash rate target by 25 basis points to 3.35%
- Underlying inflation was above expectations at 6.9%
- Strong domestic demand is adding to the inflationary pressures
- CPI is expected to decline this year due to global factors and slower growth in domestic demand
- Medium-term inflation expectations remain well anchored, and it is important that this remains the case
- The labour market remains very tight
- Wages growth is expected to continue picking up due to the tight labour market and higher inflation
- The board will continue to pay close attention to labour costs and the price-setting behaviour of firms in the period ahead
- Further increases in interest rates will be needed over the months ahead
The RBA hiked the overnight cash rate by 25bp to 3.35% - its highest level since September 2012 – and warned of further increases in the months ahead. The two key words here are ‘increases’ and ‘months’, as it implies more than one hike over the coming months. And with rates at 3.35% it means the market pricing and consensus among economists for a terminal rate of 3.6% is not correct.
Given that the employment situation remains robust (or tight, as they say), inflation is higher than they expected and ‘strong domestic demand is adding to inflationary pressures’, we have several green lights for a hike in March and perhaps in May. Perhaps we’re closer to the elusive pause they teased us with last year, but I see no immediate threat of one in that statement.
And whilst the RBA expect CPI to decline as global factors and growth in domestic demands slows, what is going to happen if they do not slow quickly enough? Yep, more hikes. For now, a March hike seems like a done deal and I live in hope they hint at a pause, but I will not hang my hat on that given the data overall and strong levels of inflation.
The RBA’s quarterly SOMP is due to drop on Friday
The focus now shifts to Friday’s quarterly SOMP (Statement on Monetary Policy) which includes their revised forecasts.
The past three reports have seen growth forecasts decelerate and inflation upwardly revised. Given the new monthly annual CPI read rose to 8.1% y/y, and trimmed mean and median inflation beat expectations, there’s a decent chance we’ll see CPI revised higher once more – which in itself could signal another rate hike or two. Wage growth has also been revised higher over the past three reports and could be taken as another hawkish cue should it be revised higher for a fourth.
AUD/USD 1-hour chart:
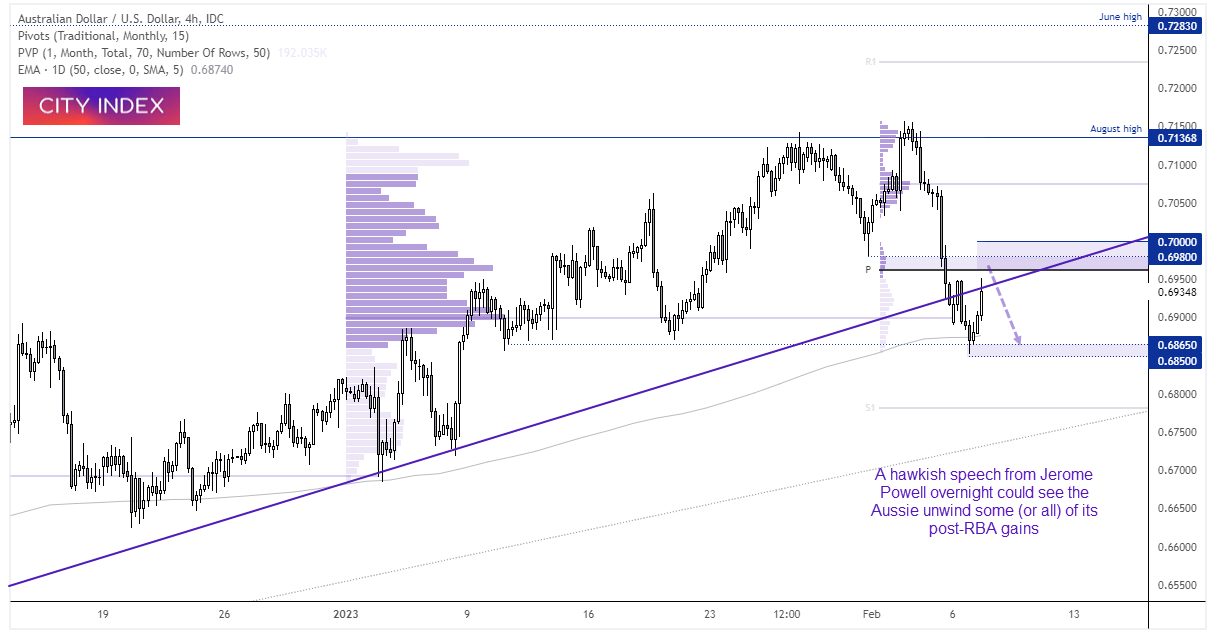
The Aussie bounce around 1% after the rate decision, but it is debatable as to whether it can retain its strength if Jerome Powell delivers a hawkish message overnight. The Fed’s rate remains above the RBA’s, with a higher expected terminal rate.
AUD/USD found support around the 50-day EMA and has since spiked higher, but bears may want to seek evidence of weakness around 0.6900 as it houses the monthly pivot point and broken trendline. Of course, should Powell fail to deliver the hawkish message, then it leaves AUD (and other FX majors) more wriggle room to unwind some of their post-NFP losses.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.