



Asian Open Consumer confidence and the dollar are on a high
The dollar hit fresh highs overnight, broadly up against all majors and weighing on further on metals. Yields also turned at interesting levels.
Share this:
Learn more about trading indices
The latest US stimulus package, worth slightly over 8% of US GDP, returns to the House on Tuesday for final approval and is likely to be signed off by President Biden shortly after.
Its key features which include a $1400 payment for individuals with incomes of $75,000 or less ($150k for couples) are expected to see US GDP growth rise to 7% this year, the highest rate since 1984. Within that, Q2 2021 GDP is expected to rise by `11%, the biggest single quarterly rise since 1978.
Reinforcing the rapidly improving global economic outlook, Westpac’s respected Chief Economist, Bill Evans today raised his Australian 2021 GDP growth forecast from 4% to 4.5% following last week’s stronger-than-expected Q4 Australian GDP print.
Although the better GDP number reflects a broad-based recovery, it was consumer spending that provided the majority of the beat. This should ensure that another strong consumer sentiment survey (already near-decade highs) is released on Wednesday, as households draw on their large pile of accumulated savings.
The stronger Australian GDP profile is supportive of the ASX200. Additionally, the ASX200 is likely to weather a continued rise in global yields better than other countries' tech stock heavy indices. As noted previously, higher yields are supportive of the bank and resource stocks that are well represented in the ASX200.
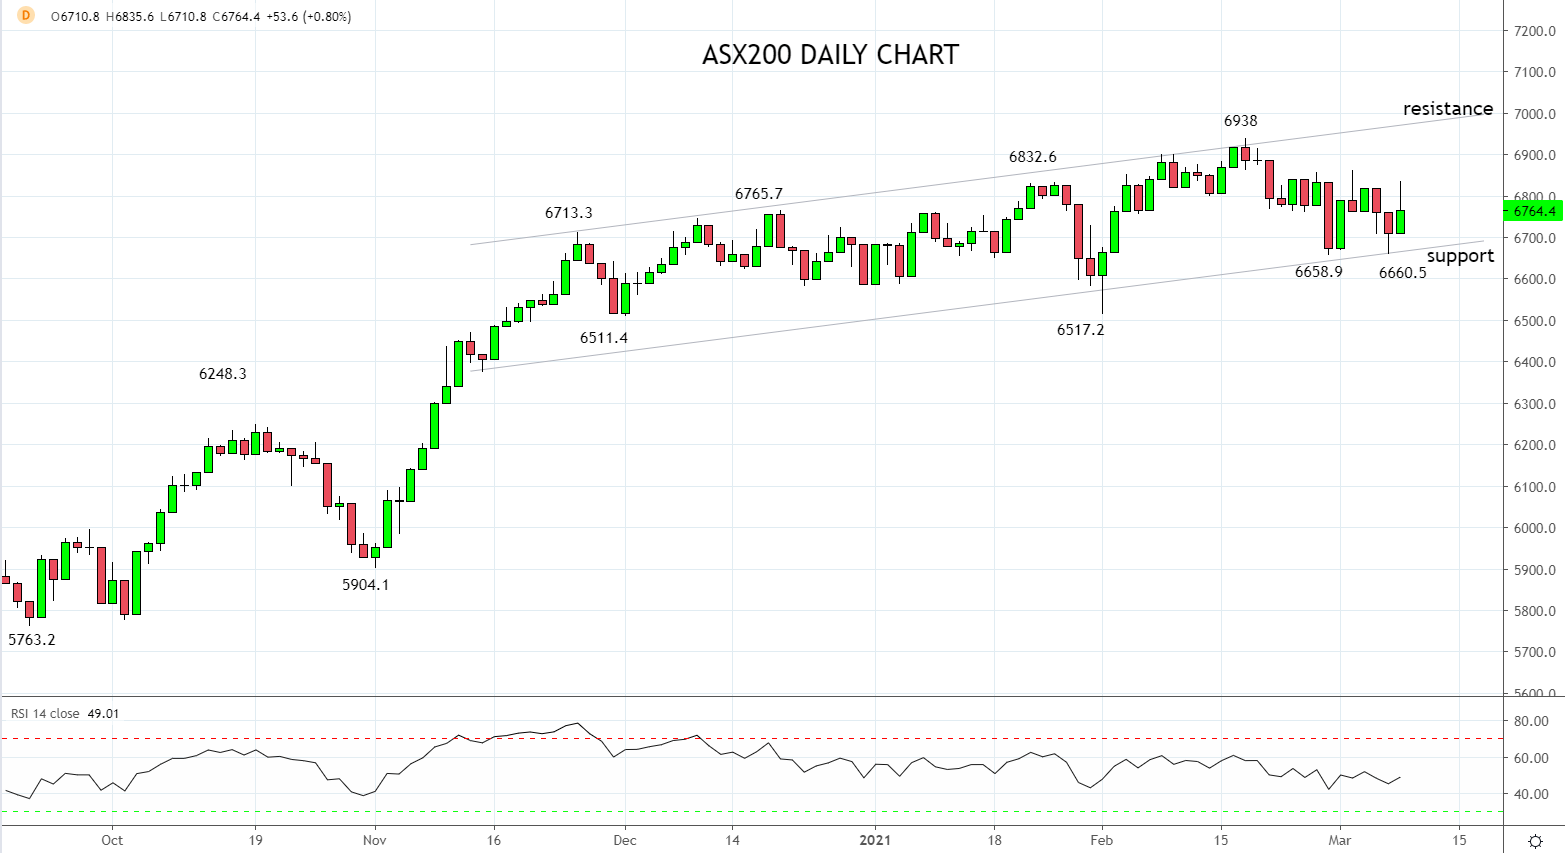
Technically, the ASX200 continues to trade in a choppy fashion, within a well-established uptrend channel. An environment that is suitable for short-term traders, not so good for traders that prefer trending markets.
Trend channel resistance is currently coming in near 7000, where short-term traders may look to short the market in anticipation of lower prices to rebuy. Trend channel support is viewed 6660 area, where short-term buyers are expected to emerge in anticipation of further range trading ahead.
Source Tradingview. The figures stated areas of the 8th of March 2021. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.