



Cable reigns supreme
GBP/USD posts largest pip gain of the week against its major pairs: Charts
Share this:

The US Dollar was bullish against most of its major pairs on Friday with the exception of the GBP and JPY.
On Monday, no major economic data is expected to be released.
The Euro was bearish against most of its major pairs with the exception of the AUD. In Europe, September Consumer Price Index was released at +0.1%, as expected, vs -0.4% in August. The last phase of Brexit talks should end today. Boris Johnson and EU Commission President Von Der Leyen will hold talk on next steps tomorrow.
The Australian dollar was bearish against all of its major pairs.
Here is a review of key economic data over the past week:
On the jobs front, Change in Nonfarm Payrolls dropped to 661K on month in September (859K expected), from a revised 1,489K in August. The Unemployment Rate declined to 7.9% on month in September (8.2% expected), from 8.4% in August. Initial Jobless Claims fell to 837K for the week ending September 26th (850K expected), from a revised 873K in the week before. Continuing Claims dropped to 11,767K for the week ending September 19th (12,200K expected), from a revised 12,747K in the prior week. Finally, Automatic Data Processing's Employment Change rose to 749K on month in September (649K expected), from a revised 481K in August.
Regarding sentiment, The University of Michigan's Consumer Sentiment Index increased to 80.4 on month in the September final reading (79.0 expected), from 78.9 in the September preliminary reading. The Conference Board's Consumer Confidence Index spiked to 101.8 on month in September (90.0 expected), from a revised 86.3 in August.
Looking at consumers, Personal Income slipped 2.7% on month in August (-2.5% expected), compared to a revised +0.5% in July. Personal Spending rose 1.0% on month in August (+0.8% expected), compared to a revised +1.5% in July.
On the housing data front, The Mortgage Bankers Association's Mortgage Applications dropped 4.8% for the week ending September 25th, compared to +6.8% in the week before. Pending Home Sales surged 8.8% on month in August (+3.1% expected), compared to +5.9% in July.
Factory Orders rose 0.7% on month in August (+0.9% expected), compared to a revised +6.5% in July. Durable Goods Orders increased 0.5% on month in the August final reading (+0.4% expected), compared to +0.4% in the August preliminary reading. Markit's US Manufacturing Purchasing Managers' Index unexpectedly declined to 53.2 on month in the September final reading (53.5 expected), from 53.5 in the September preliminary reading. Construction Spending increased 1.4% on month in August (+0.7% expected), compared to a revised +0.7% in July. Wholesale Inventories unexpectedly rose 0.5% on month in the August preliminary reading (-0.1% expected), compared to a revised -0.1% in the July final reading.
U.S. GDP rose to -31.4% on quarter in the second quarter third reading (-31.7% expected), from -31.7% in the second quarter second reading.
The GBP/USD posted the largest weekly gain of 197 pips. Key resistance remains in play at the 1.2985 level. The bias remains bearish on a daily chart until 1.2985 is broken to the downside.

Source: GAIN Capital, TradingView
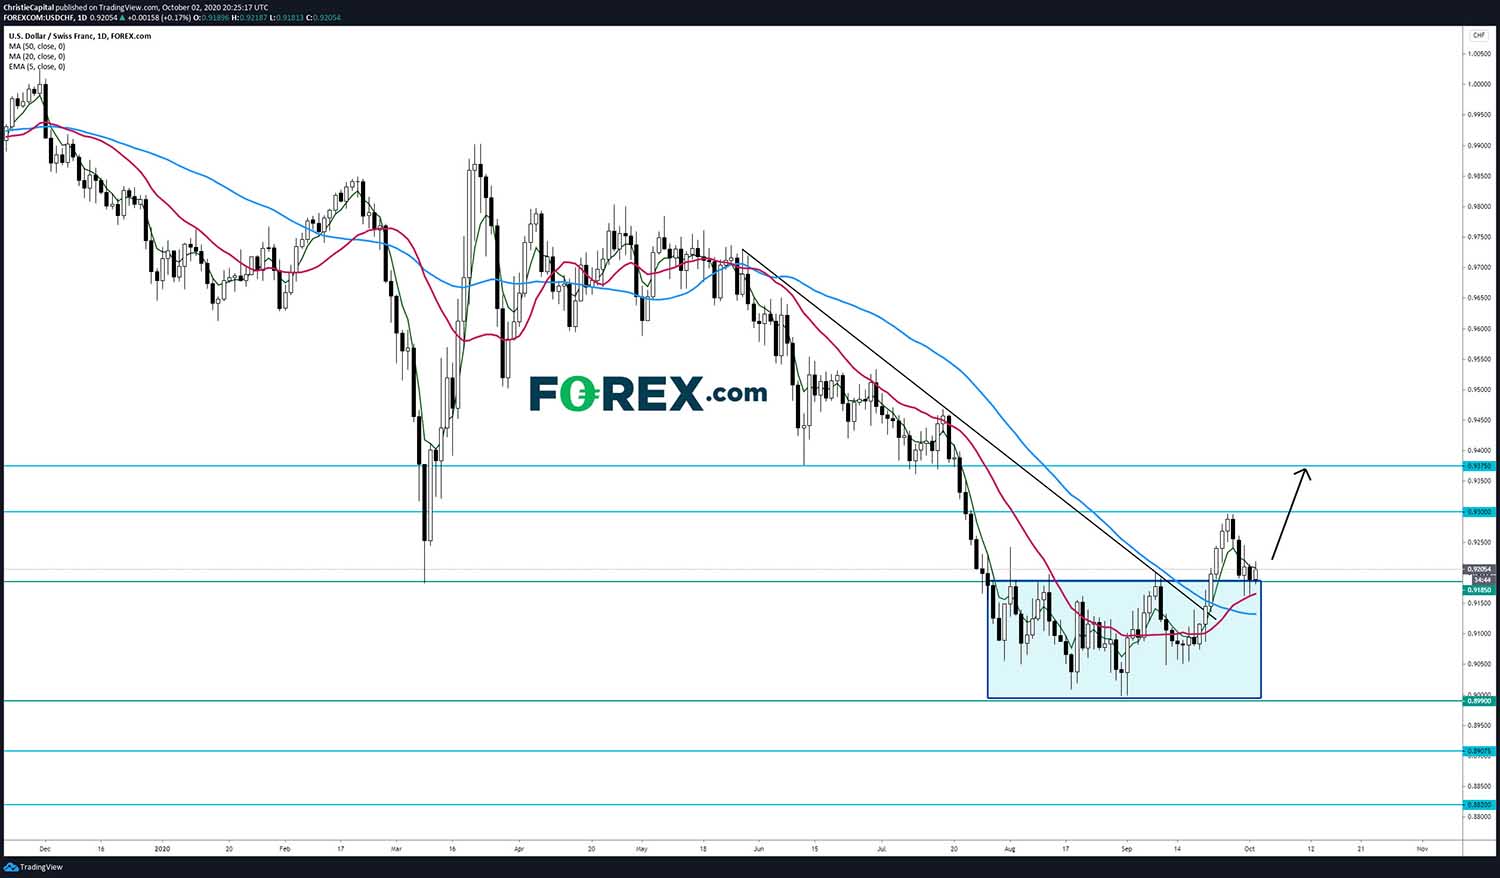
The worst performing pair of the week was the USD/CHF declining 82 pips WoW. The pair is struggling to maintain support at the 0.9185 breakout level. A break above 0.93 resistance would set a path towards a target of 0.9375 on the rebound.

Source: GAIN Capital, TradingView
Have a great weekend.
On Monday, no major economic data is expected to be released.
The Euro was bearish against most of its major pairs with the exception of the AUD. In Europe, September Consumer Price Index was released at +0.1%, as expected, vs -0.4% in August. The last phase of Brexit talks should end today. Boris Johnson and EU Commission President Von Der Leyen will hold talk on next steps tomorrow.
The Australian dollar was bearish against all of its major pairs.
Here is a review of key economic data over the past week:
On the jobs front, Change in Nonfarm Payrolls dropped to 661K on month in September (859K expected), from a revised 1,489K in August. The Unemployment Rate declined to 7.9% on month in September (8.2% expected), from 8.4% in August. Initial Jobless Claims fell to 837K for the week ending September 26th (850K expected), from a revised 873K in the week before. Continuing Claims dropped to 11,767K for the week ending September 19th (12,200K expected), from a revised 12,747K in the prior week. Finally, Automatic Data Processing's Employment Change rose to 749K on month in September (649K expected), from a revised 481K in August.
Regarding sentiment, The University of Michigan's Consumer Sentiment Index increased to 80.4 on month in the September final reading (79.0 expected), from 78.9 in the September preliminary reading. The Conference Board's Consumer Confidence Index spiked to 101.8 on month in September (90.0 expected), from a revised 86.3 in August.
Looking at consumers, Personal Income slipped 2.7% on month in August (-2.5% expected), compared to a revised +0.5% in July. Personal Spending rose 1.0% on month in August (+0.8% expected), compared to a revised +1.5% in July.
On the housing data front, The Mortgage Bankers Association's Mortgage Applications dropped 4.8% for the week ending September 25th, compared to +6.8% in the week before. Pending Home Sales surged 8.8% on month in August (+3.1% expected), compared to +5.9% in July.
Factory Orders rose 0.7% on month in August (+0.9% expected), compared to a revised +6.5% in July. Durable Goods Orders increased 0.5% on month in the August final reading (+0.4% expected), compared to +0.4% in the August preliminary reading. Markit's US Manufacturing Purchasing Managers' Index unexpectedly declined to 53.2 on month in the September final reading (53.5 expected), from 53.5 in the September preliminary reading. Construction Spending increased 1.4% on month in August (+0.7% expected), compared to a revised +0.7% in July. Wholesale Inventories unexpectedly rose 0.5% on month in the August preliminary reading (-0.1% expected), compared to a revised -0.1% in the July final reading.
U.S. GDP rose to -31.4% on quarter in the second quarter third reading (-31.7% expected), from -31.7% in the second quarter second reading.
The GBP/USD posted the largest weekly gain of 197 pips. Key resistance remains in play at the 1.2985 level. The bias remains bearish on a daily chart until 1.2985 is broken to the downside.
Source: GAIN Capital, TradingView
The worst performing pair of the week was the USD/CHF declining 82 pips WoW. The pair is struggling to maintain support at the 0.9185 breakout level. A break above 0.93 resistance would set a path towards a target of 0.9375 on the rebound.
Source: GAIN Capital, TradingView
Have a great weekend.
The US Dollar was bullish against most of its major pairs on Friday with the exception of the GBP and JPY.
On Monday, no major economic data is expected to be released.
The Euro was bearish against most of its major pairs with the exception of the AUD. In Europe, September Consumer Price Index was released at +0.1%, as expected, vs -0.4% in August. The last phase of Brexit talks should end today. Boris Johnson and EU Commission President Von Der Leyen will hold talk on next steps tomorrow.
The Australian dollar was bearish against all of its major pairs.
Here is a review of key economic data over the past week:
On the jobs front, Change in Nonfarm Payrolls dropped to 661K on month in September (859K expected), from a revised 1,489K in August. The Unemployment Rate declined to 7.9% on month in September (8.2% expected), from 8.4% in August. Initial Jobless Claims fell to 837K for the week ending September 26th (850K expected), from a revised 873K in the week before. Continuing Claims dropped to 11,767K for the week ending September 19th (12,200K expected), from a revised 12,747K in the prior week. Finally, Automatic Data Processing's Employment Change rose to 749K on month in September (649K expected), from a revised 481K in August.
Regarding sentiment, The University of Michigan's Consumer Sentiment Index increased to 80.4 on month in the September final reading (79.0 expected), from 78.9 in the September preliminary reading. The Conference Board's Consumer Confidence Index spiked to 101.8 on month in September (90.0 expected), from a revised 86.3 in August.
Looking at consumers, Personal Income slipped 2.7% on month in August (-2.5% expected), compared to a revised +0.5% in July. Personal Spending rose 1.0% on month in August (+0.8% expected), compared to a revised +1.5% in July.
On the housing data front, The Mortgage Bankers Association's Mortgage Applications dropped 4.8% for the week ending September 25th, compared to +6.8% in the week before. Pending Home Sales surged 8.8% on month in August (+3.1% expected), compared to +5.9% in July.
Factory Orders rose 0.7% on month in August (+0.9% expected), compared to a revised +6.5% in July. Durable Goods Orders increased 0.5% on month in the August final reading (+0.4% expected), compared to +0.4% in the August preliminary reading. Markit's US Manufacturing Purchasing Managers' Index unexpectedly declined to 53.2 on month in the September final reading (53.5 expected), from 53.5 in the September preliminary reading. Construction Spending increased 1.4% on month in August (+0.7% expected), compared to a revised +0.7% in July. Wholesale Inventories unexpectedly rose 0.5% on month in the August preliminary reading (-0.1% expected), compared to a revised -0.1% in the July final reading.
U.S. GDP rose to -31.4% on quarter in the second quarter third reading (-31.7% expected), from -31.7% in the second quarter second reading.
The GBP/USD posted the largest weekly gain of 197 pips. Key resistance remains in play at the 1.2985 level. The bias remains bearish on a daily chart until 1.2985 is broken to the downside.

Source: GAIN Capital, TradingView
The worst performing pair of the week was the USD/CHF declining 82 pips WoW. The pair is struggling to maintain support at the 0.9185 breakout level. A break above 0.93 resistance would set a path towards a target of 0.9375 on the rebound.
Source: GAIN Capital, TradingView
Have a great weekend.
On Monday, no major economic data is expected to be released.
The Euro was bearish against most of its major pairs with the exception of the AUD. In Europe, September Consumer Price Index was released at +0.1%, as expected, vs -0.4% in August. The last phase of Brexit talks should end today. Boris Johnson and EU Commission President Von Der Leyen will hold talk on next steps tomorrow.
The Australian dollar was bearish against all of its major pairs.
Here is a review of key economic data over the past week:
On the jobs front, Change in Nonfarm Payrolls dropped to 661K on month in September (859K expected), from a revised 1,489K in August. The Unemployment Rate declined to 7.9% on month in September (8.2% expected), from 8.4% in August. Initial Jobless Claims fell to 837K for the week ending September 26th (850K expected), from a revised 873K in the week before. Continuing Claims dropped to 11,767K for the week ending September 19th (12,200K expected), from a revised 12,747K in the prior week. Finally, Automatic Data Processing's Employment Change rose to 749K on month in September (649K expected), from a revised 481K in August.
Regarding sentiment, The University of Michigan's Consumer Sentiment Index increased to 80.4 on month in the September final reading (79.0 expected), from 78.9 in the September preliminary reading. The Conference Board's Consumer Confidence Index spiked to 101.8 on month in September (90.0 expected), from a revised 86.3 in August.
Looking at consumers, Personal Income slipped 2.7% on month in August (-2.5% expected), compared to a revised +0.5% in July. Personal Spending rose 1.0% on month in August (+0.8% expected), compared to a revised +1.5% in July.
On the housing data front, The Mortgage Bankers Association's Mortgage Applications dropped 4.8% for the week ending September 25th, compared to +6.8% in the week before. Pending Home Sales surged 8.8% on month in August (+3.1% expected), compared to +5.9% in July.
Factory Orders rose 0.7% on month in August (+0.9% expected), compared to a revised +6.5% in July. Durable Goods Orders increased 0.5% on month in the August final reading (+0.4% expected), compared to +0.4% in the August preliminary reading. Markit's US Manufacturing Purchasing Managers' Index unexpectedly declined to 53.2 on month in the September final reading (53.5 expected), from 53.5 in the September preliminary reading. Construction Spending increased 1.4% on month in August (+0.7% expected), compared to a revised +0.7% in July. Wholesale Inventories unexpectedly rose 0.5% on month in the August preliminary reading (-0.1% expected), compared to a revised -0.1% in the July final reading.
U.S. GDP rose to -31.4% on quarter in the second quarter third reading (-31.7% expected), from -31.7% in the second quarter second reading.
The GBP/USD posted the largest weekly gain of 197 pips. Key resistance remains in play at the 1.2985 level. The bias remains bearish on a daily chart until 1.2985 is broken to the downside.
Source: GAIN Capital, TradingView
The worst performing pair of the week was the USD/CHF declining 82 pips WoW. The pair is struggling to maintain support at the 0.9185 breakout level. A break above 0.93 resistance would set a path towards a target of 0.9375 on the rebound.
Source: GAIN Capital, TradingView
Have a great weekend.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
AUD/USD Analysis: What's Next for the Australian Dollar After the RBA Decision?
Recent trading sessions have reflected a more neutral tone around the Australian dollar. This can be seen in AUD/USD price action, which has posted moves of roughly 0.2% over the last two sessions without establishing a clear direction. Much of this lack of momentum is linked to expectations surrounding the next policy moves from both the Reserve Bank of Australia (RBA) and the Federal Reserve.

USD into a Massive Week as Yields Fly and Gold Breaks
It’s a huge week with PCE and NFP, but it’s what’s happening off of the calendar that demands attention with US yields flying to fresh multi-decade highs.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.