



Core PCE not as bad as feared. But how much does it matter?
It probably won’t matter in isolation, as the Fed is now looking at a number of inflation data points to help determine the next direction for inflation in the US.
Share this:

The US Core PCE Price Index has traditionally been known as the Fed’s favorite measure of inflation. Today, the US released the print for May with a reading of 4.7% YoY vs an expectation of 4.8% YoY and an April reading of 4.9% YoY. This is the third month in a row of declines for the reading and the lowest since November 2021. In addition, the headline PCE Price Index was 6.3% YoY vs a previous reading of 6.3% YoY.
So, is the Core PCE Price Index giving us a sign that we have had peak inflation? Fed Chairman Powell said in the press conference following the last FOMC meeting that the main reason for hiking interest rates 75bps, rather than the expected 50bps, was because of the 8.6% YoY CPI reading, as well as the higher than expected Michigan Inflation Expectations prints. This leads us to believe that although the Core PCE is still in the mix as one of the measures the Fed will use to determine inflation levels, it may not be the holy grail of inflation readings as it was in the past.
The initial reaction for the US Dollar Index was to pullback on the data release. Within the first 15 minutes after, the DXY pulled back from 105.50 down to 105.30.

Source: Tradingview, Stone X
However, over the last 2 ½ days, the DXY has been on a move higher as it tries to test the highs from June 15th at 105.79, its highest level since December 2002. The high of the move today as of the time of this writing is 105.54. Resistance above is at the 127.2% Fibonacci extension from the highs of May 13th to the lows of May 30th near 106.01. Above there, price can move to a confluence of resistance at the 161.8% Fibonacci extension from the same timeframe and the highs from December 2002 near 107.30. Support below is at the low of June 16th at 103.42, then horizontal support at 102.78.

Source: Tradingview, Stone X
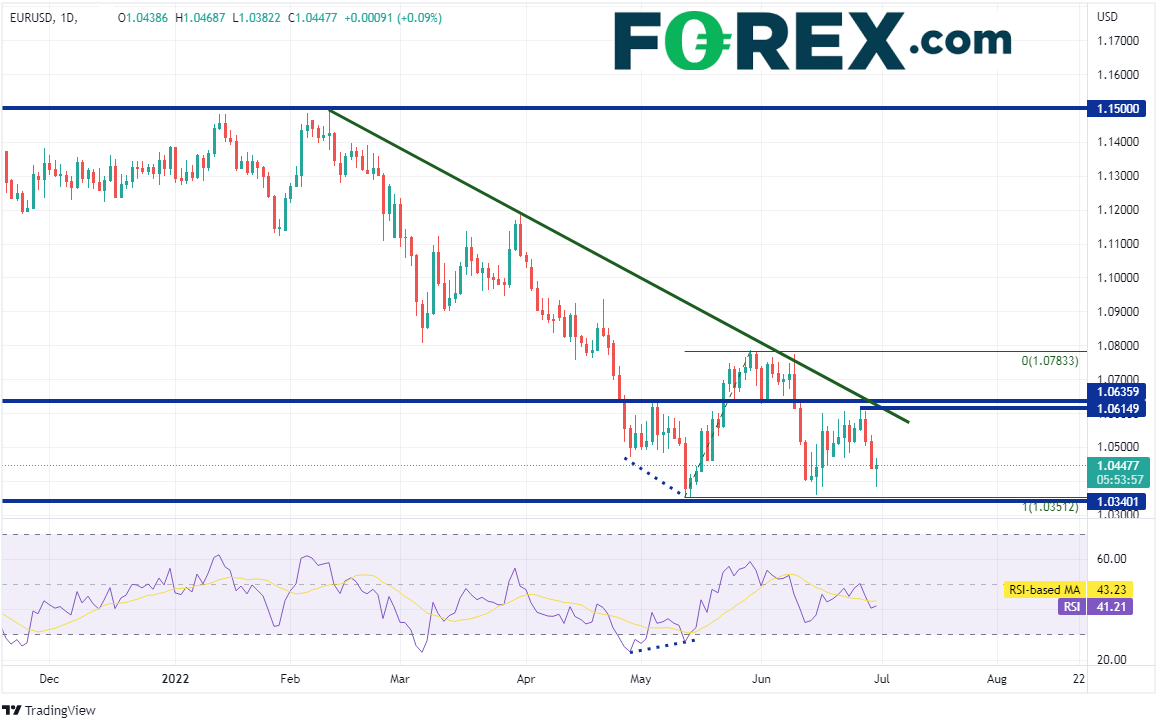
The Euro makes of 57% of the US Dollar Index. Therefore, it’s not a surprise that when the DXY moves in one direction, EUR/USD moves in the opposite direction. EUR/USD has been moving lower over the last 3 days as the US Dollar Index was moving higher. The pair is trying to test the lows from May 13th at 1.0349, just 9 pips from its lowest level since December 2002. If the pair does continue lower, support is at the 127.2% and 161.8% Fibonacci extensions from the lows of May 13th to the highs of May 30th at 1.0234 and 1.0084, respectively. However, if EUR/USD moves higher, first resistance is at the highs from June 27th and the downward sloping trendline (green) near 1.0615. Just above there is long-term horizontal resistance at 1.0536, then the highs from May 30th at 1.0784.
Source: Tradingview, Stone X
US Core PCE was released today and it was softer than expected. Will it matter to the Fed? It probably won’t matter in isolation, as the Fed is now looking at a number of inflation data points to help determine the next direction for inflation in the US.
The US Core PCE Price Index has traditionally been known as the Fed’s favorite measure of inflation. Today, the US released the print for May with a reading of 4.7% YoY vs an expectation of 4.8% YoY and an April reading of 4.9% YoY. This is the third month in a row of declines for the reading and the lowest since November 2021. In addition, the headline PCE Price Index was 6.3% YoY vs a previous reading of 6.3% YoY.
So, is the Core PCE Price Index giving us a sign that we have had peak inflation? Fed Chairman Powell said in the press conference following the last FOMC meeting that the main reason for hiking interest rates 75bps, rather than the expected 50bps, was because of the 8.6% YoY CPI reading, as well as the higher than expected Michigan Inflation Expectations prints. This leads us to believe that although the Core PCE is still in the mix as one of the measures the Fed will use to determine inflation levels, it may not be the holy grail of inflation readings as it was in the past.
Everything you need to know about the Federal Reserve
The initial reaction for the US Dollar Index was to pullback on the data release. Within the first 15 minutes after, the DXY pulled back from 105.50 down to 105.30.

Source: Tradingview, Stone X
However, over the last 2 ½ days, the DXY has been on a move higher as it tries to test the highs from June 15th at 105.79, its highest level since December 2002. The high of the move today as of the time of this writing is 105.54. Resistance above is at the 127.2% Fibonacci extension from the highs of May 13th to the lows of May 30th near 106.01. Above there, price can move to a confluence of resistance at the 161.8% Fibonacci extension from the same timeframe and the highs from December 2002 near 107.30. Support below is at the low of June 16th at 103.42, then horizontal support at 102.78.

Source: Tradingview, Stone X
Trade the DXY now: Login or Open a new account!
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
The Euro makes of 57% of the US Dollar Index. Therefore, it’s not a surprise that when the DXY moves in one direction, EUR/USD moves in the opposite direction. EUR/USD has been moving lower over the last 3 days as the US Dollar Index was moving higher. The pair is trying to test the lows from May 13th at 1.0349, just 9 pips from its lowest level since December 2002. If the pair does continue lower, support is at the 127.2% and 161.8% Fibonacci extensions from the lows of May 13th to the highs of May 30th at 1.0234 and 1.0084, respectively. However, if EUR/USD moves higher, first resistance is at the highs from June 27th and the downward sloping trendline (green) near 1.0615. Just above there is long-term horizontal resistance at 1.0536, then the highs from May 30th at 1.0784.

Source: Tradingview, Stone X
Trade EUR/USD now: Login or Open a new account!
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
US Core PCE was released today and it was softer than expected. Will it matter to the Fed? It probably won’t matter in isolation, as the Fed is now looking at a number of inflation data points to help determine the next direction for inflation in the US.
Learn more about forex trading opportunities.
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.