


DAX Recovery Accelerates as Industrial Stocks Lead Gains
The DAX briefly reclaimed the 26,000 level as investors used post-election weakness as an opportunity to rotate into industrial, healthcare and energy-transition leaders. Strong gains in Bayer, Siemens and Siemens Energy helped offset weakness in consumer and AI-related growth stocks. With bond yields easing and the dollar weakening after the US midterm elections, investors are increasingly focusing on earnings quality, visible demand and infrastructure-related growth themes.
Share this:
DAX Back at 26,000: Buyers Step In on Weakness
The DAX briefly reclaimed the psychologically important 26,000-point level on Wednesday morning. After opening weak at 25,850.40 and falling to an intraday low of 25,536.50, the index reversed sharply higher and reached an intraday high of 26,013.50. It was last trading at 25,972 points, up 153.50 points (+0.59%). +
This appears to be more than just a technical rebound. Buyers actively used the weakness following the U.S. midterm elections to add exposure rather than extend losses. At the same time, the Euro Stoxx 50 rose 0.87% to 6,194.50, signalling improving risk appetite across European markets.
What's Driving the Market Today?
The main focus is the market's reaction to the U.S. midterm elections. The Democrats have significantly weakened President Donald Trump and the Republicans, with market reports indicating they have gained control of both the House of Representatives and the Senate. Surprise victories were reported in South Carolina, Texas and Ohio.
For Europe, however, this is not necessarily a negative outcome. Lower U.S. Treasury yields and a weaker dollar can make European equities relatively more attractive. The euro rose around 0.5% to $1.1249, while the U.S. Dollar Index fell 0.3% to 101.4.
DAX: Winners and Losers
A clear market rotation is visible. Investors are reducing exposure to highly valued AI and consumer stocks and reallocating capital into companies with stronger earnings visibility, industrial demand and exposure to Europe's energy transition.
|
Stock |
Performance |
Commentary |
|
Bayer |
+3.64% |
Strong gain after raising its 2026 earnings outlook |
|
Siemens Energy |
+2.27% |
Energy infrastructure remains a relative-strength leader |
|
Siemens |
+1.49% |
Industrial demand continues to support quality cyclicals |
|
Infineon |
+0.77% |
Semiconductor stocks stabilising after the AI correction |
|
SAP |
-1.83% |
High DAX weighting makes it vulnerable to AI regulation concerns |
|
Volkswagen Preferred |
-2.25% |
Auto stocks remain under pressure |
|
adidas |
-2.75% |
Consumer stocks continue to be reduced |
|
MTU Aero Engines |
-3.12% |
Aerospace growth stocks under selling pressure |
|
Fresenius Medical Care |
-3.60% |
Healthcare remains weak despite defensive characteristics |
|
Zalando |
-6.30% |
Largest DAX loser as consumer weakness is punished |
Bayer remains the key single-stock story. The shares rose 3.64% to €51.84 and generated the highest trading volume within the DAX, suggesting institutional demand rather than merely a short-term technical rebound.
Siemens and Siemens Energy further reinforce the rotation theme. Investors are not broadly increasing risk exposure, but are selectively targeting companies with visible order books, investment cycles and exposure to grid expansion, automation and the energy transition.
Technical Picture: 26,000 Remains the Key Pivot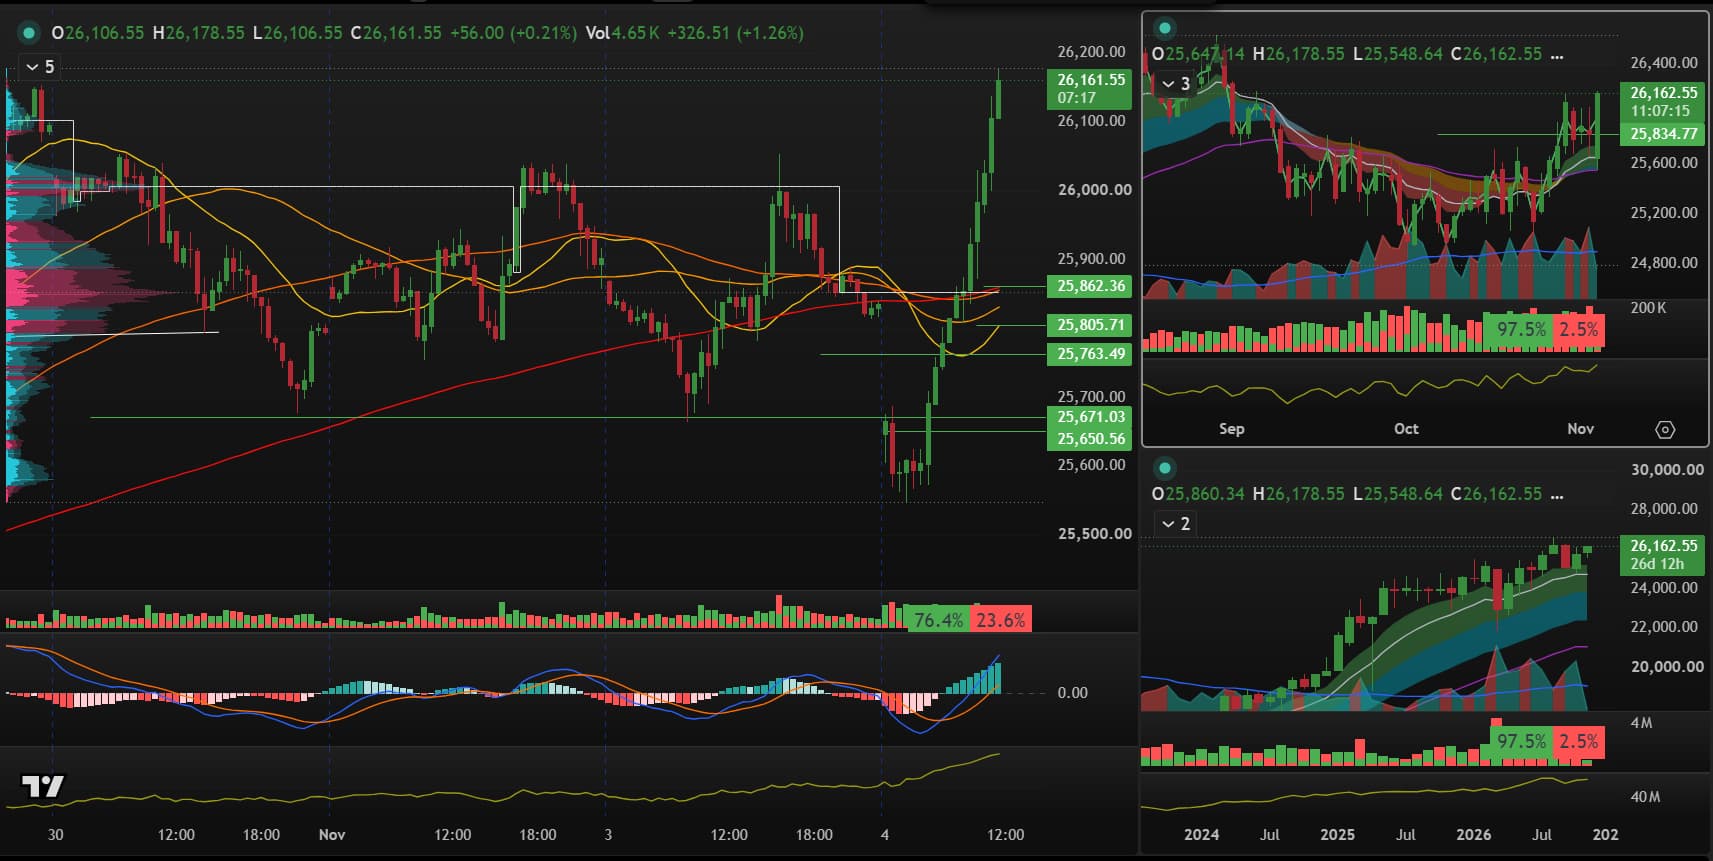
From a technical perspective, 26,000 points remains the critical level for the DAX. The index traded above it intraday before consolidating slightly below it, which is normal after a sharp rebound from the session low.
- Key support: 25,850 to 25,900, the opening area and starting point of today's recovery.
- Next support: 25,800. As long as the DAX remains above this level, the short-term recovery scenario remains intact.
- Key resistance: 26,000. A sustained close above this level would be a bullish confirmation signal.
- Next upside target: 26,030, today's high and the high from the previous two sessions.
- Further resistance: 26,150, last week's high.
- Major target: 26,618.74, the DAX all-time high.
Observations
The current environment is less about buying or selling everything and more about selective positioning.
- Favour: Siemens, Siemens Energy, Bayer and selected semiconductor names. These companies benefit from visible demand, earnings catalysts and Europe's investment cycle.
- Remain cautious with: SAP, Zalando, auto stocks and other highly valued growth names while the AI regulation debate after the U.S. election continues.
- Monitor closely: U.S. yields, the dollar and the euro. Further declines in yields would likely support European equities.
Conclusion
The DAX has tested and intraday reclaimed the 26,000-point level. The rebound is broad-based, led by industrial quality stocks, and suggests investors are treating the U.S. election reaction as a rotation opportunity rather than a trigger for broad risk reduction.
The strategic message is clear: buy quality, reduce AI concentration risk, and use 26,000 as the key confirmation level. As long as the DAX remains above 25,800, the recovery remains in control. A sustained close above 26,000 would reopen the path toward the all-time high at 26,618.74.
By Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
dax-record-high-banks-cyclicals-election-relief-rally-european-stocks
The DAX has surged to fresh record highs as investors continue to rotate into banks, industrials and cyclical stocks following the US midterm elections. Falling bond yields, lower oil prices and improving sentiment have supported risk appetite across Europe, helping the index move decisively above 26,000. The focus now shifts from political relief to whether earnings and macroeconomic data can justify the rally's next leg higher.
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?

Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.