



Global Markets Steady as Fed Meeting Trump Putin Talks and Nvidia Conference Dominate Headlines
DAX holds near record highs as Germany’s €500B borrowing plan boosts sentiment. Nvidia’s GTC event could shake up AI & semiconductor stocks, while gold hits $3,017/oz amid inflation fears. Trump-Putin talks may impact sanctions & energy markets, while Fed’s rate decision tomorrow will set the tone for US economic projections. Oil climbs on Middle East tensions.
Share this:
Global Markets Steady as Fed Meeting, Trump-Putin Talks, and Nvidia Conference Dominate Headlines
- US stock futures flat as investors await Fed rate decision & economic projections.
- Nvidia’s GTC conference in focus, with CEO Jensen Huang set to unveil the Vera Rubin AI chip.
- Trump-Putin phone call on Ukraine ceasefire could impact geopolitical risk sentiment.
- Oil prices rise following Israeli airstrikes in Gaza and Red Sea tensions.
- Asian markets rally, led by:
- Hong Kong’s Hang Seng (+2%), hitting a 3-year high on China stimulus optimism.
- Japan’s Nikkei (+1.5%), rebounding from recent losses.
- Gold hits record $3,017/oz as US retail sales miss expectations and inflation concerns persist.
US Focus: Fed Meeting, Retail Sales & Tariff Uncertainty
Fed Policy Decision Tomorrow
Rates expected to remain at 4.5%, with focus on economic projections.
- Fed’s stance on inflation & growth will guide market expectations for future rate cuts.
- US Treasury yields rebounded, reversing earlier losses amid concerns over inflation persistence.
US Retail Sales Weaker Than Expected
- February retail sales (MoM): +0.2% (Expected: +0.6%).
- Control group retail sales (ex-food, autos, fuel): +1.0% (Expected: +0.3%).
- Mixed data suggests underlying consumer spending remains resilient, but growth is slowing.
Trump-Putin Talks on Ukraine Peace Deal
- Trump hinted at discussions on land, power plants & asset division to broker a ceasefire.
- Markets are watching for potential sanctions relief on Russia, which could impact energy & commodity markets.
Nvidia GTC Conference This week: AI & Quantum Innovations Awaited
- CEO Jensen Huang to unveil new AI & quantum computing technologies, including:
- Vera Rubin AI chip.
- Advancements in Sovereign AI & AI agents.
- Automotive AI & robotics breakthroughs.
- Stock is down ~20% from its record high, as investors question AI trade sustainability.
- Impacted stocks: Broadcom, Marvell, Qualcomm, Supermicro.
European Markets Resilient Amid German Borrowing Plan
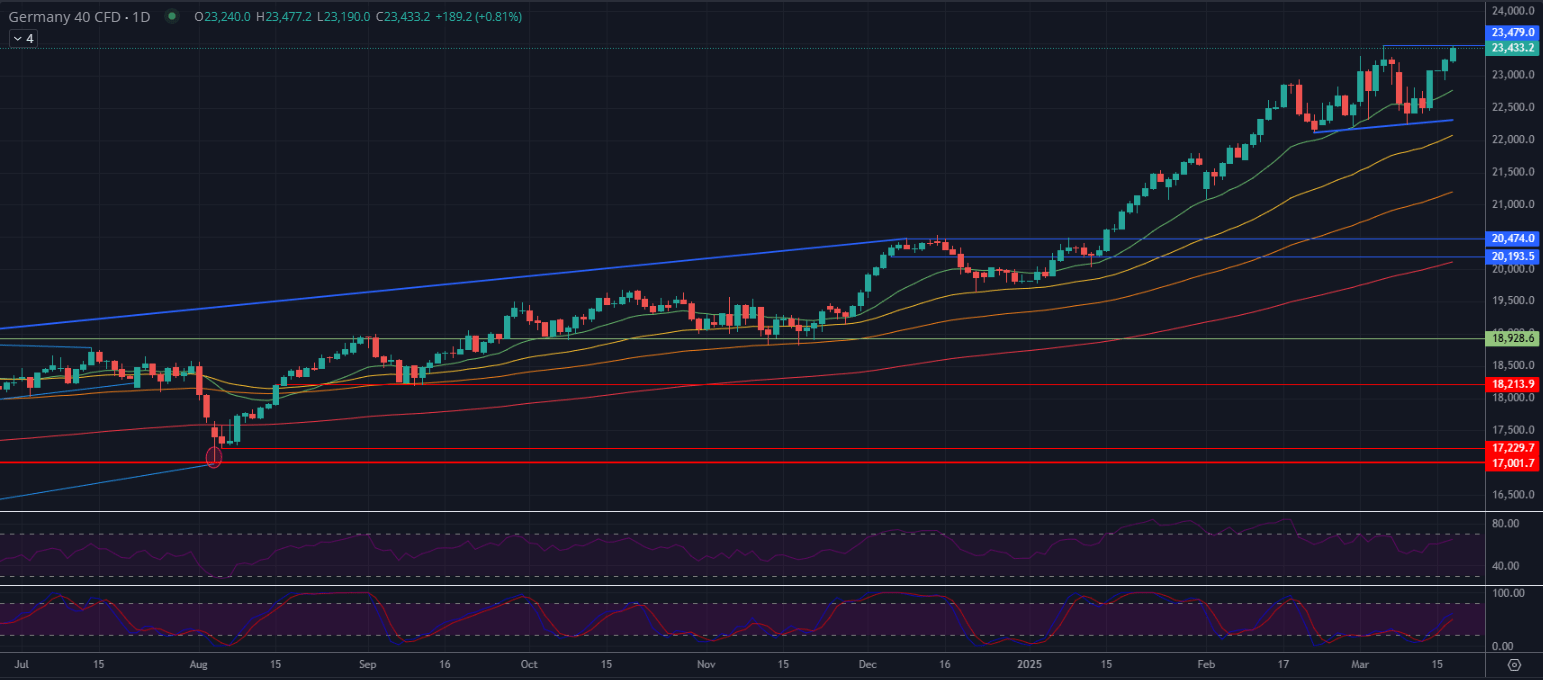
- EuroStoxx 50 futures +0.35%, DAX +0.43% as Germany’s €500 billion fiscal plan progresses.
Diagram: DAX 1 Day, near all time highs.
UK Economy Slows, BoE Rate Cut Unlikely This Week
- January GDP shrank -0.1%, driven by:
- Industrial production slump (-0.9%).
- Weak manufacturing output.
- BoE expected to keep rates at 4.5%, despite:
- Inflation still above 2% target.
- Markets only pricing in two rate cuts by early 2026.
- Planned UK defense spending increase (2.3% → 2.5% of GDP by 2027) could provide some economic support.
Energy & Commodities: Oil & Gold Surge on Geopolitical Risks
- Brent crude +1.3% to $71.97/barrel | WTI +1.3% to $68.27/barrel.
- Israeli airstrikes in Gaza reignite Middle East tensions, fueling supply concerns.
- Gold hit record $3,017/oz, benefiting from:
- US dollar weakness.
- Uncertainty over Fed policy & inflation trends.
Market Outlook
- US & European equities steady, with AI & geopolitical events in focus.
- Nvidia’s conference could shake up tech stocks, while Fed signals will drive rates & yields.
- Germany’s fiscal plan could support Eurozone growth, boosting DAX & European markets.
- Gold remains strong amid uncertainty, while oil traders watch Middle East & Ukraine tensions.
- Risk sentiment hinges on Fed, Trump-Putin talks, and Nvidia’s AI announcements.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, Gold Forecast: Two trades to watch
EUR/USD rises on USD weakness and as Eurozone inflation hits 4%. Gold – U.S. midterms lift precious metal above $4,000.


dax-26000-bayer-siemens-energy-sektorrotation-us-zwischenwahlen
The DAX briefly reclaimed the 26,000 level as investors used post-election weakness as an opportunity to rotate into industrial, healthcare and energy-transition leaders. Strong gains in Bayer, Siemens and Siemens Energy helped offset weakness in consumer and AI-related growth stocks. With bond yields easing and the dollar weakening after the US midterm elections, investors are increasingly focusing on earnings quality, visible demand and infrastructure-related growth themes.

Gold Analysis: Resilient U.S. Labor Market Continues to Pressure XAU/USD
Recent trading sessions have not been particularly favorable for gold in the short term. XAU/USD has fallen nearly 2.5% over the last three sessions, reflecting that selling pressure is once again gaining relevance and that the metal continues to struggle to regain momentum.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.