


DAX Hits Record High as Banks and Cyclicals Lead the Rally
The DAX has surged to fresh record highs as investors continue to rotate into banks, industrials and cyclical stocks following the US midterm elections. Falling bond yields, lower oil prices and improving sentiment have supported risk appetite across Europe, helping the index move decisively above 26,000. The focus now shifts from political relief to whether earnings and macroeconomic data can justify the rally's next leg higher.
Share this:
DAX Breaks to a New Record High
The DAX is trading at 26,569.30 on Thursday, just 0.24% or 65.20 points below the previous day's close. After a strong 3.18% rally on Wednesday, Germany's benchmark index has decisively moved beyond the 26,000 level and extended its all-time high today to 26,672.
European equities are also advancing broadly. The Stoxx Europe 600 is up 0.53% to 660.91, the CAC 40 gains 0.62% to 8,228.83, and the FTSE 100 rises 0.80% to 10,915.52.
Winners and Losers
The market rotation remains firmly in place. Banks, renewable-energy companies and cyclical consumer stocks are benefiting from improved risk sentiment, while defence stocks and parts of the semiconductor sector remain under pressure.
• Deutsche Bank rose 5.88% yesterday and was one of the main drivers of the banking rally.
• BMW gained 5.50%, while other German automakers such as Mercedes-Benz and Porsche also posted strong advances.
• Fresenius, Fresenius Medical Care, Commerzbank, Allianz and Bayer each gained between 4% and 6%.
• SAP, Volkswagen, Deutsche Telekom, Siemens Healthineers, BASF and Siemens advanced between 2% and 4%.
• Siemens Energy fell more than 7%, while Hochtief declined 4.7% and Infineon lost 3.3%.
• Rheinmetall is under particularly heavy pressure today, dropping more than 16% after lowering its 2026 outlook.
The weakness in Rheinmetall suggests investors are taking the potential implications of a Democratic majority in the U.S. Congress for defence spending seriously. However, the long-term drivers of the European defence sector, including higher military budgets, rearmament needs and geopolitical uncertainty, remain intact.
U.S. Elections: Relief Instead of Uncertainty
The Democrats' clear majority in both chambers of Congress has transformed initial market nervousness into a relief rally.
Investors are now pricing in less legislative chaos, a lower risk of political gridlock and the possibility of progress toward de-escalation in the Middle East.
The S&P 500 closed 1.6% higher yesterday, while European stocks climbed to a two-month high. The Stoxx Europe 600 rose 1.86% and now trades only around half a percentage point below its record high.
Banks have been among the strongest performers. Investors expect less pressure from Washington on European financial institutions and are reassessing sector valuations.
Renewable-energy stocks are also benefiting from expectations of a more supportive climate-policy backdrop:
• Ørsted gained almost 5%
• Vestas rose nearly 4%
• Nordex advanced around 6%
Technology and semiconductor stocks remain the main area of compromise. Concerns over a potentially slower expansion of AI data centres in the United States persist, leaving chipmakers and energy-intensive infrastructure stocks under pressure.
Technical Picture: DAX at Record Highs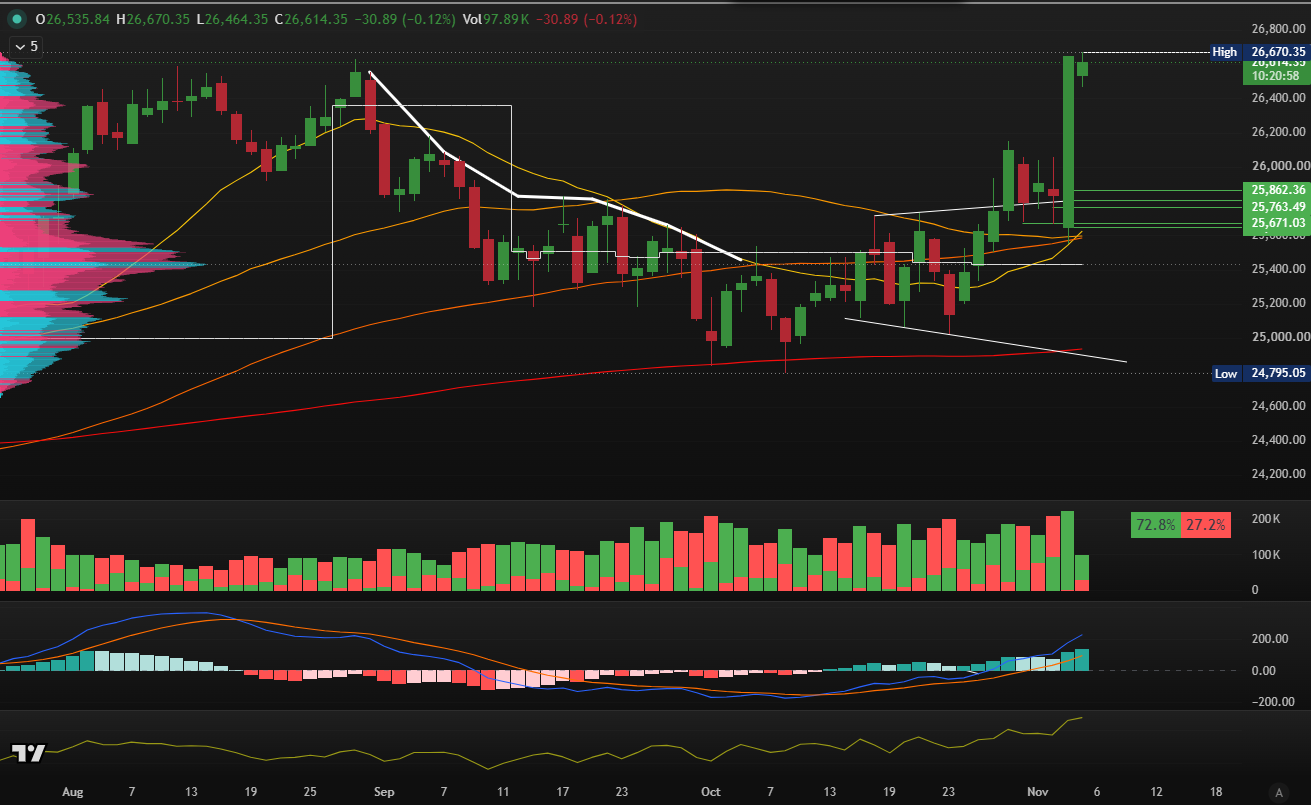
Technically, the DAX remains in a very constructive position.
The index has not only reclaimed the 26,000 level but has also established a new all-time high at 26,670.
• Primary support: 26,448, today's intraday low
• Secondary support: 26,437, Wednesday's closing price
• Psychological support: 26,500
• Immediate resistance: 26,672, today's high and the all-time high
As long as the DAX remains above 26,448, the recovery keeps the upper hand.
A breakout above 26,672 would confirm the current momentum and open the door for another advance into uncharted territory.
Outlook for the Trading Session
Market focus is now shifting from the election reaction to whether the rally can be supported by fundamentals.
Falling oil prices, lower bond yields and strong corporate earnings have improved sentiment. The next challenge is whether upcoming earnings releases and macroeconomic data can validate those expectations.
For the DAX, today represents a test of breakout strength.
As long as the index stays above 26,500, the bullish setup remains intact.
A move back below 26,448 would likely trigger a short-term consolidation phase, although it would not automatically undermine the broader medium-term uptrend.
Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
dax-record-high-banks-cyclicals-election-relief-rally-european-stocks
The DAX has surged to fresh record highs as investors continue to rotate into banks, industrials and cyclical stocks following the US midterm elections. Falling bond yields, lower oil prices and improving sentiment have supported risk appetite across Europe, helping the index move decisively above 26,000. The focus now shifts from political relief to whether earnings and macroeconomic data can justify the rally's next leg higher.
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?

Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.