



DAX Stalls at 200 EMA, Markets Eye Intel Earnings
DAX trades at 21,748, stalling near 200 EMA resistance, as momentum fades despite April’s rebound. SAP jumps 10% on strong Q1 profit, while Intel cuts 20% of staff ahead of earnings. Crude oil drops 5% as OPEC+ mulls output hikes. Today’s focus: U.S. durable goods, jobless claims, home sales, and IMF/World Bank meetings.
Share this:
Trump on Powell: No Firing Planned
President Trump told reporters he has “no intention of firing” Fed Chair Jerome Powell, despite recently stating online that “Powell’s termination cannot come fast enough.” Trump clarified he never seriously intended to remove Powell, whose term runs through May 2026, and simply wants him to be “more active” in lowering interest rates. His comments helped ease recent investor concerns.
Walmart CEO Issues Tariff Warning
Walmart’s CEO warned that Trump’s tariffs could soon lead to empty shelves, with the effects potentially visible within two weeks. The retailer stressed that these disruptions could hit consumers hard, suggesting the trade fight is entering a stage where Trump “can’t ultimately win.”
Germany
Business confidence in Germany improved in the first quarter of this year following a historic debt deal to increase defence spending by easing strict rules and establishing a substantial infrastructure fund. The IFO index rose from 84.7 in December to 86.7 in March, marking its highest level since last July. Sentiment is expected to remain lifted as seen in the forecast of 85.1 for the month of April, which could keep the Euro elevated.
Software giant SAP’s shares surge 10% after first-quarter profit beat: SAP on Wednesday posted a 58% year-on-year jump in first-quarter operating profit in constant currency, also confirming its outlook for full-year cloud revenues. CNBC reports.
DAX Technical Analysis 4 hour
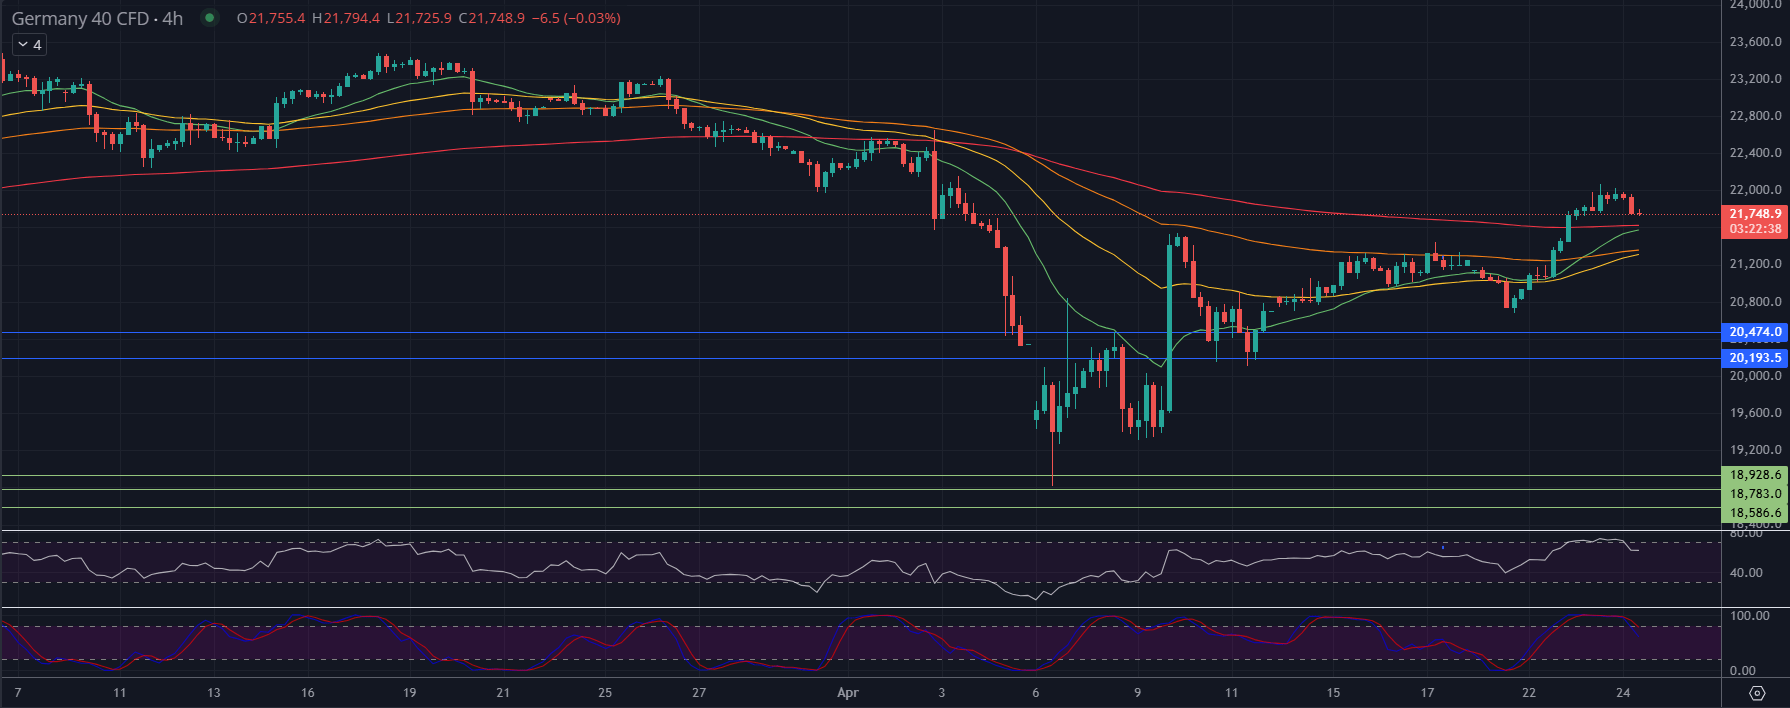
Germany 40 (DAX) CFD – 4H chart shows that the index is stalling just above the 200 EMA, trading at 21,748.9 (-0.03%). After a strong recovery from April lows, the momentum is beginning to slow at a critical resistance zone, suggesting potential consolidation or a pullback.
🔍 Technical Overview:
- Trend structure:
- Price is above all EMAs (20, 50, 100, 200), which are now sloping upward — a bullish signal.
- Momentum fading:
- Recent candles show upper wicks, indicating selling pressure near the highs.
- RSI is rolling off just below overbought territory (~60–65 range).
- Stochastic RSI has formed a bearish crossover in the overbought zone, suggesting a short-term cooldown may be underway.
📌 Key Levels:
Resistance:
- 21,800–22,000: Resistance cluster including 200 EMA + prior breakdown zone from early April
- 22,300–22,500: If broken, this is the next major target for bulls
Support:
- 21,300–21,200: Area of short-term EMA support and previous consolidation
- 20,474 / 20,193.5: Key pivot zones from the March breakdown and April breakout
- 18,928–18,586: Long-term structure low
⚠️ Outlook:
The DAX is at a key inflection point. While the structure remains bullish, the 200 EMA is acting as a solid resistance, and momentum is showing signs of fatigue. A break and close above 21,800–22,000 would likely confirm continuation. Conversely, a rejection here could trigger a pullback toward 21,300–21,000.
📈 Bias: Neutral-to-bullish — watching for confirmation of breakout vs. signs of exhaustion.
Corporate Earnings
Intel is slated to report quarterly earnings after markets close on Thursday in its first report since CEO Lip-Bu Tan took the helm at the beleaguered chipmaker. Some investors expect a big move in the shares after it does. Yahoo Finance reports. Expected move by 25/04/2025 options expiration is 7.9%. Just 1 day before Earnings the CEO released a statement that INTEL will cut up to 20% of its workforce. Could this push up earnings of the beat down Chipmaker and help them work more efficiently? Revenue falling. EPS near zero. Hit by poor leadership and didn’t profit from the data centre AI hype train like competitors did. Missed 2 of last 8 quarters. CEO changes not showing results yet.
Alphabet - earnings Expected move of 8.94% by 25/04/2025 expiration date. EPS forecast $2.02 on $89.3B. Beat expectations in last 8 quarters.
Commodities
Crude oil prices fell sharply on Wednesday following reports that OPEC+ may propose accelerating production increases in June. The move, aimed at easing global supply constraints, comes amid ongoing tensions within the group over quota compliance.
Reuters reported that several OPEC+ members could push for back-to-back output hikes, raising the likelihood of increased global supply. This news hit prices hard.
Adding pressure, U.S. crude inventories unexpectedly rose by 0.25 million barrels, marking the fourth consecutive weekly increase—pointing to weaker domestic demand.
WTI crude dropped over 5% intraday before stabilizing near $62.30 per barrel.
Also Today
12:00 World IMF/World Bank Spring Meetings: Ongoing discussions may impact global economic policies and investor sentiment.
14:30 USD Durable Goods Orders (MoM) (Mar) expected 2.1%, last 0.9%. Indicating sustained manufacturing activity.
14:30 USD Initial Jobless Claims expected 222K, last 215K, suggesting a stable labor market.
16:00 USD Existing Home Sales (Mar) expected 4.14M, last 4.26M
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

dax-record-high-banks-cyclicals-election-relief-rally-european-stocks
The DAX has surged to fresh record highs as investors continue to rotate into banks, industrials and cyclical stocks following the US midterm elections. Falling bond yields, lower oil prices and improving sentiment have supported risk appetite across Europe, helping the index move decisively above 26,000. The focus now shifts from political relief to whether earnings and macroeconomic data can justify the rally's next leg higher.
dax-26000-bayer-siemens-energy-sektorrotation-us-zwischenwahlen
The DAX briefly reclaimed the 26,000 level as investors used post-election weakness as an opportunity to rotate into industrial, healthcare and energy-transition leaders. Strong gains in Bayer, Siemens and Siemens Energy helped offset weakness in consumer and AI-related growth stocks. With bond yields easing and the dollar weakening after the US midterm elections, investors are increasingly focusing on earnings quality, visible demand and infrastructure-related growth themes.
DAX Tests 26,000 as Markets Await AMD and US Election Results
The DAX remains close to 26,000 points after extending its recovery, but the market's attention is shifting away from geopolitics and back toward earnings, economic data and US politics. Reports from Bayer, Lufthansa and Fresenius Medical Care highlight a market increasingly rewarding profit growth while punishing weak guidance. With US midterm elections, JOLTS job openings and AMD earnings on today's agenda, the next move in equities may depend less on technicals and more on whether earnings and economic data justify current valuations.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.