



Marktbrief: DAX Steadies as Central Banks and Oil Drive Risk Mood
Global markets remain headline‑driven as major central bank decisions from the Fed, BoC and BoJ coincide with elevated oil prices and persistent Iran conflict risks. A modest pullback in crude has supported a short‑term risk rebound, led by tech, but inflation concerns remain unresolved. The DAX is attempting to stabilize near key long‑term support, with sentiment still highly sensitive to energy and policy signals.
Share this:
1. Core Market Theme: Central Banks + Oil Drive Risk Sentiment
- Three major central bank decisions today (Fed, Bank of Canada, Bank of Japan) dominate markets, against a backdrop of elevated oil prices and risk about rising inflation risk.
- Oil has pulled back >$2, potentially supporting a short‑term risk rebound, but prices remain far higher than a month ago, keeping inflation concerns alive.
- Markets are trading headline‑to‑headline, with geopolitics and tweets still the primary swing factor.
2. Central Banks Today (Key Focus)
Bank of Canada (14:45 CET)
- Rates expected on hold at 2.25%.
- Watch guidance on:
- Spillover from global energy prices
- Domestic growth momentum vs inflation risks
Federal Reserve (19:00 CET)
- Rates expected unchanged (3.75%).
- Focus on:
- Impact of energy‑driven inflation
- Balance between sticky prices and slowing growth
- Updated projections and Powell’s tone on the rate path
Bank of Japan 19th March (4:00 CET)
- No policy change expected.
- Markets attentive to:
- FX sensitivity (JPY weakness)
- Any shift in language on inflation durability
3. Equity Markets: Risk‑On Relief, Led by Tech
Asia
- Japan equities rebounded sharply:
- Nikkei +2.9%, Topix +2.5%
- Tech and AI led (Advantest +6.7%, SoftBank +5.8%)
- Oil pullback and easing yield pressure supported sentiment.
US
- US stocks posted modest gains:
- S&P 500 +0.25%, Nasdaq +0.51%
- Energy headlines muted overnight, allowing positioning ahead of the Fed.
Europe
- Higher open (Euro Stoxx 50 +0.5%), tracking Asia and softer oil.
4. FX & Rates: Safe‑Haven Unwind
- USD weaker for a third session as oil eased and risk appetite improved.
- JPY and EUR strengthened, reflecting rotation out of havens.
- Bonds steadier ahead of central‑bank risk; positioning remains cautious.
5. Commodities: Oil Still the Swing Variable
- Brent & WTI lower after:
- Iraq–Kurdistan agreement to resume exports
- No fresh escalation overnight
- Supply fears remain:
- Strait of Hormuz disruption unresolved
- Drone attacks on regional energy assets continue
- Gold steady near record highs, supported by geopolitics despite the risk‑on tone.
6. Iran Conflict: Escalation Risk Persists
- US confirmed strikes on Iranian missile sites along the Hormuz coastline using deep‑penetrator munitions.
- Iran acknowledged the killing of security chief Larijani and responded with missile launches, including cluster munitions.
- Multiple Gulf states (UAE, Kuwait, Saudi Arabia, Qatar) reported missile and drone interceptions.
- Russia reportedly increased intelligence and drone support to Iran, raising strategic risks.
- Saudi Arabia convenes Arab and Islamic foreign ministers today on regional security.
Bottom line:
Markets are pricing containment, not resolution.
7. Macro & Data Today
- 13:30 CET – US PPI (Feb): expected +0.3% MoM (inflation watch).
- 15:30 CET – EIA crude inventories: key for near‑term oil direction.
- EZ CPI Final (Feb) and NZ GDP (Q4) also due.
8. Corporate & Single‑Stock News
- Beyond Meat:
- Delays annual report after preliminary Q4 revenue miss.
- Shares −4.1% after hours; stock −78% in 2025.
- Weak demand as consumers shift away from premium processed foods.
- Amazon:
- Raised ad‑free Prime Video price to $4.99/month (“Prime Video Ultra”), reinforcing pricing power.
9. Trade & Tech
- Reports that Chinese firms received approval to buy NVIDIA H200 AI chips, supporting selective China tech sentiment.
- US exploring new trade coordination mechanisms with China, while EU advances toward a trade deal with Australia.
10. DAX Technical Analysis
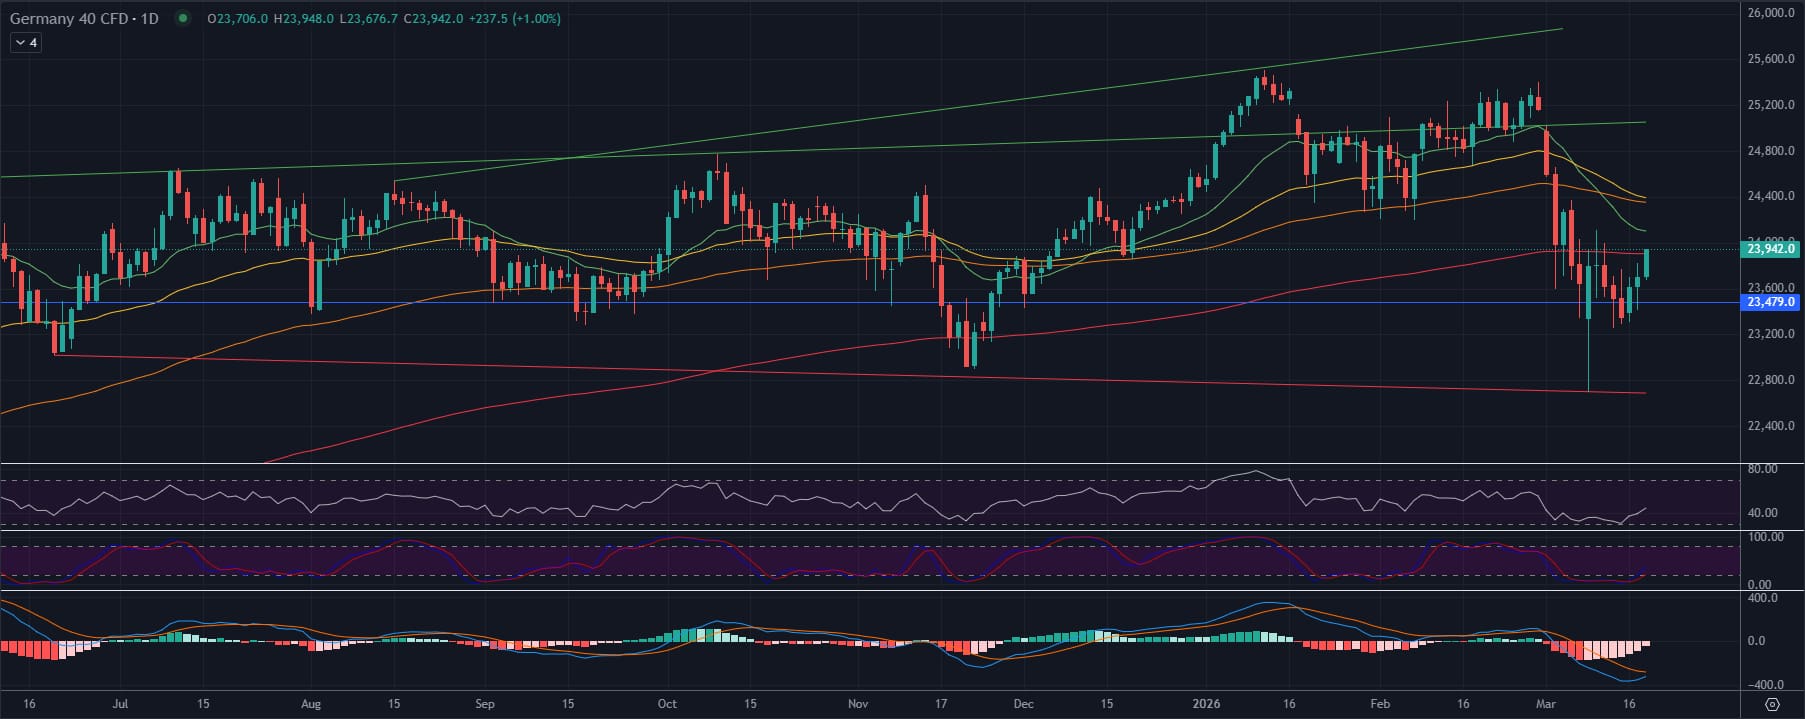
The Germany 40 is attempting to stabilize after the sharp breakdown from the 25,200–24,800 zone. Price is trading below the 50‑day and 100‑day moving averages, while the 200‑day SMA is currently being tested. The recent rebound from the 23,300 area appears corrective so far, with 3 consecutive positive days. As long as price remains above the 200 EMA, the risk of renewed downside toward 23,300 and potentially 22,800 remains muted.
Momentum indicators are showing some recovery with the RSI around 50, but moving upwards indicating building bullish momentum, while the Stochastic RSI is rebounding from oversold levels, pointing to short‑term stabilization and moving higher. MACD remains in negative territory, although downside momentum appears to be easing indicated by the consecutively smaller histogram bars, and the potential of the blue line crossing over the orange line. Overall, the daily bias appears relatively cautious, and if we hold the 24,000 mark (200 EMA), this could improve the outlook and signal a sustained recovery.
-Philip Papageorgiou – Markt Analyst
--X ex Twitter: PhilipForexCom



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.

Gold Price Forecast: XAU/USD Plunges 12.4% Toward Critical Support 10 1 2026
Softer inflation has revived expectations for a Fed pause, but Friday’s payrolls could put gold’s recovery prospects to the test.


Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.