

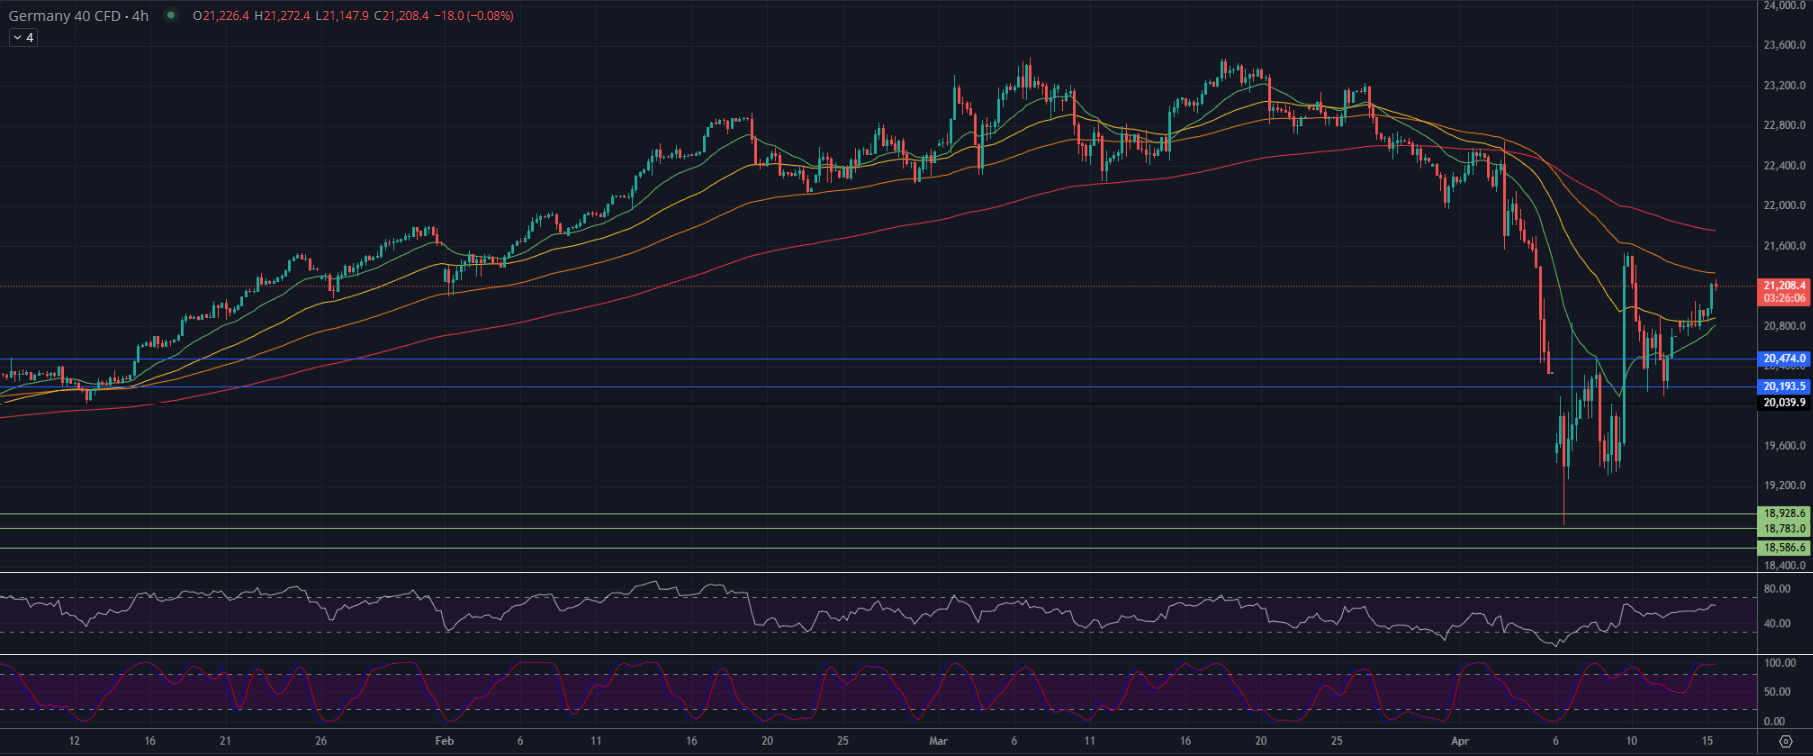


DAX Tests 21400 Resistance; Focus on rare metals
DAX rises to 21,208, testing resistance at 21,200–21,400, as markets await further Tariff news. The U.S.-China trade conflict continues to escalate, with China leveraging rare earths in negotiations. Tech stocks remain volatile, and oil prices are under pressure. Key focus today: earnings from J&J, Bank of America, Citigroup, and United Airlines. A breakout above the 100 EMA could open the path toward 21,700+.
Share this:

Morning Brief – April 15, 2025
US-China Trade Conflict Intensifies
The US continues to apply maximum pressure, aiming to establish a broader trade alliance against China. China, in response, has implemented targeted counter-tariffs and export controls. Market indicators, notably the persistently high VIX and VIX futures, suggest markets expect no swift resolution.
· Asian shares rose on hopes for US auto tariff exemptions; particularly benefiting Japanese automakers.
· Market caution persists due to uncertainties around broader US trade policies, notably regarding semiconductors and pharmaceuticals.
· US and European futures indicate weaker openings, reflecting ongoing recession worries and inflation concerns.
· Treasury yields stabilized following recent declines, supported by dovish Fed signals on potential tariff-related rate cuts.
· Dollar weakened, near multi-year lows against euro and Swiss franc, amid reduced safe-haven appeal and rising inflation.
· UK unemployment steady at 4.4%; wage growth matched forecasts.
DAX Technical Analysis 4 hours
The Germany 40 (DAX) – 4H chart shows continued strength after the sharp rebound from the April lows, with the price currently at 21,208.4, just testing the 100 EMA. This marks a key level where bulls and bears are battling for control following the recent breakout above the 20,474 resistance.
Technical Breakdown:
- Trend recovery: After forming a solid bottom near 18,600, the DAX has staged a multi-leg recovery, reclaiming the 20 EMA and now pushing into a critical confluence of resistance EMAs (50/100/200).
- Price structure: A higher high has formed above the April 10 swing, and the market is now testing to confirm a trend reversal or just a bear market rally.
Indicators:
- RSI (4H): Approaching 70, indicating strong momentum but nearing overbought territory.
- Stochastic RSI: Already overbought, which could suggest short-term consolidation or a pullback, especially if resistance holds.
Key Levels:
Resistance:
- 🔴 21,200–21,400: EMA 100 + recent breakdown area
- 🟠 21,700–22,000: Strong resistance zone capped by EMA 200
- 🟤 22,400–22,800: Next structural level for bulls if rally continues
Support:
- 🔵 20,474: Recent breakout level – must hold for bulls
- 🔵 20,193 / 20,039: Psychological support area
- 🟢 18,928–18,586: Long-term base support
Summary:
The DAX is at a crucial turning point. A sustained break and hold above 21,400 would likely confirm a shift back to bullish structure, opening the path toward 21,700–22,000. However, failure here — especially with overbought momentum indicators — could lead to a pullback to retest the 20,474 zone.
Short-term bias: Bullish but extended – watch for a breakout confirmation or consolidation.
Rare Earths as China's Strategic Leverage
China recently imposed export controls on heavy rare earths, crucial materials used in magnets for electric motors, electronics, defense, and robotics. Effective since April 4, these controls aren't a complete blockade but allow Beijing to manage exports strategically, significantly impacting US high-tech industries. China controls approximately 90% of global production of 17 of these metals and possesses extensive refining capabilities. Although rare earth exports represent a minor share of China's total exports, their strategic importance to US technology sectors positions them as powerful leverage in ongoing negotiations.
Volatility in US Markets Amid Tariff Uncertainty
Despite a strong performance last week, US markets remain volatile, still down significantly since Trump's tariff announcement on April 2, with the S&P 500 down 6%, and Nasdaq and Dow Jones each down about 5%. The weekend brought some relief as smartphones, laptops, and key electronics were exempted from recent tariffs, temporarily benefiting companies like Apple and Nvidia. However, Commerce Secretary Howard Lutnick indicated additional tariffs are imminent, particularly targeting semiconductors, adding to ongoing market uncertainty.
Corporate Earnings Spotlight
Today’s market will closely watch corporate earnings:
- Johnson & Johnson (JNJ): Expected EPS $2.57; anticipated stock move: $5.36.
- Bank of America (BAC): Expected EPS $0.81; anticipated stock move: $2.04. Analysts anticipate an EPS of approximately $0.82, reflecting a modest year-over-year increase. Consensus estimates project revenues around $26.9 billion, indicating a 4% growth compared to the same quarter last year.
- Citigroup (C): Expected EPS $1.84; anticipated stock move: $3.72.
- United Airlines (UAL): Postmarket EPS expectation of $0.80; anticipated move: $6.41.
Oil Price Outlook
Goldman Sachs projects declining oil prices through 2026, citing recession risks and increased OPEC+ supply. Forecasted average prices for Brent and WTI in 2025 are $63 and $59 per barrel, decreasing to $58 and $55 respectively in 2026.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.


RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.