
DAX Traders Watch 25,500 as Tech Rebound Meets Oil Risks
The DAX is attempting to extend its recovery as improving sentiment around technology stocks supports European equities. Strong AI-related updates from Super Micro Computer and SpaceX have boosted risk appetite, helping the index move back above key short-term averages. However, rising oil prices, persistent inflation concerns and Middle East tensions remain major obstacles. The key test for today is whether the DAX can sustain a move above 25,500 and confirm that the recovery has further room to run.
Share this:
DAX 40 Technical Analysis: Technology Rebound Supports European Futures, but Oil and Inflation Risks Persist
Wednesday, 21 October 2026
Market overview: A tentative recovery faces important resistance
The DAX 40 is attempting to stabilise following Monday’s sharp reversal and the subsequent weakness in European equities. Renewed demand for technology stocks has improved the overnight market tone, with European equity futures opening firmer.
From a technical perspective, the DAX is trading around 25,350 after opening around 25,450, above its EMA 100 and EMA 50 near 25,270 and 25,300 but below its declining 200-day average around 25,550. Making the DAX be between short-term support and a strong overhead resistance.
Daily chart: Neutral outlook with resistance overhead
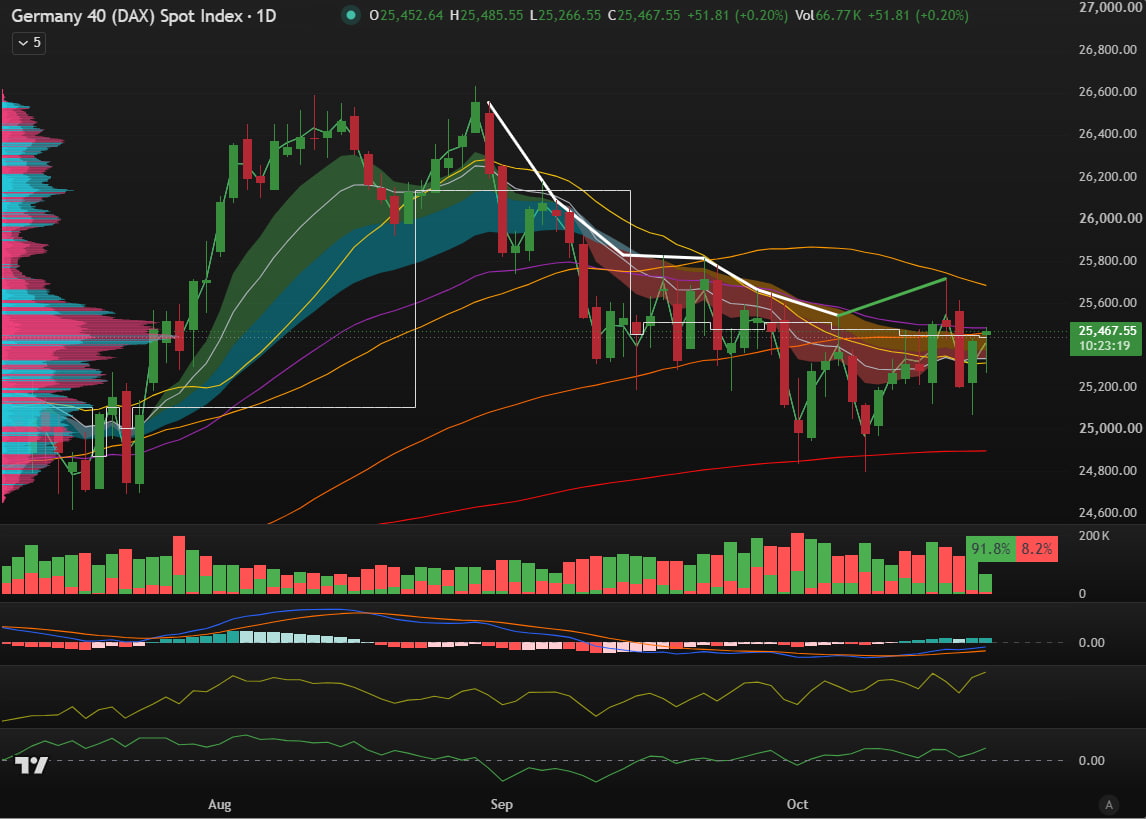
The daily chart continues to show a corrective phase following the DAX’s late-August peak near 26,600. The index has formed a series of lower highs, indicating that sellers have retained control of the medium-term price structure even as buyers have defended the October lows.
The 50-day moving average, currently around 25,670, remains the principal dynamic resistance but the EMA 100 at 25,450 has also acted as resistance on several occasions and is closer to the current market price.
By contrast, the 200 EMA is rising to near 24,900 and remains an important structural support. The index has already tested that level, twice during October, without establishing a decisive break lower and recovering to above the 25,00 level. This suggests that longer-term buyers are still defending the market, although repeated tests of support can eventually weaken it.
Generally. momentum appears to be improving from the early-October lows, but the recovery has yet to reverse the broader pattern of lower highs. A daily close above 25,600 would be the first significant signal that buyers are regaining control and would strengthen a bullish pressure higher. Beyond that level, 26,000 represents the next major psychological and technical resistance, followed by the late-summer highs near 26,600.
A failure to sustain the rebound would leave the index vulnerable to renewed selling though. Initial support lies around 25,295 (EMA 20), followed by the 24,890–24,830 (EMA 200) region. A daily close below this lower support cluster would materially weaken the longer-term technical picture and expose the next downside area around 24,600.
Four-hour chart: Short-term recovery gains traction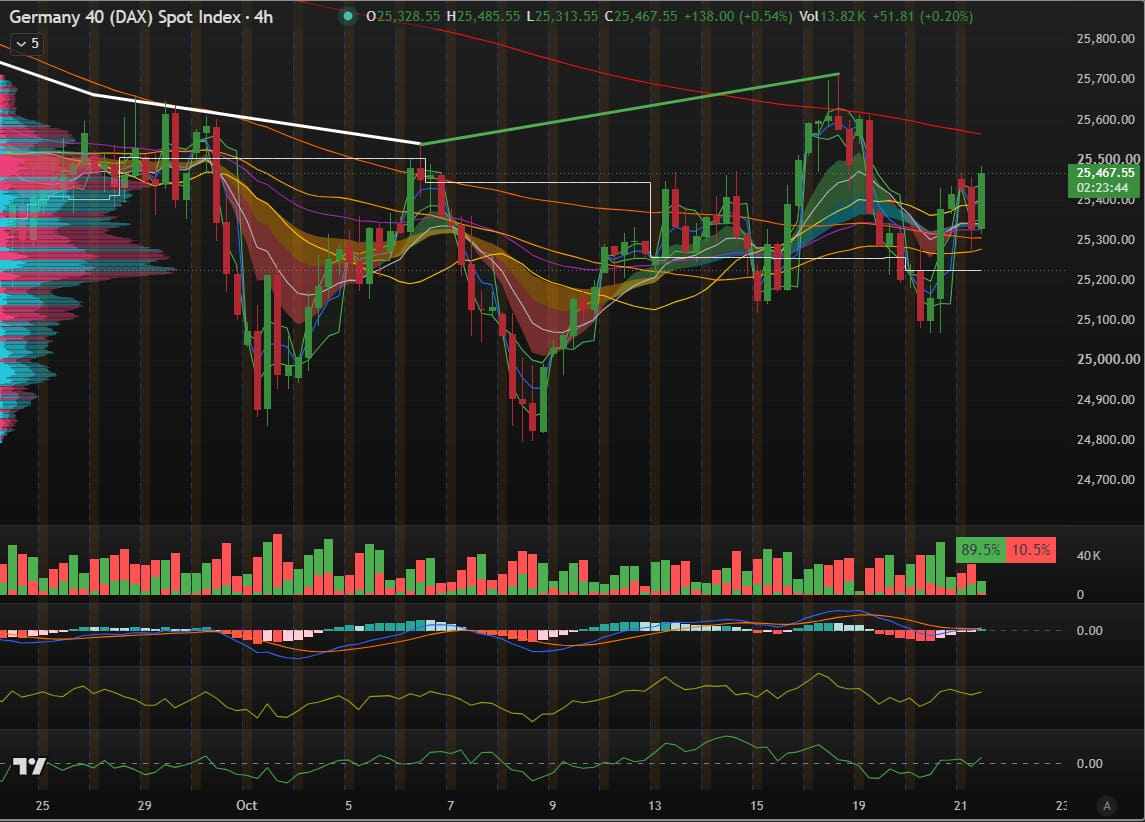
The four-hour chart shows a more constructive picture than the daily timeframe. The latest technical indicators identify a short-term bullish bias. The index is trading above its 100 EMA and 50 EMA levels near 25,310 and 25,275.
The first support zone sits between exactly those 2 levels above. However holding above at least yesterday’s low at 25,100 and October low at 24,800 is required to maintain the short-term bullish recovery.
However, the index is approaching a region where sellers have previously emerged strongly. A brief move above resistance would not, by itself, confirm a trend reversal. Buyers would need to establish acceptance above 25,600 -25,700 and prevent the market from falling back to its recent trading range.
If the index loses 25,100, the recovery could begin to weaken.
What is driving the market today?
1. Technology stocks rebound, improving the European outlook
The main positive development in the overnight session is a recovery in technology-related equities. Asian markets were mostly firmer following gains in US after-hours trading, supported by upbeat guidance from Super Micro Computer and encouraging financial results from SpaceX.
Super Micro Computer’s preliminary revenue outlook exceeded expectations, reflecting continued demand for AI infrastructure. SpaceX also reported quarterly revenue and earnings above forecasts. These developments helped lift US equity futures, with Nasdaq futures outperforming, and contributed to expectations of a firmer European open.
For the DAX, improved sentiment towards technology and AI infrastructure can support risk appetite, particularly through semiconductor and industrial technology stocks. However, the rebound should not be interpreted as a complete resolution of concerns about AI investment returns, debt financing and stretched valuations. US technology stocks remained mixed in the previous session, with the Nasdaq 100 underperforming the broader market.
2. UK inflation accelerates, reinforcing concerns about price pressures
Data released this morning showed that annual consumer price inflation increased to 3.5% in September, from 3.1% in August. Core CPI rose to 2.8% from 2.6%, while services inflation increased to 3.7% from 3.4%.
Transport, particularly motor fuels, made the largest upward contribution to the monthly change in headline inflation. The figures highlight the potential for higher energy and transport costs to feed into broader price pressures.
Although UK inflation does not directly determine German inflation or European Central Bank policy, it influences the wider European rates outlook. If markets interpret the data as evidence that inflation is proving persistent, expectations for monetary easing could be reduced, putting upward pressure on bond yields and equity valuations.
3. Middle East tensions keep oil and supply-chain risks elevated
Geopolitical developments remain a significant source of uncertainty. Crude futures moved higher amid concerns surrounding the Strait of Hormuz, including threats from Iran’s Islamic Revolutionary Guard Corps to target internet cables in the area. Iranian state-linked media also reported that a supertanker had struck a sea mine and exploded near Hormuz;
The broader concern is the potential for further disruption to energy flows and maritime transport because any sustained increase in oil prices would raise production, transport and logistics costs for European businesses.
This is relevant to the DAX because of its exposure to industrial companies, automotive manufacturers, chemicals and other energy-intensive businesses. Higher input costs would compress margins, while renewed inflation concerns may also weigh on market valuations.
Diplomatic development remains important. Indirect US–Iran negotiations are reportedly continuing through intermediary countries, but the parties remain divided over the conditions required for a broader agreement. Until there is clearer evidence of de-escalation, geopolitical risk is likely to remain a source of volatility for European equities.
4. Corporate earnings could determine whether the rebound lasts
The earnings calendar is another potential catalyst. Companies including SAP, Tesla, IBM, Meta and Texas Instruments, alongside several other major US and European businesses will report earnings today.
SAP is particularly relevant to the German market because of its weight and importance within the domestic technology sector. Results and guidance from major technology companies can also influence sentiment towards AI investment, enterprise spending and semiconductor demand.
A stronger earnings backdrop could help the DAX overcome near-term technical resistance. Conversely, disappointing guidance or renewed concerns about the profitability of AI-related investment could undermine the recovery and encourage investors to sell into strength.
Conclusion
The DAX 40 is showing signs of a short-term recovery on the 4h chart, but the broader technical picture remains weak. Technology-sector strength and a firmer European futures outlook provide support, while higher oil prices, persistent inflation risks and geopolitical uncertainty continue to limit confidence.
The key level for today is 25,500. A sustained break above it would strengthen the bullish case and open the way towards 25,700. Failure at resistance, followed by a break below 25,300, would suggest that the rebound is losing momentum and increase the risk of another test of the October lows.
For now, the most appropriate assessment is short-term cautiously bullish, medium-term neutral.
Stay informed,
By Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Traders Watch 25,500 as Tech Rebound Meets Oil Risks
The DAX is attempting to extend its recovery as improving sentiment around technology stocks supports European equities. Strong AI-related updates from Super Micro Computer and SpaceX have boosted risk appetite, helping the index move back above key short-term averages. However, rising oil prices, persistent inflation concerns and Middle East tensions remain major obstacles. The key test for today is whether the DAX can sustain a move above 25,500 and confirm that the recovery has further room to run.
GBP/USD, DAX Forecast: Two trades to watch
GBP/USD unchanged despite UK inflation jumping to an 11-month high. DAX steady after Space-X earnings revive AI trade but oil limits gains.

GBP/USD, DAX Forecast: Two trades to watch
GBP/USD unchanged despite UK inflation jumping to an 11-month high. DAX steady after Space-X earnings revive AI trade but oil limits gains.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.