


Dow Jones Analysis: DJIA Attempts to Return to Record Highs
The Dow Jones Index has now posted two consecutive bullish sessions, gaining more than 1.4% in the short term and once again approaching its record highs, signaling renewed buying momentum in the equity market.
Share this:
The Dow Jones Index has now posted two consecutive bullish sessions, gaining more than 1.4% in the short term and once again approaching its record highs, signaling renewed buying momentum in the equity market. Buying pressure has remained firm, mainly supported by positive expectations surrounding the new corporate earnings season and a slightly softer tone in comments related to the trade war. As long as these factors persist, demand for equities could remain relevant in the coming trading sessions.


What’s Driving Demand?
The Dow Jones started the week on a positive note, led by the strong performance of Apple and Salesforce, which both posted gains close to 4.00%. This rebound has helped restore investor confidence and strengthen the index’s bullish bias in recent sessions.
In Salesforce’s case, the company announced its long-term projections, anticipating revenues of $60 billion by 2030 and expanding its share buyback program by $7 billion — a clear signal of confidence to the market. The stock has begun recovering from this year’s lows, near $230.
Meanwhile, Apple has seen renewed investor confidence amid optimism about upcoming product launches and recent technological improvements announced by the company. The stock has already surpassed its yearly highs, reaching the $260 area. Both companies, which currently hold the 14th and 15th spots in the index composition, have played a key role in the Dow Jones recovery and in sustaining its recent appreciation.
This confidence is also reflected among the top five stocks in the index. With the exception of Home Depot, which has seen a slight -0.64% decline, the others have posted gains above 0.8%, showing that the market maintains a positive tone in the short term.

Source: Slickcharts
Another key factor is the possibility that the United States and China are moderating their stance in the trade war. Both countries have emphasized the need to keep diplomatic channels open, and the upcoming meeting between the Chinese Vice Premier and the U.S. Treasury Secretary in Malaysia is expected to help ease tensions over the coming days.
However, this rebound in confidence could be temporary, as it largely depends on whether corporate results exceed market expectations. Companies like Coca-Cola and Procter & Gamble — both part of the Dow Jones — will release their earnings reports on October 21 and 24, respectively. Although the market remains optimistic ahead of these announcements, strong results will be necessary to sustain current demand and prevent a reversal in sentiment.
Additionally, the brief easing of trade tensions has also contributed to short-term optimism, though it could quickly fade if no real progress is achieved in negotiations between the U.S. and China. In this sense, the prevailing buying pressure may be temporary and will depend on developments throughout the week. If expectations fall short, the Dow Jones Index could once again face a bearish bias in the coming sessions.
How Is Confidence Holding Up?
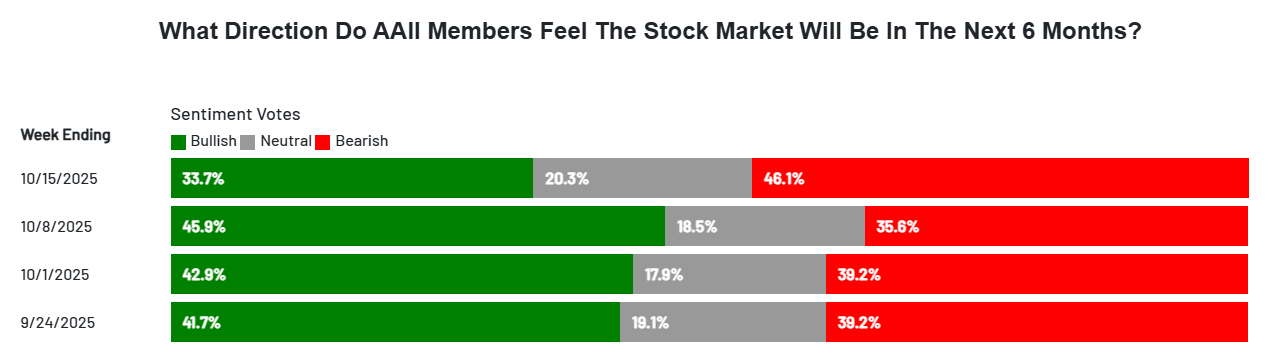
Although short-term confidence has gradually improved in recent sessions, the long-term outlook for the equity market remains fragile. According to the AAII Investor Sentiment Survey, 33.7% of respondents maintain a bullish view for the next six months, 20.3% are neutral, and 46.1% hold a bearish outlook, based on data for the week ending October 15.
Source: AAII
In this context, as long as long-term sentiment remains negative, the short-term recovery could be only a temporary effect without a structural basis to support sustained demand for the index in the coming months. If confidence indicators fail to show a meaningful improvement, it could lead to renewed selling pressure on Dow Jones fluctuations in the weeks ahead.
Dow Jones Technical Outlook

Source: StoneX, Tradingview
- Renewed Buying Momentum: In recent sessions, upward price movements have pushed the Dow Jones toward record highs, maintaining a relevant bullish bias in the short term. If the price manages to consolidate again near these levels, the uptrend that prevailed for much of the year — and was interrupted weeks ago — could resume. However, as the price approaches the 46,800-point resistance, market indecision may increase, making it difficult to break through this barrier in the coming sessions.
- RSI: The RSI line continues to show a steady upward move, with readings above the neutral 50 level, indicating that the average buying strength over the past 14 sessions remains solid. If this trend continues, it could further support short-term buying pressure.
- MACD: The MACD remains near the neutral line (0), reflecting a balance between buying and selling strength. This technical neutrality could lead to a phase of price indecision, which is consistent with the index’s typical behavior when it approaches record highs.
Key Levels:
- 46,800 points – Major Resistance: This level corresponds to the index’s record highs. A sustained breakout above this area could reactivate the previous uptrend, which currently remains secondary.
- 45,700 points – Current Barrier: This area coincides with the 50-period simple moving average. As long as the price holds here, the index could consolidate in a neutral scenario or even form a sideways channel in the coming sessions.
- 44,800 points – Key Support: This level aligns with the Ichimoku Cloud. A sustained break below it would confirm a structural shift in market momentum, potentially giving way to a new short-term bearish trend.
Written by Julian Pineda, CFA – Market Analyst
Follow him on: @julianpineda25
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Wall Street Forecast: DJIA rises on hawkish Fed expectations & rising yields
U.S. stocks are opening lower on Wednesday, pressured by higher crude oil prices and rising government bond yields, as investors await further developments from negotiations in the Middle East and ahead of a key U.S.-China summit.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.


Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.