



Dow Jones Forecast: DJIA slips as Middle East tensions lift oil and treasury yields
U.S. stocks are heading for a weaker start as fresh tensions between the U.S. and Iran, fading prospects of a peace deal in the Middle East and rising oil prices raise concerns over the inflation outlook
Share this:


US futures
Dow futures 0.1%, S&P futures 0.47% & Nasdaq futures -1.2%
European futures
FTSE -0.2%, DAX -0.5%
- US stocks fall as US-Iran peace hopes fade
- US 30-year Treasury yield at a 19-year high
- FOMC minutes will be released tomorrow
- Oil rises amid continued Middle East supply concerns
U.S. stocks fall as US-Iran peace hopes fade, oil, treasury yields rise
U.S. stocks are heading for a weaker start as fresh tensions between the U.S. and Iran, fading prospects of a peace deal in the Middle East and rising oil prices raise concerns over the inflation outlook.
After Wall Street posted minor losses on Monday, all three major indices are pointing to a modestly lower open, following weakness across European markets.
President Trump said he would not extend the ceasefire with Iran, which expired yesterday, while Iran has shifted to a fully offensive military posture as diplomatic efforts to end the war have stalled.
The developments have pushed oil prices higher, bringing inflation concerns back into focus.
The 10-year Treasury yield is now at its highest level since January 2025, while the 30-year Treasury yield has reached its highest level since 2007.
With oil rising towards $90 a barrel, investors are increasingly concerned about the possibility of a more prolonged inflation shock.
However, fiscal concerns are also playing a role. The size of U.S. government debt continues to put pressure on longer-term borrowing costs, particularly as investors question how quickly the fiscal position can improve.
Interestingly, both short- and long-term yields are rising even as markets have reduced expectations for Fed rate hikes. The market is now pricing in a 96% probability of at least one Fed rate hike before the end of the year.
Attention will turn to tomorrow's FOMC meeting minutes for further clues over the Fed's view on inflation and the outlook for interest rates.
Rising yields is pulling tech stocks sharply lower, causing the Nasdaq to underperform.
Corporate Movers
Home Depot is rising 1.5% after the home improvement retailer posted fiscal Q2 earnings that beat expectations on both the top and bottom lines and reaffirmed its full-year guidance.
Tesla is falling 1.2% following reports that it will launch its Cybercab robotaxi, which has no steering wheel, brake or accelerator pedals, on Austin streets this month.
Memory chipmakers are under pressure in pre-market trading, with Micron and SK Hynix both down more than 4%. Sandisk is also lower amid continued volatility across memory stocks.
Dow Jones Forecast – Technical Analysis
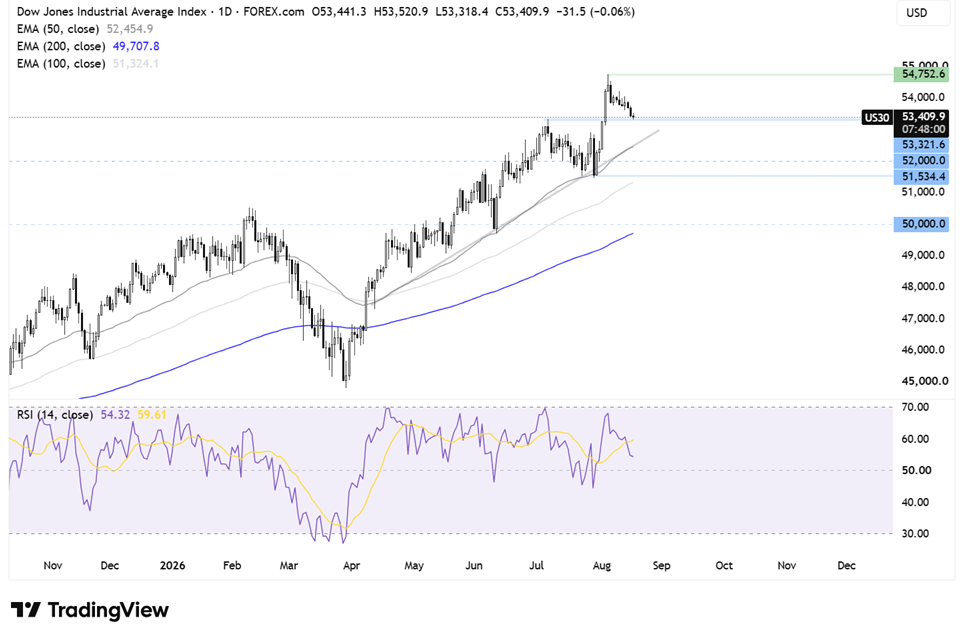
The Dow Jones ran into resistance at the record high of 54,750, forming a shooting-star reversal candle before easing lower towards 53,400.
The index remains above its rising trend line and both the 50 and 200 EMAs, so despite the pullback, the broader trend remains constructive.
Sellers would need to break below 53,000, around the July high, to weaken the near-term uptrend. Below here, attention turns towards 52,600, where the 50 EMA and rising trend line support converge.
It would take a break below 51,500, the July low, to create a lower low and change the structure of the chart to bearish.
FX Markets – Dollar Firms, GBP/USD Falls
The U.S. dollar is rising slightly, supported by safe-haven demand and the fact that the U.S. is a net oil exporter, following President Trump's decision not to extend the ceasefire with Iran. However, gains could be limited as markets have reduced expectations for further Fed rate hikes following recent U.S. economic data.
EUR/USD is falling after three straight days of gains as the dollar strengthens, despite stronger-than-expected German ZEW economic sentiment. Economic sentiment improved to 34.2 in August from 26.3 in July, beating expectations of 30. The current situation index also came in ahead of forecasts. This marks the fourth straight month of improving German investor confidence, helped by a strong earnings season and signs that the economy is recovering from some of the disruption caused by the Iran war.
GBP/USD is falling after UK labour market data showed further weakness in the second quarter, with private-sector earnings growth slowing and vacancies falling. UK unemployment remained unchanged at 4.9%, against expectations of a decline to 4.8%. Meanwhile, private-sector earnings growth slowed to 2.8%, the weakest level in six years, while vacancies fell to their lowest level since late 2014, excluding the pandemic period. The data suggests that the UK jobs market is no longer generating the wage pressure that would force the Bank of England to raise rates. However, it is also not weakening quickly enough to make aggressive rate cuts the obvious next step.
Oil rises as Middle East tensions raise supply concerns
Oil prices are pushing higher for a third straight day on Tuesday as hopes of a deal to end the Middle East conflict fade.
Brent has climbed towards $90 a barrel, while WTI is around $85 after President Trump decided not to extend the U.S.-Iran ceasefire on Monday, adding to concerns over the Strait of Hormuz.
While some oil is still managing to transit through the strait, crossings remain in single digits.
Iran has separately been negotiating with Oman over an agreement to manage the Strait of Hormuz and has said the two sides are close to a deal. However, Trump has responded to those talks by threatening to bomb Oman.
With no clear signs of de-escalation and oil flows through the Strait still heavily restricted, supply concerns are keeping prices supported.
For oil prices to move lower, the market will likely need to see clearer signs that tensions are easing and that normal shipping through the Strait of Hormuz can resume.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.


Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

US Dollar Technical Outlook: DXY Bulls Meet Resistance at Yearly Highs 10 1 2026
The U.S. Dollar has held firm despite fading Fed hike bets, but Friday’s payrolls could test the rally’s staying power.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.