



EU indices slightly up TA focus on Hugo Boss
European stocks report | Berkeley | Hugo Boss | Iberdrola | Colruyt...
Share this:
INDICES
Yesterday, European stocks recorded beefy gains, with the Stoxx Europe 600 Index advancing 2.9%. Germany's DAX 30 surged 3.4%, France's CAC 40 rose 2.8%, and the U.K.'s FTSE 100 jumped 2.9%.
EUROPE ADVANCE/DECLINE
97% of STOXX 600 constituents traded higher yesterday.
73% of the shares trade above their 20D MA vs 44% Monday (below the 20D moving average).
38% of the shares trade above their 200D MA vs 32% Monday (below the 20D moving average).
The Euro Stoxx 50 Volatility index eased 2.32pts to 36.1, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: none
3mths relative low: none
Europe Best 3 sectors
construction & materials, banks, telecommunications
Europe worst 3 sectors
travel & leisure, real estate, health care
INTEREST RATE
The 10yr Bund yield fell 1bp to -0.45% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -22bps (above its 20D MA).
ECONOMIC DATA
UK 07:00: May Core Inflation Rate MoM, exp.: 0.1%
UK 07:00: May PPI Output YoY, exp.: -0.7%
UK 07:00: May PPI Input YoY, exp.: -9.8%
UK 07:00: May PPI Input MoM, exp.: -5.1%
UK 07:00: May PPI Output MoM, exp.: -0.7%
UK 07:00: May Core Inflation Rate YoY, exp.: 1.4%
UK 07:00: May Inflation Rate MoM, exp.: -0.2%
UK 07:00: May Inflation Rate YoY, exp.: 0.8%
UK 07:00: May PPI Core Output YoY, exp.: 0.6%
UK 07:00: May PPI Core Output MoM, exp.: -0.1%
UK 07:00: May Retail Price Idx MoM, exp.: 0%
UK 07:00: May Retail Price Idx YoY, exp.: 1.5%
EC 10:00: May Inflation Rate MoM final, exp.: 0.3%
EC 10:00: May Core Inflation Rate YoY final, exp.: 0.9%
EC 10:00: May Inflation Rate YoY final, exp.: 0.3%
EC 10:00: Apr Construction Output YoY, exp.: -15.4%
EC 10:00: ECB Mersch speech
GE 10:40: 10-Year Bund auction, exp.: -0.47%
EC 12:00: ECB Guindos speech
MORNING TRADING
In Asian trading hours, EUR/USD was little changed at 1.1259 while GBP/USD dropped to 1.2546. USD/JPY fell to 107.22. This morning, government data showed that Japan's exports decline 28.3% on year in May (-26.1% expected) and imports sank 26.2% (-20.4% expected),
Spot gold eased to $1,724 an ounce.
#UK - IRELAND#
Berkeley, a property developer, posted full-year results: "Revenue of £1,920.4 million in the year (2019: £2,957.4 million) arose primarily from the sale of new homes in London and the South East. (...) Pre-tax return on equity for the year is 16.6%, compared to 27.9% last year reflecting the return of profitability to normal levels. Basic earnings per share has decreased by 32.5% from 481.1 pence to 324.9 pence. (...) Berkeley starts the coming year from a position of relative strength, with net cash of £1,138.9 million, forward sales of £1.9 billion and an estimated £6.4 billion of gross profit in our land holdings."
Kingfisher, a retailer, announced that full-year post-tax profit plunged 95.9% on year to 8 million pounds, citing 441 million exceptional charges related to store and Russia impairments. Also, Revenue was down 1.5% (-1.5% like-for-like) to 11.51 billion pounds. The company said "no specific guidance provided for FY 20/21 given the uncertainty around COVID-19".
BHP Group, a multinational mining group, announced the appointment of David Lamont, currently CFO of ASX-listed global biotech company CSL, as new CFO, effective December 1.
Serco Group, a provider of public services, issued a 1H trading update: "We expect revenue of around £1.8bn in the first half of 2020, around 23% higher than the £1.5bn reported in the first half of 2019. (...) We expect first half UTP (Underlying trading profit) of £75m-£80m, about 50% more than the £51m reported last year."
William Hill, a bookmaker, announced it has raised 224 million pounds through the placing of new ordinary shares of 10p each.
WPP, an advertising and public relations company, was upgraded to "buy" from "neutral" at Goldman Sachs.
#GERMANY#
Hugo Boss, a luxury fashion house, announced the appointment of Daniel Grieder, former CEO of Tommy Hilfiger Global and PVH Europe, as future CEO for period of five years starting on June 1, 2021. From a chartist point of view, the share is capped by a declining trend line drawn from 2018 and continues to develop a process of lower tops and lower bottoms. Look for a re-test of 19 and even 10 in extension.
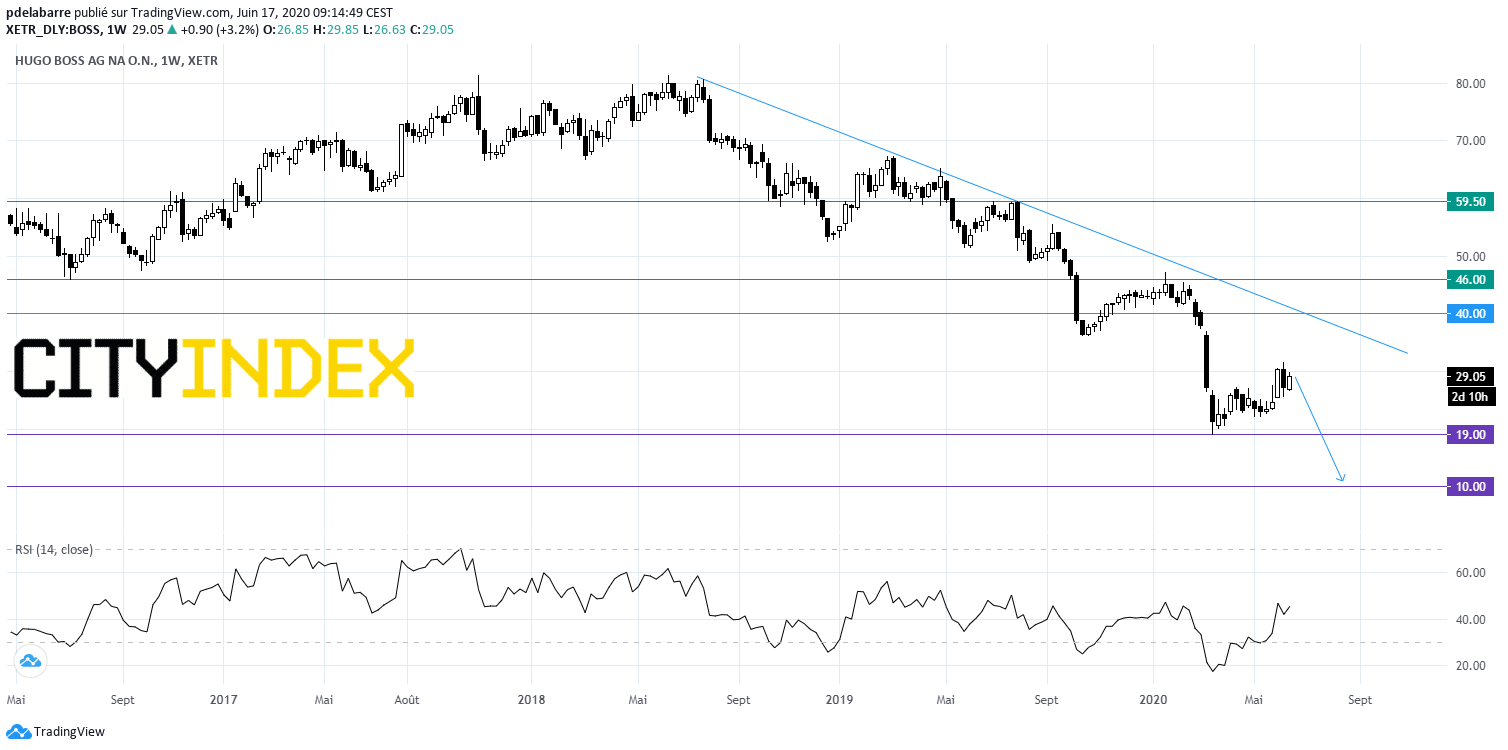
Source: GAIN Capital, TradingView
RWE, an electricity and gas supplier, was upgraded to "buy" from "hold" at HSBC.
#FRANCE#
Icade, a real estate investment trust, said easyHotel has signed an 12-year off-plan lease for a 180-room hotel covering 4,000 square metre to be housed in its soon-to-be-built JUMP building, located in Paris. Financial terms were not disclosed.
BNP Paribas, a banking group, was downgraded to "sell" from "hold" at Societe Generale.
#SPAIN#
Iberdrola, a Spanish electric utility group, announced that it has agreed to acquire Australian renewable energy company Infigen for 0.86 Australian dollar per share, implying a diluted equity value of 841 million Australian dollars.
#BENELUX#
Colruyt, a retail group, announced that full-year net income rose 12.2% on year to 431 million euros and EBIT grew 5.4% to 511 million euros on revenue of 9.58 billion euros, up 1.6% (+1.7% on a comparable basis). The company proposed a gross dividend of 1.35 euros per share.
#ITALY#
Recordati, a pharmaceutical group, was upgraded to "buy" from "neutral" at Goldman Sachs.
#SWITZERLAND#
Novartis, a pharmaceutical group, said the U.S. Food and Drug Administration has approved its Cosentyx for the treatment of active non-radiographic axial spondyloarthritis.
#SCANDINAVIA - DENMARK#
Telia, a Swedish telecommunications group, confirmed that it is in talks regarding a potential sale of its indirect stake in Turkcell to the Turkish Wealth Fund for 530 million dollars.
Pandora, a Danish jewellery retailer, was upgraded to "buy" from "hold" at HSBC.
EX-DIVIDEND
Swedbank: SEK8.8
Yesterday, European stocks recorded beefy gains, with the Stoxx Europe 600 Index advancing 2.9%. Germany's DAX 30 surged 3.4%, France's CAC 40 rose 2.8%, and the U.K.'s FTSE 100 jumped 2.9%.
EUROPE ADVANCE/DECLINE
97% of STOXX 600 constituents traded higher yesterday.
73% of the shares trade above their 20D MA vs 44% Monday (below the 20D moving average).
38% of the shares trade above their 200D MA vs 32% Monday (below the 20D moving average).
The Euro Stoxx 50 Volatility index eased 2.32pts to 36.1, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: none
3mths relative low: none
Europe Best 3 sectors
construction & materials, banks, telecommunications
Europe worst 3 sectors
travel & leisure, real estate, health care
INTEREST RATE
The 10yr Bund yield fell 1bp to -0.45% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -22bps (above its 20D MA).
ECONOMIC DATA
UK 07:00: May Core Inflation Rate MoM, exp.: 0.1%
UK 07:00: May PPI Output YoY, exp.: -0.7%
UK 07:00: May PPI Input YoY, exp.: -9.8%
UK 07:00: May PPI Input MoM, exp.: -5.1%
UK 07:00: May PPI Output MoM, exp.: -0.7%
UK 07:00: May Core Inflation Rate YoY, exp.: 1.4%
UK 07:00: May Inflation Rate MoM, exp.: -0.2%
UK 07:00: May Inflation Rate YoY, exp.: 0.8%
UK 07:00: May PPI Core Output YoY, exp.: 0.6%
UK 07:00: May PPI Core Output MoM, exp.: -0.1%
UK 07:00: May Retail Price Idx MoM, exp.: 0%
UK 07:00: May Retail Price Idx YoY, exp.: 1.5%
EC 10:00: May Inflation Rate MoM final, exp.: 0.3%
EC 10:00: May Core Inflation Rate YoY final, exp.: 0.9%
EC 10:00: May Inflation Rate YoY final, exp.: 0.3%
EC 10:00: Apr Construction Output YoY, exp.: -15.4%
EC 10:00: ECB Mersch speech
GE 10:40: 10-Year Bund auction, exp.: -0.47%
EC 12:00: ECB Guindos speech
MORNING TRADING
In Asian trading hours, EUR/USD was little changed at 1.1259 while GBP/USD dropped to 1.2546. USD/JPY fell to 107.22. This morning, government data showed that Japan's exports decline 28.3% on year in May (-26.1% expected) and imports sank 26.2% (-20.4% expected),
Spot gold eased to $1,724 an ounce.
#UK - IRELAND#
Berkeley, a property developer, posted full-year results: "Revenue of £1,920.4 million in the year (2019: £2,957.4 million) arose primarily from the sale of new homes in London and the South East. (...) Pre-tax return on equity for the year is 16.6%, compared to 27.9% last year reflecting the return of profitability to normal levels. Basic earnings per share has decreased by 32.5% from 481.1 pence to 324.9 pence. (...) Berkeley starts the coming year from a position of relative strength, with net cash of £1,138.9 million, forward sales of £1.9 billion and an estimated £6.4 billion of gross profit in our land holdings."
Kingfisher, a retailer, announced that full-year post-tax profit plunged 95.9% on year to 8 million pounds, citing 441 million exceptional charges related to store and Russia impairments. Also, Revenue was down 1.5% (-1.5% like-for-like) to 11.51 billion pounds. The company said "no specific guidance provided for FY 20/21 given the uncertainty around COVID-19".
BHP Group, a multinational mining group, announced the appointment of David Lamont, currently CFO of ASX-listed global biotech company CSL, as new CFO, effective December 1.
Serco Group, a provider of public services, issued a 1H trading update: "We expect revenue of around £1.8bn in the first half of 2020, around 23% higher than the £1.5bn reported in the first half of 2019. (...) We expect first half UTP (Underlying trading profit) of £75m-£80m, about 50% more than the £51m reported last year."
William Hill, a bookmaker, announced it has raised 224 million pounds through the placing of new ordinary shares of 10p each.
WPP, an advertising and public relations company, was upgraded to "buy" from "neutral" at Goldman Sachs.
#GERMANY#
Hugo Boss, a luxury fashion house, announced the appointment of Daniel Grieder, former CEO of Tommy Hilfiger Global and PVH Europe, as future CEO for period of five years starting on June 1, 2021. From a chartist point of view, the share is capped by a declining trend line drawn from 2018 and continues to develop a process of lower tops and lower bottoms. Look for a re-test of 19 and even 10 in extension.
Source: GAIN Capital, TradingView
RWE, an electricity and gas supplier, was upgraded to "buy" from "hold" at HSBC.
#FRANCE#
Icade, a real estate investment trust, said easyHotel has signed an 12-year off-plan lease for a 180-room hotel covering 4,000 square metre to be housed in its soon-to-be-built JUMP building, located in Paris. Financial terms were not disclosed.
BNP Paribas, a banking group, was downgraded to "sell" from "hold" at Societe Generale.
#SPAIN#
Iberdrola, a Spanish electric utility group, announced that it has agreed to acquire Australian renewable energy company Infigen for 0.86 Australian dollar per share, implying a diluted equity value of 841 million Australian dollars.
#BENELUX#
Colruyt, a retail group, announced that full-year net income rose 12.2% on year to 431 million euros and EBIT grew 5.4% to 511 million euros on revenue of 9.58 billion euros, up 1.6% (+1.7% on a comparable basis). The company proposed a gross dividend of 1.35 euros per share.
#ITALY#
Recordati, a pharmaceutical group, was upgraded to "buy" from "neutral" at Goldman Sachs.
#SWITZERLAND#
Novartis, a pharmaceutical group, said the U.S. Food and Drug Administration has approved its Cosentyx for the treatment of active non-radiographic axial spondyloarthritis.
#SCANDINAVIA - DENMARK#
Telia, a Swedish telecommunications group, confirmed that it is in talks regarding a potential sale of its indirect stake in Turkcell to the Turkish Wealth Fund for 530 million dollars.
Pandora, a Danish jewellery retailer, was upgraded to "buy" from "hold" at HSBC.
EX-DIVIDEND
Swedbank: SEK8.8
INDICES
Yesterday, European stocks recorded beefy gains, with the Stoxx Europe 600 Index advancing 2.9%. Germany's DAX 30 surged 3.4%, France's CAC 40 rose 2.8%, and the U.K.'s FTSE 100 jumped 2.9%.
EUROPE ADVANCE/DECLINE
97% of STOXX 600 constituents traded higher yesterday.
73% of the shares trade above their 20D MA vs 44% Monday (below the 20D moving average).
38% of the shares trade above their 200D MA vs 32% Monday (below the 20D moving average).
The Euro Stoxx 50 Volatility index eased 2.32pts to 36.1, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: none
3mths relative low: none
Europe Best 3 sectors
construction & materials, banks, telecommunications
Europe worst 3 sectors
travel & leisure, real estate, health care
INTEREST RATE
The 10yr Bund yield fell 1bp to -0.45% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -22bps (above its 20D MA).
ECONOMIC DATA
UK 07:00: May Core Inflation Rate MoM, exp.: 0.1%
UK 07:00: May PPI Output YoY, exp.: -0.7%
UK 07:00: May PPI Input YoY, exp.: -9.8%
UK 07:00: May PPI Input MoM, exp.: -5.1%
UK 07:00: May PPI Output MoM, exp.: -0.7%
UK 07:00: May Core Inflation Rate YoY, exp.: 1.4%
UK 07:00: May Inflation Rate MoM, exp.: -0.2%
UK 07:00: May Inflation Rate YoY, exp.: 0.8%
UK 07:00: May PPI Core Output YoY, exp.: 0.6%
UK 07:00: May PPI Core Output MoM, exp.: -0.1%
UK 07:00: May Retail Price Idx MoM, exp.: 0%
UK 07:00: May Retail Price Idx YoY, exp.: 1.5%
EC 10:00: May Inflation Rate MoM final, exp.: 0.3%
EC 10:00: May Core Inflation Rate YoY final, exp.: 0.9%
EC 10:00: May Inflation Rate YoY final, exp.: 0.3%
EC 10:00: Apr Construction Output YoY, exp.: -15.4%
EC 10:00: ECB Mersch speech
GE 10:40: 10-Year Bund auction, exp.: -0.47%
EC 12:00: ECB Guindos speech
MORNING TRADING
In Asian trading hours, EUR/USD was little changed at 1.1259 while GBP/USD dropped to 1.2546. USD/JPY fell to 107.22. This morning, government data showed that Japan's exports decline 28.3% on year in May (-26.1% expected) and imports sank 26.2% (-20.4% expected),
Spot gold eased to $1,724 an ounce.
#UK - IRELAND#
Berkeley, a property developer, posted full-year results: "Revenue of £1,920.4 million in the year (2019: £2,957.4 million) arose primarily from the sale of new homes in London and the South East. (...) Pre-tax return on equity for the year is 16.6%, compared to 27.9% last year reflecting the return of profitability to normal levels. Basic earnings per share has decreased by 32.5% from 481.1 pence to 324.9 pence. (...) Berkeley starts the coming year from a position of relative strength, with net cash of £1,138.9 million, forward sales of £1.9 billion and an estimated £6.4 billion of gross profit in our land holdings."
Kingfisher, a retailer, announced that full-year post-tax profit plunged 95.9% on year to 8 million pounds, citing 441 million exceptional charges related to store and Russia impairments. Also, Revenue was down 1.5% (-1.5% like-for-like) to 11.51 billion pounds. The company said "no specific guidance provided for FY 20/21 given the uncertainty around COVID-19".
BHP Group, a multinational mining group, announced the appointment of David Lamont, currently CFO of ASX-listed global biotech company CSL, as new CFO, effective December 1.
Serco Group, a provider of public services, issued a 1H trading update: "We expect revenue of around £1.8bn in the first half of 2020, around 23% higher than the £1.5bn reported in the first half of 2019. (...) We expect first half UTP (Underlying trading profit) of £75m-£80m, about 50% more than the £51m reported last year."
William Hill, a bookmaker, announced it has raised 224 million pounds through the placing of new ordinary shares of 10p each.
WPP, an advertising and public relations company, was upgraded to "buy" from "neutral" at Goldman Sachs.
#GERMANY#
Hugo Boss, a luxury fashion house, announced the appointment of Daniel Grieder, former CEO of Tommy Hilfiger Global and PVH Europe, as future CEO for period of five years starting on June 1, 2021. From a chartist point of view, the share is capped by a declining trend line drawn from 2018 and continues to develop a process of lower tops and lower bottoms. Look for a re-test of 19 and even 10 in extension.
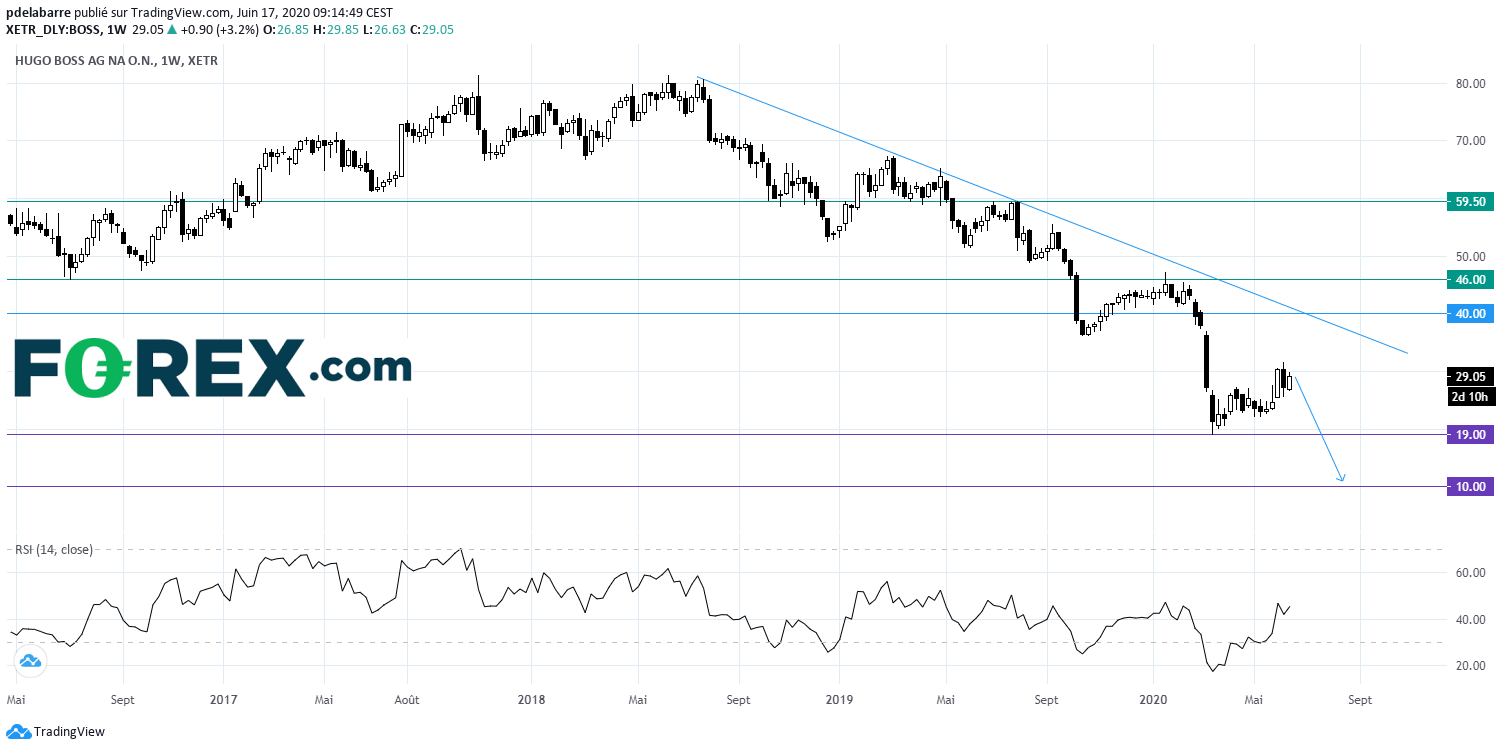
Source: GAIN Capital, TradingView
RWE, an electricity and gas supplier, was upgraded to "buy" from "hold" at HSBC.
#FRANCE#
Icade, a real estate investment trust, said easyHotel has signed an 12-year off-plan lease for a 180-room hotel covering 4,000 square metre to be housed in its soon-to-be-built JUMP building, located in Paris. Financial terms were not disclosed.
BNP Paribas, a banking group, was downgraded to "sell" from "hold" at Societe Generale.
#SPAIN#
Iberdrola, a Spanish electric utility group, announced that it has agreed to acquire Australian renewable energy company Infigen for 0.86 Australian dollar per share, implying a diluted equity value of 841 million Australian dollars.
#BENELUX#
Colruyt, a retail group, announced that full-year net income rose 12.2% on year to 431 million euros and EBIT grew 5.4% to 511 million euros on revenue of 9.58 billion euros, up 1.6% (+1.7% on a comparable basis). The company proposed a gross dividend of 1.35 euros per share.
#ITALY#
Recordati, a pharmaceutical group, was upgraded to "buy" from "neutral" at Goldman Sachs.
#SWITZERLAND#
Novartis, a pharmaceutical group, said the U.S. Food and Drug Administration has approved its Cosentyx for the treatment of active non-radiographic axial spondyloarthritis.
#SCANDINAVIA - DENMARK#
Telia, a Swedish telecommunications group, confirmed that it is in talks regarding a potential sale of its indirect stake in Turkcell to the Turkish Wealth Fund for 530 million dollars.
Pandora, a Danish jewellery retailer, was upgraded to "buy" from "hold" at HSBC.
EX-DIVIDEND
Swedbank: SEK8.8
Yesterday, European stocks recorded beefy gains, with the Stoxx Europe 600 Index advancing 2.9%. Germany's DAX 30 surged 3.4%, France's CAC 40 rose 2.8%, and the U.K.'s FTSE 100 jumped 2.9%.
EUROPE ADVANCE/DECLINE
97% of STOXX 600 constituents traded higher yesterday.
73% of the shares trade above their 20D MA vs 44% Monday (below the 20D moving average).
38% of the shares trade above their 200D MA vs 32% Monday (below the 20D moving average).
The Euro Stoxx 50 Volatility index eased 2.32pts to 36.1, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: none
3mths relative low: none
Europe Best 3 sectors
construction & materials, banks, telecommunications
Europe worst 3 sectors
travel & leisure, real estate, health care
INTEREST RATE
The 10yr Bund yield fell 1bp to -0.45% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -22bps (above its 20D MA).
ECONOMIC DATA
UK 07:00: May Core Inflation Rate MoM, exp.: 0.1%
UK 07:00: May PPI Output YoY, exp.: -0.7%
UK 07:00: May PPI Input YoY, exp.: -9.8%
UK 07:00: May PPI Input MoM, exp.: -5.1%
UK 07:00: May PPI Output MoM, exp.: -0.7%
UK 07:00: May Core Inflation Rate YoY, exp.: 1.4%
UK 07:00: May Inflation Rate MoM, exp.: -0.2%
UK 07:00: May Inflation Rate YoY, exp.: 0.8%
UK 07:00: May PPI Core Output YoY, exp.: 0.6%
UK 07:00: May PPI Core Output MoM, exp.: -0.1%
UK 07:00: May Retail Price Idx MoM, exp.: 0%
UK 07:00: May Retail Price Idx YoY, exp.: 1.5%
EC 10:00: May Inflation Rate MoM final, exp.: 0.3%
EC 10:00: May Core Inflation Rate YoY final, exp.: 0.9%
EC 10:00: May Inflation Rate YoY final, exp.: 0.3%
EC 10:00: Apr Construction Output YoY, exp.: -15.4%
EC 10:00: ECB Mersch speech
GE 10:40: 10-Year Bund auction, exp.: -0.47%
EC 12:00: ECB Guindos speech
MORNING TRADING
In Asian trading hours, EUR/USD was little changed at 1.1259 while GBP/USD dropped to 1.2546. USD/JPY fell to 107.22. This morning, government data showed that Japan's exports decline 28.3% on year in May (-26.1% expected) and imports sank 26.2% (-20.4% expected),
Spot gold eased to $1,724 an ounce.
#UK - IRELAND#
Berkeley, a property developer, posted full-year results: "Revenue of £1,920.4 million in the year (2019: £2,957.4 million) arose primarily from the sale of new homes in London and the South East. (...) Pre-tax return on equity for the year is 16.6%, compared to 27.9% last year reflecting the return of profitability to normal levels. Basic earnings per share has decreased by 32.5% from 481.1 pence to 324.9 pence. (...) Berkeley starts the coming year from a position of relative strength, with net cash of £1,138.9 million, forward sales of £1.9 billion and an estimated £6.4 billion of gross profit in our land holdings."
Kingfisher, a retailer, announced that full-year post-tax profit plunged 95.9% on year to 8 million pounds, citing 441 million exceptional charges related to store and Russia impairments. Also, Revenue was down 1.5% (-1.5% like-for-like) to 11.51 billion pounds. The company said "no specific guidance provided for FY 20/21 given the uncertainty around COVID-19".
BHP Group, a multinational mining group, announced the appointment of David Lamont, currently CFO of ASX-listed global biotech company CSL, as new CFO, effective December 1.
Serco Group, a provider of public services, issued a 1H trading update: "We expect revenue of around £1.8bn in the first half of 2020, around 23% higher than the £1.5bn reported in the first half of 2019. (...) We expect first half UTP (Underlying trading profit) of £75m-£80m, about 50% more than the £51m reported last year."
William Hill, a bookmaker, announced it has raised 224 million pounds through the placing of new ordinary shares of 10p each.
WPP, an advertising and public relations company, was upgraded to "buy" from "neutral" at Goldman Sachs.
#GERMANY#
Hugo Boss, a luxury fashion house, announced the appointment of Daniel Grieder, former CEO of Tommy Hilfiger Global and PVH Europe, as future CEO for period of five years starting on June 1, 2021. From a chartist point of view, the share is capped by a declining trend line drawn from 2018 and continues to develop a process of lower tops and lower bottoms. Look for a re-test of 19 and even 10 in extension.
Source: GAIN Capital, TradingView
RWE, an electricity and gas supplier, was upgraded to "buy" from "hold" at HSBC.
#FRANCE#
Icade, a real estate investment trust, said easyHotel has signed an 12-year off-plan lease for a 180-room hotel covering 4,000 square metre to be housed in its soon-to-be-built JUMP building, located in Paris. Financial terms were not disclosed.
BNP Paribas, a banking group, was downgraded to "sell" from "hold" at Societe Generale.
#SPAIN#
Iberdrola, a Spanish electric utility group, announced that it has agreed to acquire Australian renewable energy company Infigen for 0.86 Australian dollar per share, implying a diluted equity value of 841 million Australian dollars.
#BENELUX#
Colruyt, a retail group, announced that full-year net income rose 12.2% on year to 431 million euros and EBIT grew 5.4% to 511 million euros on revenue of 9.58 billion euros, up 1.6% (+1.7% on a comparable basis). The company proposed a gross dividend of 1.35 euros per share.
#ITALY#
Recordati, a pharmaceutical group, was upgraded to "buy" from "neutral" at Goldman Sachs.
#SWITZERLAND#
Novartis, a pharmaceutical group, said the U.S. Food and Drug Administration has approved its Cosentyx for the treatment of active non-radiographic axial spondyloarthritis.
#SCANDINAVIA - DENMARK#
Telia, a Swedish telecommunications group, confirmed that it is in talks regarding a potential sale of its indirect stake in Turkcell to the Turkish Wealth Fund for 530 million dollars.
Pandora, a Danish jewellery retailer, was upgraded to "buy" from "hold" at HSBC.
EX-DIVIDEND
Swedbank: SEK8.8
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.