



EU Markets Open Lower as Earnings Season and Iran Risks Weigh
European markets are set for a weaker open as elevated energy prices, unresolved Iran tensions and a busy earnings slate test risk appetite. Despite ceasefire language, physical risks around the Strait of Hormuz remain high, keeping a geopolitical premium priced into oil. With earnings from major US and European corporates underway, markets are balancing company results against persistent macro and geopolitical uncertainty.
Share this:
EU Market Open – Key Takeaways
Market Snapshot
- Europe: Set for a lower open; Euro Stoxx 50 futures -1.0%
- Energy: Brent trading around $102/bbl, elevated but off intraday highs
- Risk tone: Defensive / risk‑off bias driven by persistent Middle East uncertainty
- APAC: Mostly negative; energy the key outperformer
DAX Technical Analysis
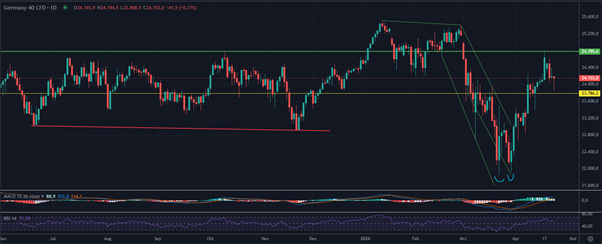
The Germany 40 has rebounded sharply from the March low near 22,100–22,300, retracing a significant portion of the prior sell‑off but now stalling below key resistance. The index failed to hold above the 24,800 resistance zone, which marks the former range top and the breakdown level from February, confirming it as strong supply. Price is currently consolidating around 24,100–24,200, above interim support near 23,780, but still below the broader resistance band at 24,700–24,800. Structurally, the move higher appears corrective within a wider consolidation rather than a clean trend resumption, unless price can regain the upper green resistance line.
Momentum indicators suggest improving conditions but with fading upside conviction. MACD has crossed into positive territory and continues to rise, indicating that bearish momentum has been neutralized for now. RSI is holding near 56, consistent with neutral‑to‑constructive momentum but not strong enough to confirm a breakout. The lack of follow‑through above 24,800 keeps the risk of renewed consolidation or pullback alive. Overall, the bias remains neutral‑bullish above 23,780, but a sustained daily close above 24,800 is required to confirm trend continuation toward the highs, while failure risks a retracement back toward 23,800–23,600.
Geopolitics – Iran Conflict
Ceasefire & Negotiation Signals
- Trump (Fox):
- Expects Iranian FM Araghchi to remain involved in talks
- Denied reports of a 3–5 day ceasefire, saying no fixed timeline exists
- White House: No deadline set for Iran’s proposal; ceasefire timing dictated by Trump
- Iran (President Pezeshkian):
- Iran remains open to dialogue
- Blockade, threats, and breaches of commitments cited as main obstacles to real negotiations
- Reports suggest Washington wants “understandings” by Sunday, not just talks
Escalation & Security Risks
- Military posture:
- Third US aircraft carrier (USS Bush) heading toward the Middle East
- Pentagon warns clearing Hormuz of mines could take six months
- Maritime incidents:
- US intercepted and redirected ≥3 Iranian oil tankers
- Iran reportedly seized two vessels in the Strait of Hormuz
- Iranian rhetoric hardening:
- Hormuz reopening “impossible” under a naval blockade
- Explicit threats against regional energy infrastructure
- Air defences reportedly activated against UAVs
- Regional developments:
- UK and allies preparing mine‑clearing contingency operations
- Israel–Lebanon talks scheduled in Washington; Lebanon to seek one‑month ceasefire extension
Market implication:
- Despite ceasefire language, physical supply risks remain elevated, keeping a geopolitical premium priced into crude and weighing on risk assets.
Equities
Europe
- Futures point to a defensive open
- Losers: Cyclicals, consumer, transport (oil‑sensitive)
- Support: Energy and defence stocks
United States (Prior Session)
- Equities rallied on ceasefire extension, despite firm oil:
- S&P 500: +1.05%
- Nasdaq 100: +1.73%
- Dow: +0.69%
- Russell 2000: +0.74%
- Tape reflects conflicting forces: lower immediate war risk vs. ongoing Hormuz disruption
Asia‑Pacific
- Mostly lower:
- Japan: Nikkei retreated from record highs above 60k amid oil volatility
- Australia: Lower despite PMI returning to expansion; energy the sole outperformer
- China/HK: Dragged by autos & retail weakness, offsetting energy gains
FX
- USD (DXY): Rangebound; geopolitics dominates, Fed in blackout
- EUR/USD: Soft, briefly below 1.1700, weighed by oil surge and weak EU sentiment
- GBP/USD: Choppy near 1.3500; domestic political noise adds pressure
- USD/JPY: Directionless; brief upside on oil‑driven yen weakness
- AUD/NZD: Subdued despite stronger PMI data
- CNY: PBoC fix remains firmer than market expectations
Fixed Income
- USTs: Subdued after prior curve flattening; front‑end yields sensitive to oil‑led inflation risk
- Bunds: Fell to weekly lows amid:
- Rising energy prices
- Fresh supply
- Germany growth downgrades
- JGBs: Pressured by energy‑linked inflation concerns
Commodities
- Crude Oil:
- Early aggressive rally faded due to lack of fresh catalysts
- Still structurally supported by tanker seizures, blockade risk, and mine threats
- Gold: Choppy around $4,700/oz; safe‑haven demand offset by higher yields/oil
- Copper: Pulled back as Asian risk appetite weakened
Crypto
- Bitcoin: Drifted lower, slipping below $78,000, tracking broader risk‑off tone
Macro & Events to Watch (Today)
Data
- Global Flash PMIs (Apr) – growth vs. inflation momentum
- UK PSNB (Mar)
- French Business Confidence (Apr)
- Mexican Inflation (Apr)
- Canada PPI (Mar)
- US Jobless Claims
Central Banks
- ECB Wage Tracker – second‑round inflation focus
Earnings Highlights
- US: Blackstone, Freeport‑McMoRan, American Airlines, Intel, Lockheed Martin, Keurig Dr Pepper
- Europe: SAP, Safran, Sanofi, Vinci, Orange
Bottom Line
- Markets are pricing persistent energy disruption risk, not outright escalation.
- Bias: Defensive positioning favoured while Brent holds above $100.
- Key trigger: Any credible signal of blockade easing or Hormuz reopening would quickly reprice crude and risk sentiment—absence of that keeps the skew risk‑off.
Philip Papageorgiou
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

US Midterm Fallout: What Does the “Blue Tsunami” Mean for the S&P 500?
Democrats made sweeping gains in the US midterm elections, winning control of both the House and Senate - what does it mean for the S&P 500 and the AI trade?

Euro Technical Outlook: EUR/USD Support Reversal Sets Up Breakout Test Ahead of NFP 11 4 2026
Euro bulls are attempting to build on the rebound from recent lows, but pivotal resistance still stands in the way of a larger EUR/USD recovery.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.