



Europe Points Higher After China Trade Mix Up PMIs Next
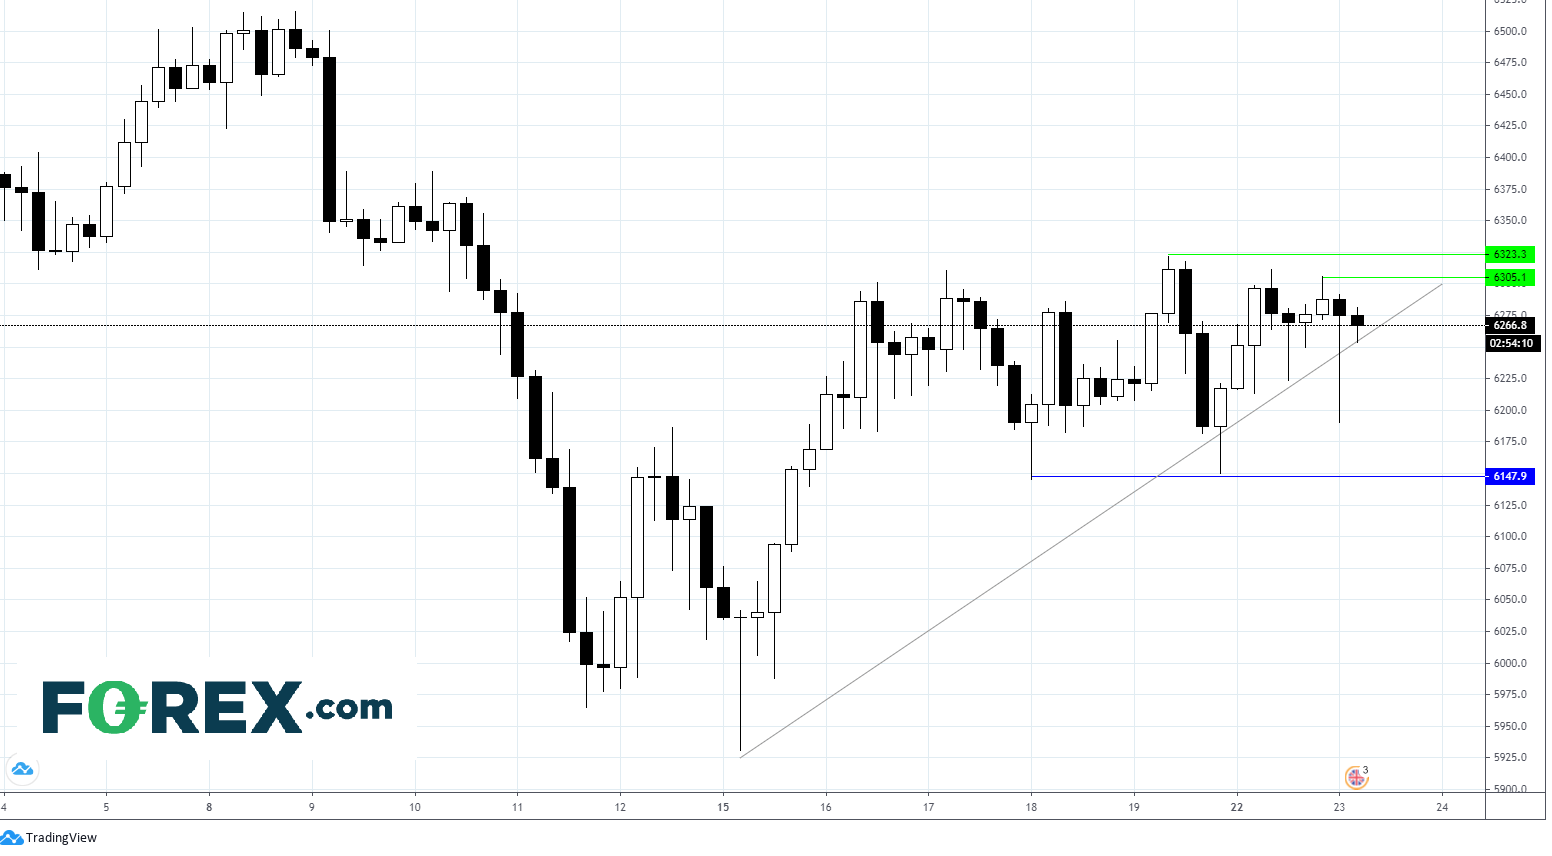
After some whipsaw action in the Asian session as the White House’s stance on China was thrown into confusion, the waters have calmed and Europe is pointing higher.
Share this:

After some whipsaw action in the Asian session as the White House’s stance on China was thrown into confusion, the waters have calmed, and European bourses are pointing to a mildly higher open.
Trump was the saving grace, walking back on Trade Secretary Perter Navarro’s assertion that the trade deal with China was over. Trump swiftly contradicted the claim, saying that the China trade deal was “fully intact”.
There is no smoke without fire. Navarro is one of the most outspoken critics of China among Trump’s senior advisors. However, we know that relations between the US and China have been on a knife’s edge for a while. The market movements overnight show that the markets are still sensitive to US – Sino trade relations. There is a good chance that US – China trade relations could return with vigor in the second part of the year as the global economy recovers from covid-19 outbreak and as we head towards the US elections.
Reopening optimism overshadows second wave fears
Concerns over a second wave of coronavirus infections remain, although Beijing has seen fewer new cases, lifting sentiment. However, Germany’s recent flare up has seen the R rate push higher again.
Concerns over a second wave of coronavirus infections remain, although Beijing has seen fewer new cases, lifting sentiment. However, Germany’s recent flare up has seen the R rate push higher again.
Optimism surrounding the reopening of the UK economy is adding to the risk on mood, with Boris Johnson expected to announce a reduction in the 2 meter rule, in addition to adding cinema’s, museums and galleries to the list of premises able to reopen on 4th July. Expectations of US and Spanish stimulus are also bolstering the mood in the market ahead of Purchasing Mangers Index data.
PMIs to show the worst has past
Looking ahead, the focus shifts towards purchasing managers index data which will released from the UK, Eurozone and the US providing a decent picture as to how the economic recovery is developing.
PMIs across the board are expected to confirm that April was the trough from the coronavirus economic catastrophe and that the recovery has been gathering pace ever since. Service sector and manufacturing sector PMI readings are expected to reveal that the pace of contraction slowed again in Jun. The data is also expected to show that activity in the sectors remains in contraction, with the service sector, which bore the brunt of the lockdown measures, lagging.
In the UK the manufacturing sector PMI is expected to increase to 45 in June, up from 40.7. The service sector is due to jump from 29 in May to 39.5 this month. A better than expected reading could boost the Pound and keep risk sentiment buoyant, supporting stocks.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.