



European Market Open | Investors Eye Fed Speakers Amid Trade and Shutdown Stalemate
European equities opened softer on Thursday as investors awaited UK and Eurozone GDP data and a wave of Fed speakers, while the US shutdown stalemate and renewed tariff rhetoric tempered risk appetite. Gold held above $4,200/oz, extending record gains on dovish Fed signals, and oil firmed slightly after US inventory data. The DAX continues to consolidate between 24,000 and 24,510, awaiting a breakout for direction. Markets remain data-driven and sensitive to policy tone.
Share this:
European Market Open | Investors Eye GDP & Fed Speakers Amid Trade and Shutdown Stalemate
Market Overview
- Asia: Stocks mostly higher, taking the lead from Wall Street’s late-session rebound.
- ASX 200 hit a record high on softer yields and strong miners.
- Nikkei 225 advanced despite weak machinery orders and mixed BoJ commentary.
- Hang Seng / Shanghai Comp lagged amid renewed US–China trade tensions and reports that the FCC will expel Hong Kong Telecom from US networks.
- Europe: Futures point lower — Euro Stoxx 50 –0.4% after Wednesday’s +1.0% close.
- US Futures: Flat after Wednesday’s gains (SPX +0.41%, NDX +0.68%, DJI –0.04%, RUT +0.89%).
Today’s focus:
- Data: UK GDP (Aug), Eurozone Trade Balance (Aug), Philly Fed (Oct), Atlanta Fed GDP.
- Central Banks: Fed’s Waller, Barkin, Barr, Miran, Bowman, Kashkari; ECB’s Lane, Lagarde; BoC’s Macklem; BoE’s Greene, Mann.
- Earnings: TSMC, Bank of New York Mellon, KeyCorp, Charles Schwab, United Airlines, ABB, Bankinter.
- Suspended: US Weekly Claims, PPI (Sep), Retail Sales (Sep).
Asia-Pacific Highlights
- Japan: BoJ’s Tamura — “push rates toward neutral” but no sharp tightening needed.
- Australia: Job data missed; Unemployment 4.5%.
- RBA: Bullock/Kent noted policy “marginally tight,” not restrictive.
- Tri-lateral Meeting: BoJ, PBoC, BoK met in Washington; discussed macro coordination.
Europe & UK
- UK:
- Chancellor Reeves: Higher taxes on wealthy “part of the story”; fiscal buffer may need GBP 50bn (IFS).
- Launching initiative with top pension funds to boost domestic investment.
- ECB:
- Villeroy: Global economy resilient; next move “more likely a cut.”
- Makhlouf: Inflation where they want it; Kocher: regulation too complex.
- France: PM Lecornu secures Socialist backing; pension reform suspended, budget targets EUR 31bn in cost cuts.
Germany – DAX Technical Outlook 4 H
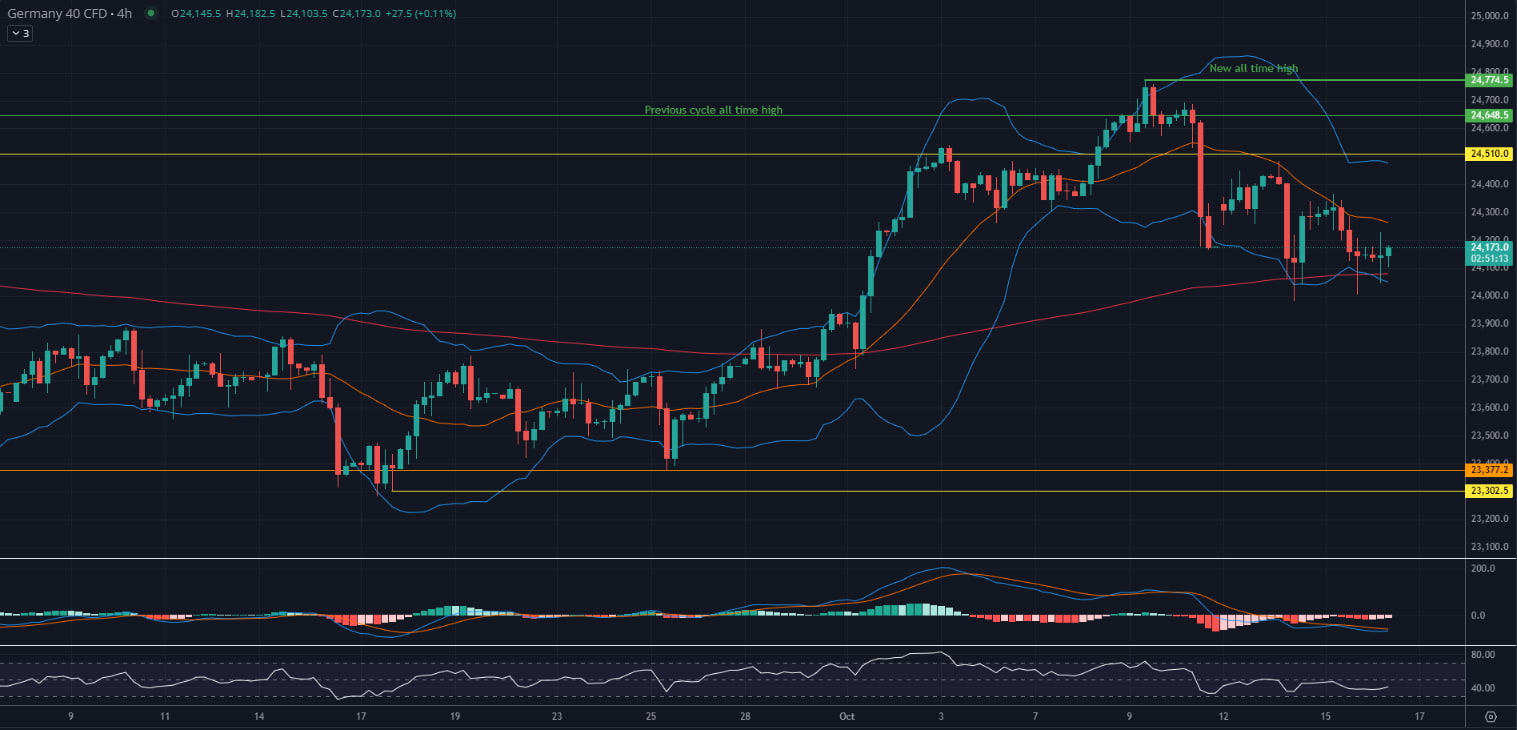
The Germany 40 (4H) continues to consolidate after failing to hold above 24,510, with price stabilizing around 24,150–24,200 near the 200 EMA. The MACD remains flat and below the signal line, reflecting weak momentum, while the RSI (around 45) signals neutral conditions. The market is compressing between lower highs and steady support, hinting at a coiling phase ahead of a breakout.
Key resistance stands at 24,350–24,510, followed by the 24,648–24,775 all-time-high zone. Support remains firm at 24,000, with deeper downside limited to 23,800–23,650 if momentum fades. A breakout above 24,510 would restore the bullish structure, while a close below 24,000 would turn the bias bearish short term. Tone: neutral, awaiting directional confirmation.
US Recap
- Equities: Wall Street finished higher despite choppy trading.
- Tech rebounded late after an early dip triggered by an Anthropic AI update that revived concerns NVDA chips may be overbought.
- Focus remained on US–China trade rhetoric and the ongoing government shutdown.
- Index moves today: SPX +0.41% (6,672) · NDX +0.68% (24,745) · DJI –0.04% (46,253) · RUT +0.89% (2,518).
Trade & Tariffs
- Trump: Declared “we are in a trade war with China,” calling tariffs essential for national security.
- South Korea: Claimed to have signed a USD 350bn US investment deal; Treasury’s Bessent expects resolution of tariff issues “within 10 days.”
- Mexico: In talks to reduce tariffs on heavy-truck parts.
- China: Transport Ministry launched an investigation into US Section 301 tariffs on shipping; MOFCOM warned the US cannot “threaten and negotiate simultaneously.”
- Other: US regulators found no widespread appliance tariff evasion (WSJ).
Monetary Policy & Fed Speak
- Miran (voter): AI investment may raise the neutral rate, but Fed policy is currently more restrictive than perceived; sees urgency in reaching neutrality faster.
- Waller (voter): Warned AI may cause job losses before new jobs appear.
- Beige Book: Economic activity largely unchanged; labour demand muted; consumer spending soft; EV sales strong ahead of tax-credit expiry.
- Bessent (Treasury): Shutdown hurting economy by up to USD 15bn/week; investment boom “sustainable”; QE should be used “sparingly, like antibiotics.”
- Fed tone: Gradual easing still expected; growing concern about labour-market risks amid tariff uncertainty.
US Shutdown
- Senate expected to leave for the week without progress.
- OMB: Layoffs could exceed 10,000 workers; court temporarily blocked federal job cuts across 30 agencies.
Fixed Income & FX
- Bonds:
- UST 10yr gained on safe-haven demand.
- Bunds steady above 130.00; JGBs flattened on BoJ commentary.
- DXY: Lower after Trump’s trade comments; USD pressured by dovish Fed rhetoric.
- EUR/USD: Higher on Eurozone industrial output beat and stronger ECB sentiment.
- GBP/USD: Above 1.34 after Reeves hinted at tax rises for the wealthy but ruled out austerity.
- USD/JPY: Lower near 151.00 after BoJ’s Tamura advocated rates closer to neutral.
- AUD/USD: Weaker after soft jobs data (Unemployment 4.5%).
Commodities
- Oil: Slightly firmer as Trump said India will cut Russian oil imports; upside capped by US inventory builds and IEA’s forecast of a 4mbpd surplus in 2026.
- API: Crude +7.4mln bbls, Gasoline +3.0mln, Distillates –4.8mln.
- Gold: Extended record run above $4,200/oz, supported by Fed cut expectations and softer USD.
- Copper: Flat amid lingering trade friction.
Geopolitics
- Middle East:
- Trump said Israel could resume Gaza operations “at any time” if Hamas breaches ceasefire.
- Hamas says it has handed over all recoverable hostages/bodies; Red Cross confirmed additional remains.
- US coordinating Gaza stabilisation force with multiple countries.
- Russia-Ukraine:
- Trump: Ukraine “wants to go on the offensive.”
- Zelensky to meet Trump Friday to discuss Tomahawk missiles; EU funding special tribunal for Russian aggression.
- Venezuela: Trump confirmed CIA operations, prompting Caracas condemnation for “violating sovereignty.”


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.

S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.