



Forex Friday: Dollar Bulls, Pound Bears Exhausted
In this week’s edition, we discuss the dollar and its impressive rally, and ponder over the pounded pound
Share this:
Welcome to Forex Friday, a weekly report in which we discuss selected currency themes mainly from a macro viewpoint, but we also throw in a pinch of technical analysis here and there. In this week’s edition, we discuss the dollar and its impressive rally, and ponder over the pounded pound, ahead of key central bank meetings from both sides of the pond next week.
Dollar: King of FX
The Dollar Index broke above the 2020 high this week, with the greenback rising against all major currencies, before easing back somewhat so far in Friday’s session amid profit-taking and bargain hunting of downbeat foreign currencies. The King of FX has been doing exceptionally well against currencies where the central bank is still relatively more dovish, such as the yen, yuan, euro and franc. Traders are convinced the FOMC will raise rates by 50 basis points next Wednesday and signal more aggressive hikes in the months ahead due to soaring inflationary pressures. Against the fundamental backdrop, it is hard to bet against the greenback. However, the dollar’s rally looks a bit overdone against some of the slightly more stronger currencies like the CAD. I also think the GBP/USD may have fallen too far by dipping below the 1.25 handle this week. See below for more on the cable.
But could the Fed trigger a sell-off in the dollar?
Well, the dollar’s aggressive rally in recent weeks suggests the market has been pricing in the Fed’s projected hikes and quantitative tightening. Having talked it up so much, the key risk would be if the FOMC decides to hike by 25 basis points instead of 50 on Wednesday. This would catch everyone guard, as it 50 bps is precisely what the market is pricing in, judging by the CME’s useful FedWatch tool:
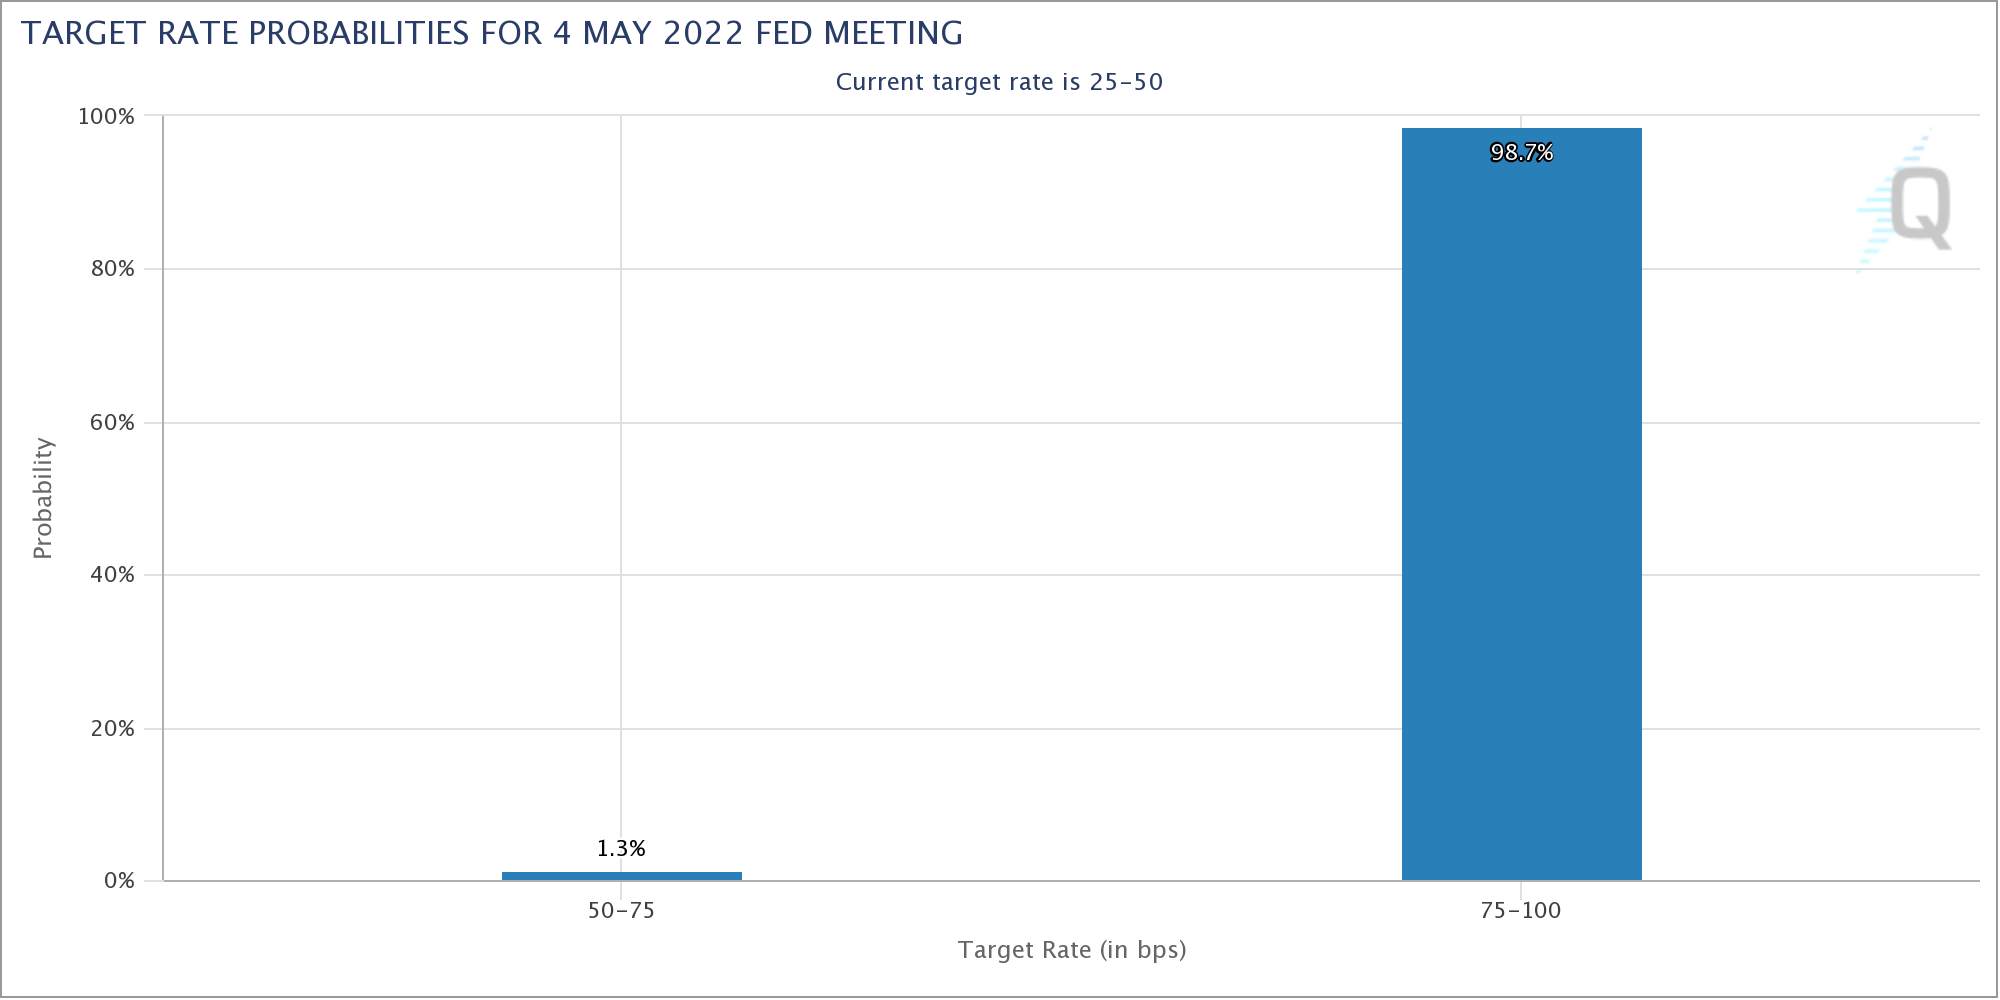
Meanwhile, the Fed’s preferred measure of inflation will be published later on Friday: Core PCE Price Index is seen rising another 0.3% or 5.3% year-over-year. It is unlikely that this, the surprise negative GDP print we saw on Thursday, or any other macro pointers that will be released from now until Wednesday will have any impact on the Fed’s decision to hike by 50 bps.
GBP/USD finds dip buyers at 1.25
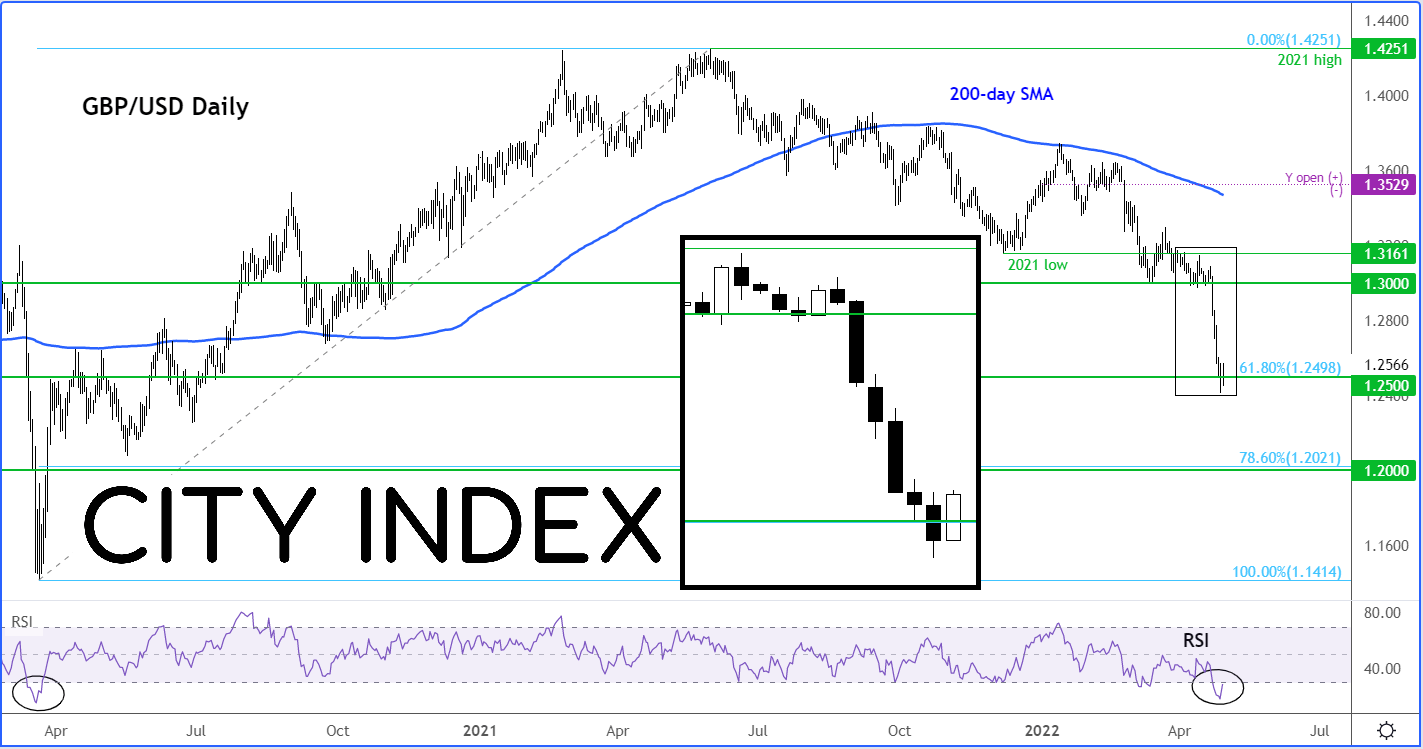
The GBP/USD has had a very rough couple of weeks as it slumped more than 600 pips from above 1.30 to below 1.25 on the back of expectations that tightening from the Federal Reserve and Bank of England will diverge with the former seen becoming more aggressive than the latter. But I reckon the worst of the selling is over and there is a good possibility for a decent rebound as we look ahead to a busy week of central bank action next week with both the Fed and BoE set to tighten their respective policies.
Now the Bank of England has already raised rates three times and a fourth increase is almost certain. The uncertainty lies about the pace of tightening: will it be 25 or 50 basis points on Thursday? Governor Bailey recently implicitly implied it will be 25 bps, as the Bank is walking a ‘narrow path’ between growth and inflation. But unlike some of the other central banks, like the Bank of Japan or Swiss National Bank, the BoE is tightening its belt. This should therefore keep the downside limited for the cable.
We like a bit of technical analysis and the psychological importance of the 1.25 handle cannot be ignored, which helps explain why we have seen some short-side profit taking here and long-side bargain hunting. It is even more interesting when you consider that the 61.8% Fibonacci retracement level also converges around 1.2500. Could we see a bounce back to 1.2700 from here? If the BoE is more hawkish in the week ahead, I wouldn’t rule out a revisit of 1.3000.
Welcome to Forex Friday, a weekly report in which we discuss selected currency themes mainly from a macro viewpoint, but we also throw in a pinch of technical analysis here and there. In this week’s edition, we discuss the dollar and its impressive rally, and ponder over the pounded pound, ahead of key central bank meetings from both sides of the pond next week.
Dollar: King of FX
The Dollar Index broke above the 2020 high this week, with the greenback rising against all major currencies, before easing back somewhat so far in Friday’s session amid profit-taking and bargain hunting of downbeat foreign currencies. The King of FX has been doing exceptionally well against currencies where the central bank is still relatively more dovish, such as the yen, yuan, euro and franc. Traders are convinced the FOMC will raise rates by 50 basis points next Wednesday and signal more aggressive hikes in the months ahead due to soaring inflationary pressures. Against the fundamental backdrop, it is hard to bet against the greenback. However, the dollar’s rally looks a bit overdone against some of the slightly more stronger currencies like the CAD. I also think the GBP/USD may have fallen too far by dipping below the 1.25 handle this week. See below for more on the cable.
But could the Fed trigger a sell-off in the dollar?
Well, the dollar’s aggressive rally in recent weeks suggests the market has been pricing in the Fed’s projected hikes and quantitative tightening. Having talked it up so much, the key risk would be if the FOMC decides to hike by 25 basis points instead of 50 on Wednesday. This would catch everyone guard, as it 50 bps is precisely what the market is pricing in, judging by the CME’s useful FedWatch tool:
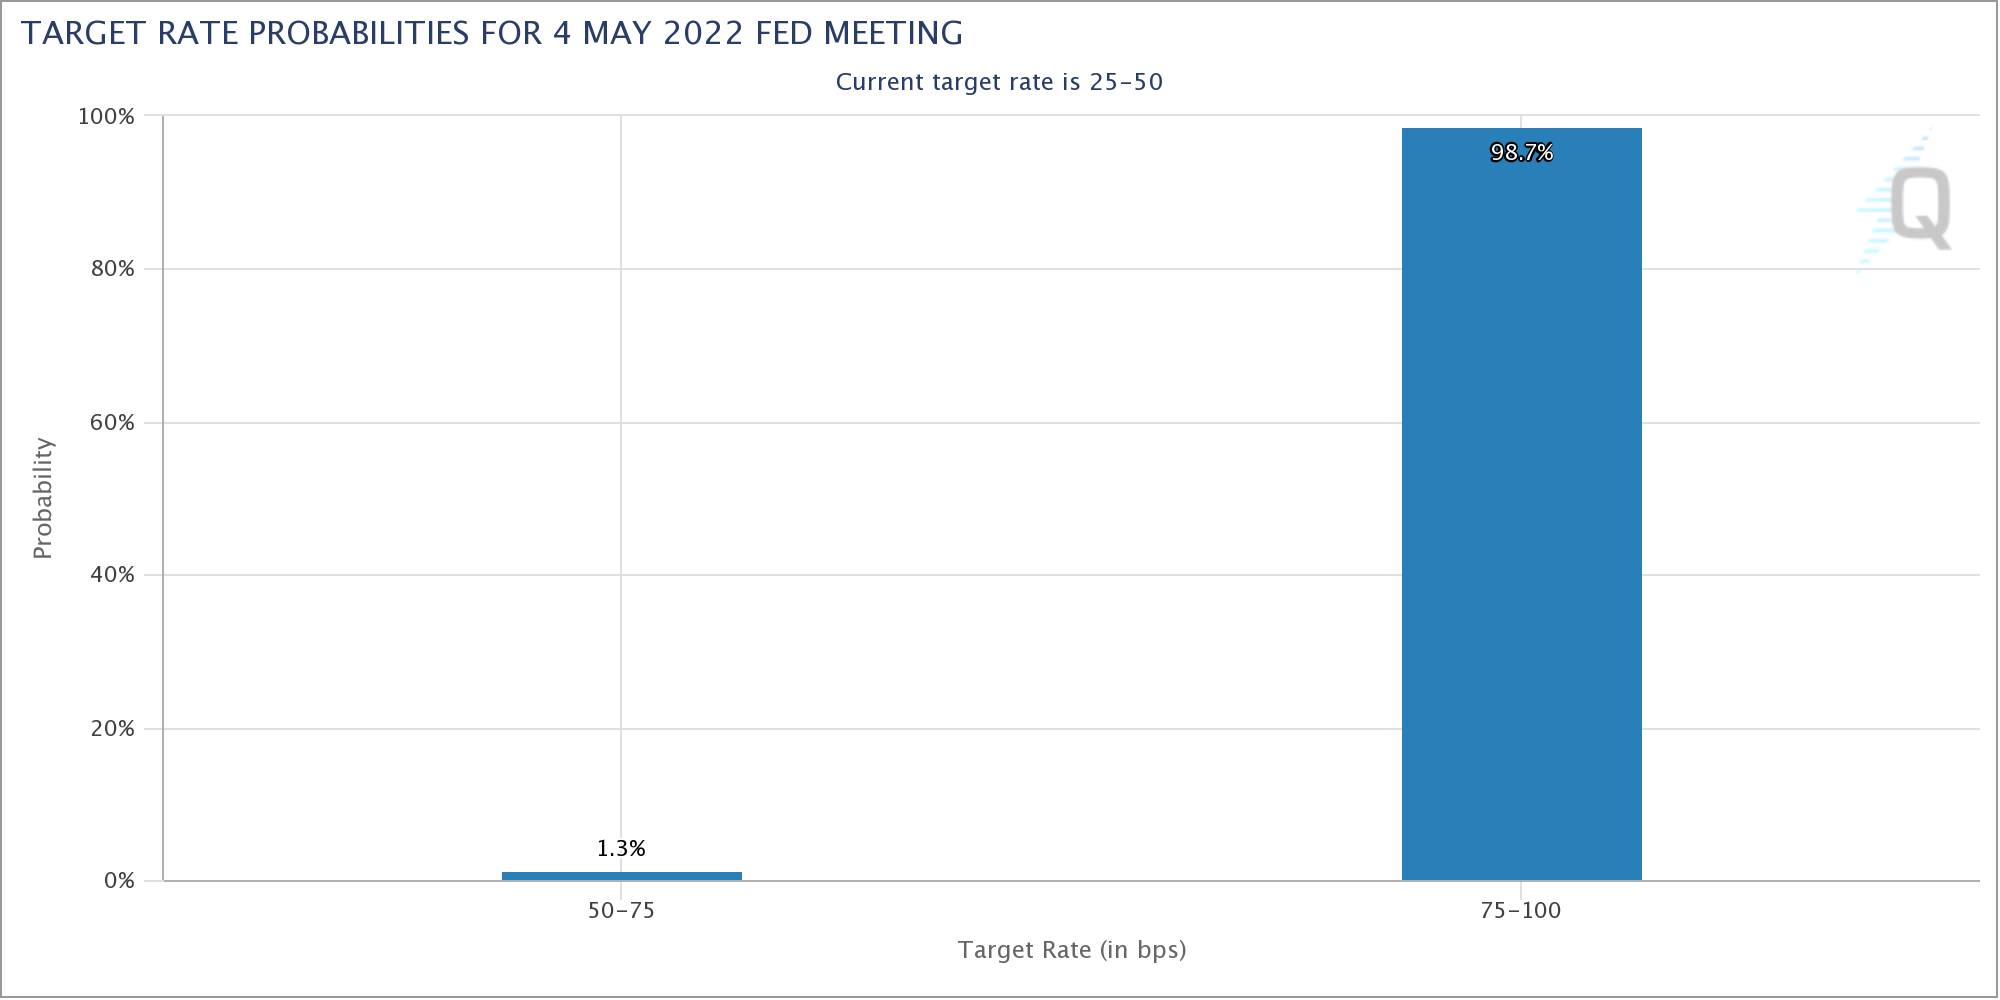
Meanwhile, the Fed’s preferred measure of inflation will be published later on Friday: Core PCE Price Index is seen rising another 0.3% or 5.3% year-over-year. It is unlikely that this, the surprise negative GDP print we saw on Thursday, or any other macro pointers that will be released from now until Wednesday will have any impact on the Fed’s decision to hike by 50 bps.
GBP/USD finds dip buyers at 1.25
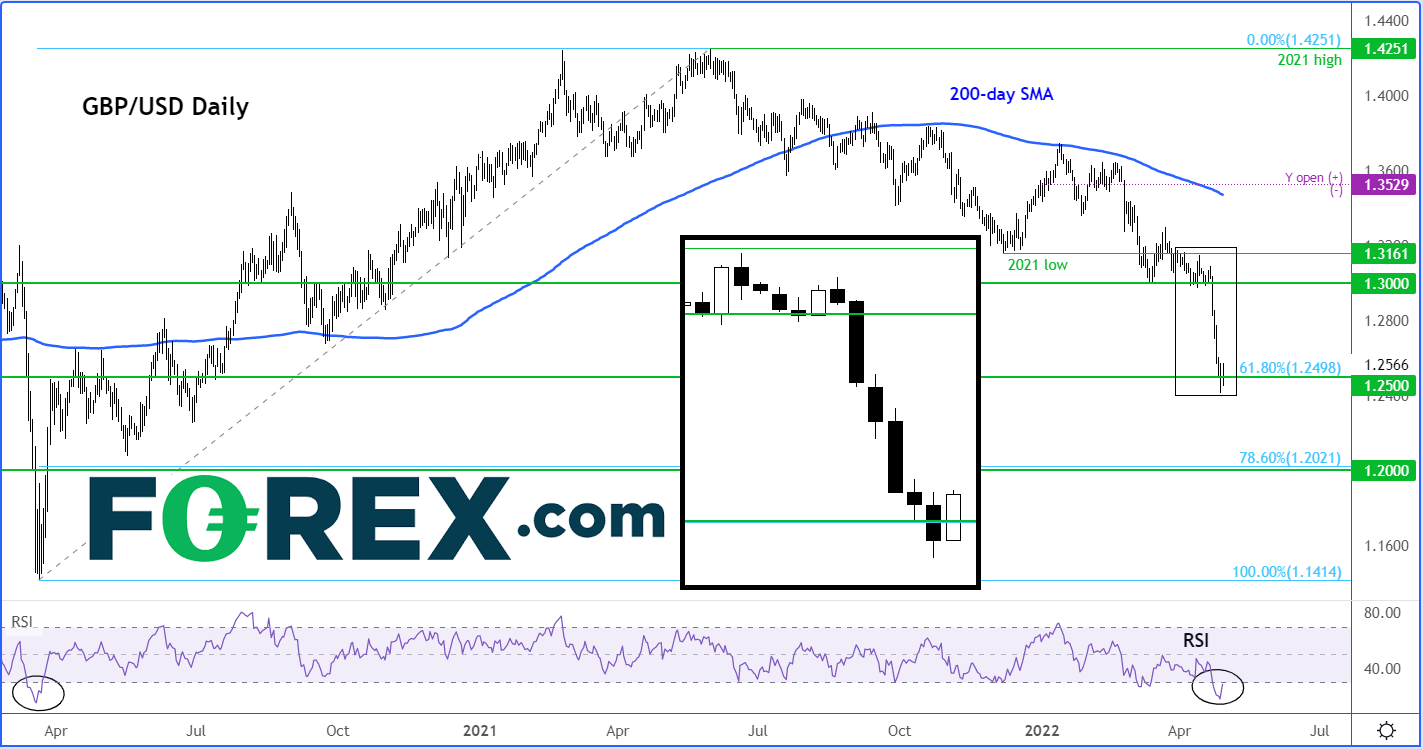
The GBP/USD has had a very rough couple of weeks as it slumped more than 600 pips from above 1.30 to below 1.25 on the back of expectations that tightening from the Federal Reserve and Bank of England will diverge with the former seen becoming more aggressive than the latter. But I reckon the worst of the selling is over and there is a good possibility for a decent rebound as we look ahead to a busy week of central bank action next week with both the Fed and BoE set to tighten their respective policies.
Now the Bank of England has already raised rates three times and a fourth increase is almost certain. The uncertainty lies about the pace of tightening: will it be 25 or 50 basis points on Thursday? Governor Bailey recently implicitly implied it will be 25 bps, as the Bank is walking a ‘narrow path’ between growth and inflation. But unlike some of the other central banks, like the Bank of Japan or Swiss National Bank, the BoE is tightening its belt. This should therefore keep the downside limited for the cable.
We like a bit of technical analysis and the psychological importance of the 1.25 handle cannot be ignored, which helps explain why we have seen some short-side profit taking here and long-side bargain hunting. It is even more interesting when you consider that the 61.8% Fibonacci retracement level also converges around 1.2500. Could we see a bounce back to 1.2700 from here? If the BoE is more hawkish in the week ahead, I wouldn’t rule out a revisit of 1.3000.
Source: StoneX and TradingView.com
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.