



FTSE 100, Oil Forecast: Two trades to watch
FTSE falls as HSBC drags index after earnings miss. Oil remains elevated as US-Iran hostilities rise.
Share this:


FTSE falls as HSBC drags index after earnings miss
The FTSE 100 fell on Tuesday, its first session after the long weekend, underperforming European peers as weakness in HSBC weighed on the index.
HSBC shares dropped around 5% after first-quarter profits missed expectations, hit by an unexpected fraud-related charge in the UK and rising credit provisions linked to growing economic risks from the Middle East conflict.
The bank reported pre-tax profit of $9.4 billion, below forecasts of $9.6 billion. While performance in wealth management and Hong Kong remained resilient and the bank upgraded its net interest income outlook, results were overshadowed by a $1.3 billion expected credit loss. This included a $400 million fraud-related charge and a further $300 million increase in allowances tied to the deteriorating global economic outlook.
The escalation in geopolitical tensions is particularly significant for HSBC, which has focused on Asia and the Middle East as key growth regions. The conflict now risks undermining those expansion plans, raising uncertainty over future earnings.
HSBC has also been undergoing a major restructuring over the past 18 months aimed at simplifying the business and reducing costs. While this strategy helped lift shares to record highs earlier this year, the outbreak of the US–Iran conflict has since put the stock under pressure.
Beyond banks, miners also weighed on the FTSE, while oil majors such as BP and Shell gained on higher crude prices. However, strength in energy stocks was not enough to offset broader weakness in the index.
Macro backdrop – Politics and rates in focus
Political uncertainty is also building. Speculation around Keir Starmer’s leadership is being reflected more clearly in sterling than in equities, although it remains a broader risk factor.
Meanwhile, UK gilt yields are rising sharply after markets reopened, driven by inflation concerns linked to higher oil prices. Traders are increasingly pricing in the possibility of further rate hikes from the Bank of England.
With the UK economic calendar relatively quiet this week, attention will turn to corporate earnings and upcoming elections.
FTSE forecast – technical analysis
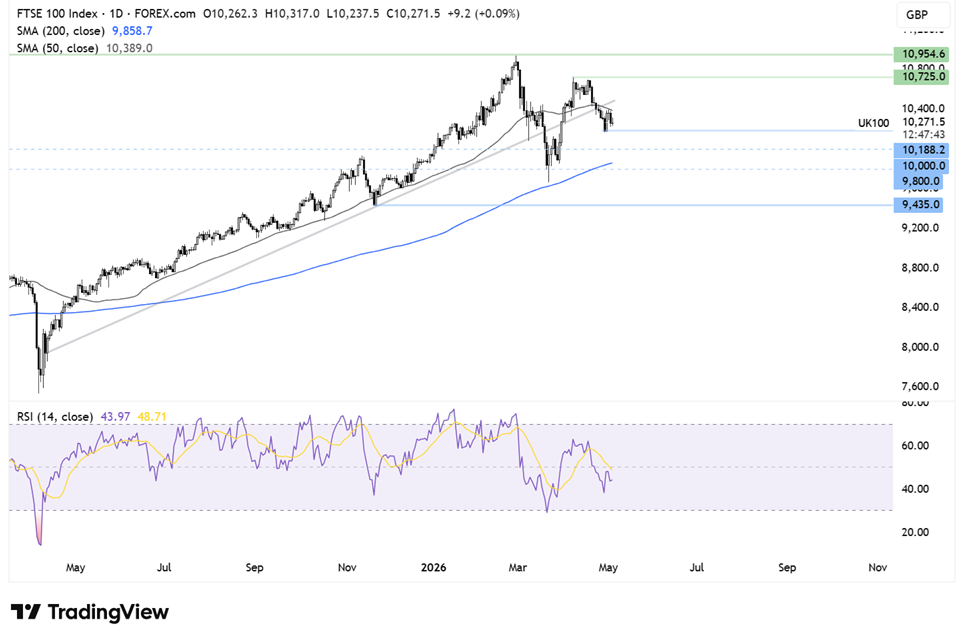
After running into resistance at 10,725, and forming a lower high, the FTSE rebounded lower, falling below the multi-month rising trendline and the 50 SMA to 10,200. Rejection at the 50 SMA again, combined with RSI below 50, keeps sellers hopeful of further downside.
Sellers will look to take out support at 10,200 to extend losses towards 10,000, the psychological level. A break below here exposes the 200 SMA at 9866. Below here, sellers could gain traction towards 9800 and 9667, the 2026 low.
On the upside, resistance is seen at the 50 SMA at 10,400. And the rising trendline resistance at 10,500. Above here, 10,725 comes into focus. A rise above here creates a higher high.
Oil remains elevated as US-Iran hostilities rise
Oil prices are easing on Tuesday but remain elevated near 105 per barrel after rallying nearly 6% in the previous session.
Concerns over the fragile Middle East ceasefire have resurfaced after the US and Iran traded blows over the Strait of Hormuz and amid ongoing disruption to shipping through the waterway. Efforts to restore safe passage by President Trump have failed and the outlook remains uncertain, with risks of further escalation.
The UAE has also confirmed a strike on the Fujairah oil hub, threatening around 1.9 million barrels per day of supply.
The latest developments underscore the ongoing risk of supply disruption. While global inventories are not yet critically low, analysts at Goldman Sachs note that the pace of drawdowns is becoming increasingly concerning. Refined product inventories—particularly jet fuel—are tightening ahead of the peak summer travel season in the Northern Hemisphere.
Oil forecast - technical analysis
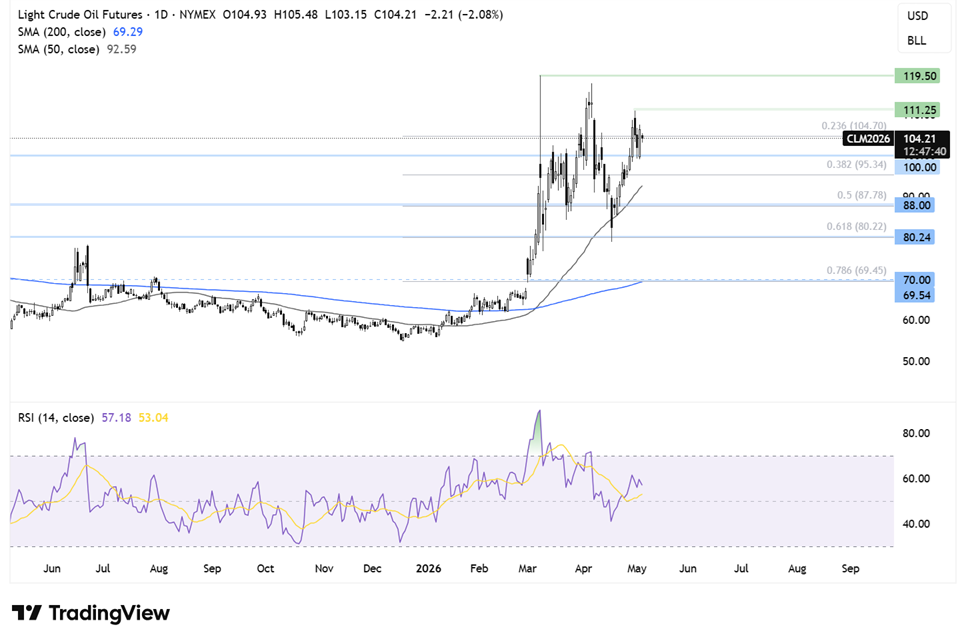
Oil recovered from the 79.00 low, pushing above the 50 SMA and extending the recovery to 111.00 before easing back to 105.00, the 23.6% Fib retracement of the 55.00 low and 120.00 high as momentum slows.
Should momentum pick up, buyers will look to rise above 111.00, bringing 120 back into focus. A rose above here would be a bullish breakout.
A meaningful break below 105 opens the door to 100.00, yesterday’s low. Below here, 95.00 comes into play, the 38.2% Fib retracement ahead of the 50 SMA at 93.00.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

DAX Weakens as Tech and Defence Stocks Come Under Pressure
European equities are under pressure as the global technology selloff extends into a second session. Concerns about AI-related capital expenditure, semiconductor demand and regulatory risks are weighing heavily on technology stocks, while rising oil prices add another layer of uncertainty. With the US jobs report due later today, investors are reassessing valuations, growth expectations and the outlook for interest rates.

Crude Oil, DXY Outlook: Geopolitical Risks Halt Sell-Offs in the Dollar and Oil
The U.S. Dollar Index, Brent and WTI are rebounding from key support levels and oversold conditions after steep sell-offs. U.S.–Iran tensions, inflation risks and rate expectations remain in focus.

dax-record-high-banks-cyclicals-election-relief-rally-european-stocks
The DAX has surged to fresh record highs as investors continue to rotate into banks, industrials and cyclical stocks following the US midterm elections. Falling bond yields, lower oil prices and improving sentiment have supported risk appetite across Europe, helping the index move decisively above 26,000. The focus now shifts from political relief to whether earnings and macroeconomic data can justify the rally's next leg higher.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.