




FX Brief Tight Ranges Ahead Of Key Data
A summary of news and snapshot of moves from today’s Asia session.
Share this:

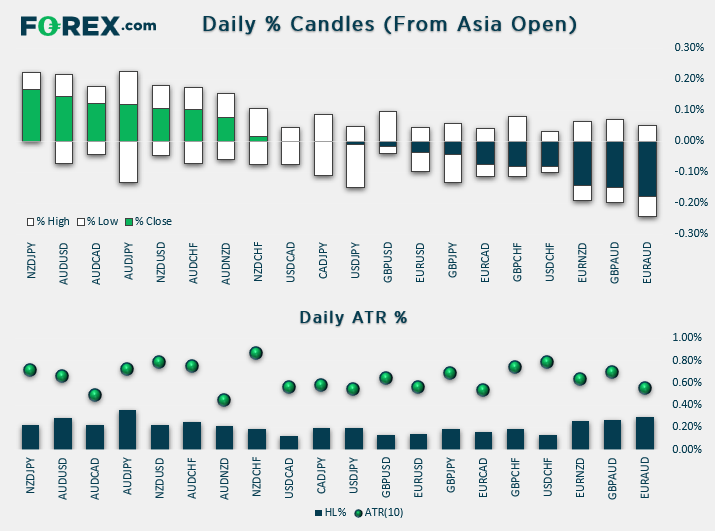
- Very minor ranges across FX markets so far, as traders eagerly await RBA’s meeting up at half past the hour.
- Index futures are slightly higher, gold remains near yesterday’s lows and beneath $1,390 after its most bearish day in a year.
- On trade, the US government turned their attention to Europe and threatened tariffs of a $4bn on European goods. Trump also said any trade deal with China would have to be tilted towards the US side.
- China’s Premier Li Keqiang pledged to lower rates and use RRR cut to help smaller businesses, and ‘not resort to currency devaluation’.
- NZ business confidence plunged to its most pessimistic level since March 2009. 34% of businesses expect conditions to deteriorate, compared with 29% last quarter. Building consents jumped +13.2% in May.
Up Next:
- RBA are expected to cut rates in just under 30 minutes. Although if recent history is anything to go by, we may need to wait for Philip Lowe to deliver the dovish message when he speaks later today.
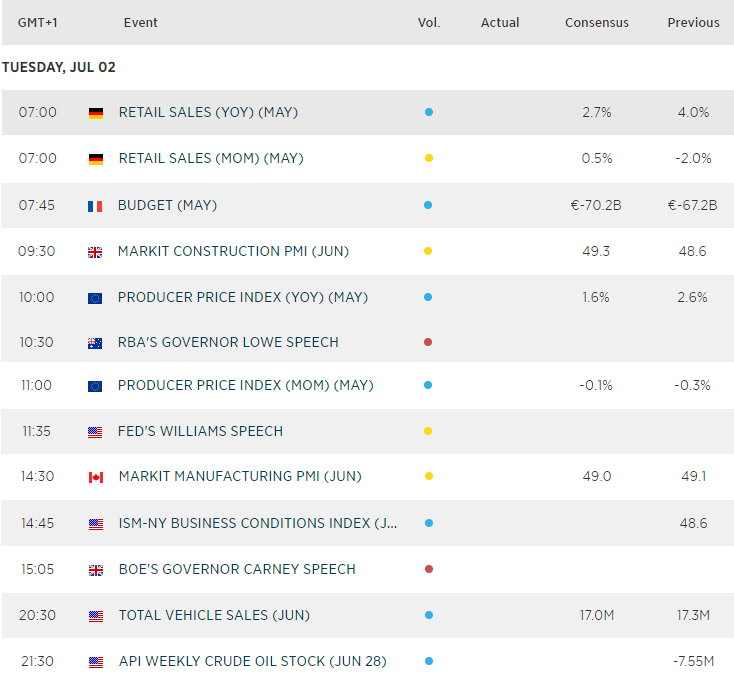
- EU producer prices are expected to soften to 14-month low, potentially adding further fuel to the dovish (Euro bearish) fire.
- Global PMI has largely disappointed this week, so concerns of softer global growth are resurfacing despite the positive sentiment form the G20. UK construction PMI is polled to contract at a weaker pace – but given the weak lead from elsewhere and the fact it contracted at its fastest pace since November 2012, we have low hopes for a turnaround.
Related analysis:
RBA Preview: AUD/USD Holds Above 70c Ahead Of Expected Rate Cut
Featured Trade: Bullish exhaustion seen in AUDJPY ahead of RBA
- Very minor ranges across FX markets so far, as traders eagerly await RBA’s meeting up at half past the hour.
- Index futures are slightly higher, gold remains near yesterday’s lows and beneath $1,390 after its most bearish day in a year.
- On trade, the US government turned their attention to Europe and threatened tariffs of a $4bn on European goods. Trump also said any trade deal with China would have to be tilted towards the US side.
- China’s Premier Li Keqiang pledged to lower rates and use RRR cut to help smaller businesses, and ‘not resort to currency devaluation’.
- NZ business confidence plunged to its most pessimistic level since March 2009. 34% of businesses expect conditions to deteriorate, compared with 29% last quarter. Building consents jumped +13.2% in May.
Up Next:
- RBA are expected to cut rates in just under 30 minutes. Although if recent history is anything to go by, we may need to wait for Philip Lowe to deliver the dovish message when he speaks later today.
- EU producer prices are expected to soften to 14-month low, potentially adding further fuel to the dovish (Euro bearish) fire.
- Global PMI has largely disappointed this week, so concerns of softer global growth are resurfacing despite the positive sentiment form the G20. UK construction PMI is polled to contract at a weaker pace – but given the weak lead from elsewhere and the fact it contracted at its fastest pace since November 2012, we have low hopes for a turnaround.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.