



Gold rises on US ratings downgrade: Asian Open – 2nd August 2023
The US has lost its triple AAA ratings status according to Fitch Ratings agency, which saw S&P 500 E-mini futures fall around -0.6% at the open and spot gold rise around 0.6% from its cycle lows. We now have a bullish bias for gold over the near-term, although the success of its anticipated move to 1960 likely depends on the performance of the US dollar and how seriously traders take the downgrade to be.
Share this:
Market Summary:
- Fitch Ratings agency downgraded the US long term ratings outlook to AA+ (from AAA) to reflect “expected fiscal deterioration over the next three years, a high and growing general government debt burden, and the erosion of governance…” according to the announcement on their website
- S&P 500 E-mini futures fell around -0.6% at the open (which is a bit of a ‘meh’ response in the grand scheme of things) and Treasury Secretary Janet Yellen called the downgrade ‘arbitrary’ and ‘outdated’
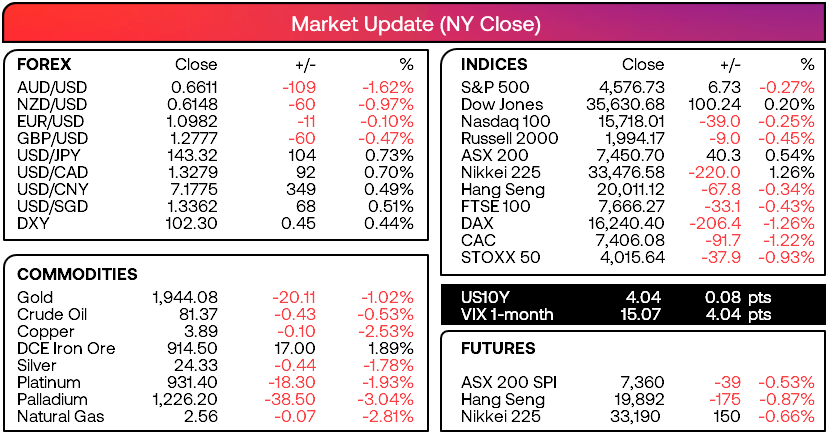
- Still, it weighed on the US dollar and sent gold 0.4% higher as it sucked in safe-haven flows early in the Asian session
- The US dollar continued to advance as US job openings fell to a 26-month low, to serve as a timely reminder of just how tight the US labour market remains
- However, the US manufacturing sector continued to shrink although at a slightly slower pace with the ISM survey falling to 46.4 (below 50 denotes contraction). Prices paid – a rough measure of inflationary pressure within the sector – also contracted at 42.6
- The RBA held their cash rate at 4.1% for a second month, and many are now speculating that it could be their peak rate. The focus now shifts to Friday’s SOMP (Statement on Monetary Policy) to see if any significant revisions are made to their quarterly forecasts
- The stronger US dollar and dovish RBA meeting sent AUD/USD down to 66c, which is a major line of defence for Aussie bulls over the near term. We noted in yesterday’s report that AUD/USD shares a strongly inverted 20 -day correlation with DXY (US dollar index), so perhaps it can break support if DXY keeps advancing
- China’s manufacturing sector contracted faster than expected in July according to a privately run PMI survey by Caixin
- Australian building approvals fell -7.7% in June. Yet building approvals is a volatile number at the best of times, so whilst it fell -7.7% m/m in June – the growth has simply slowed relative to May’s 20.6% surge.
Events in focus (AEDT):
- 09:00 – Australia’s construction and manufacturing index (AIG)
- 09:50 – Japan’s monetary policy meeting minutes, retail sales, monetary base y/y
- 11:30 – The RBA’s chart pack for Australia
ASX 200 at a glance:
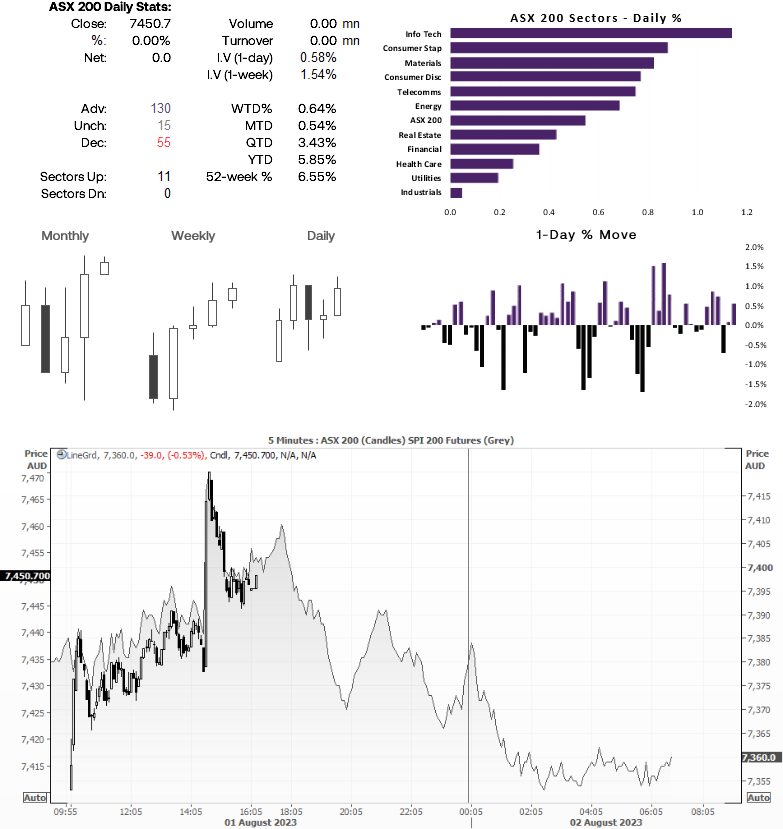
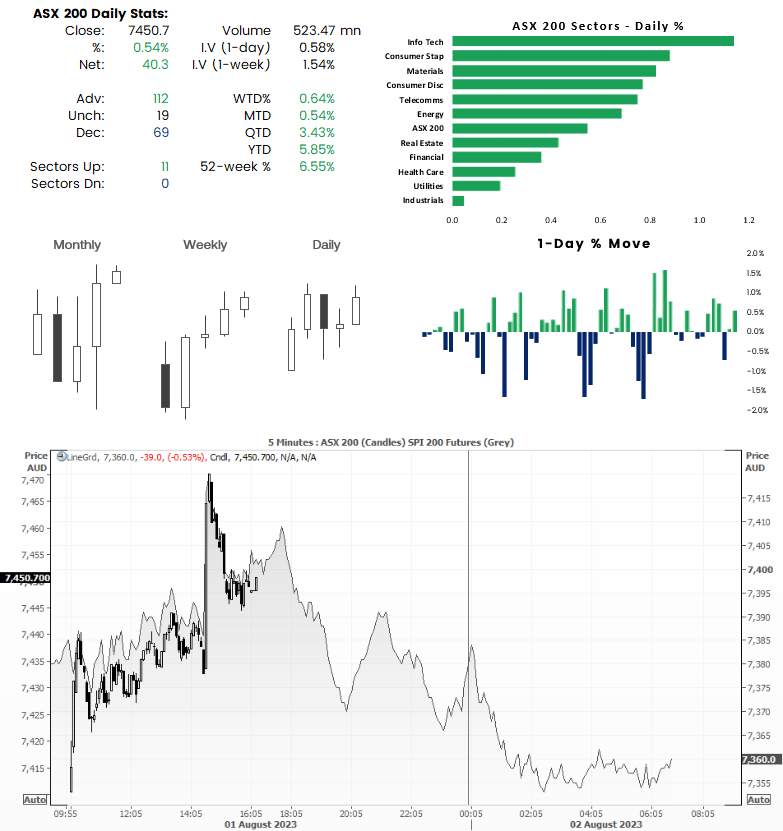
- The ASX 200 closed to a 2-day high after the dovish RBA meeting
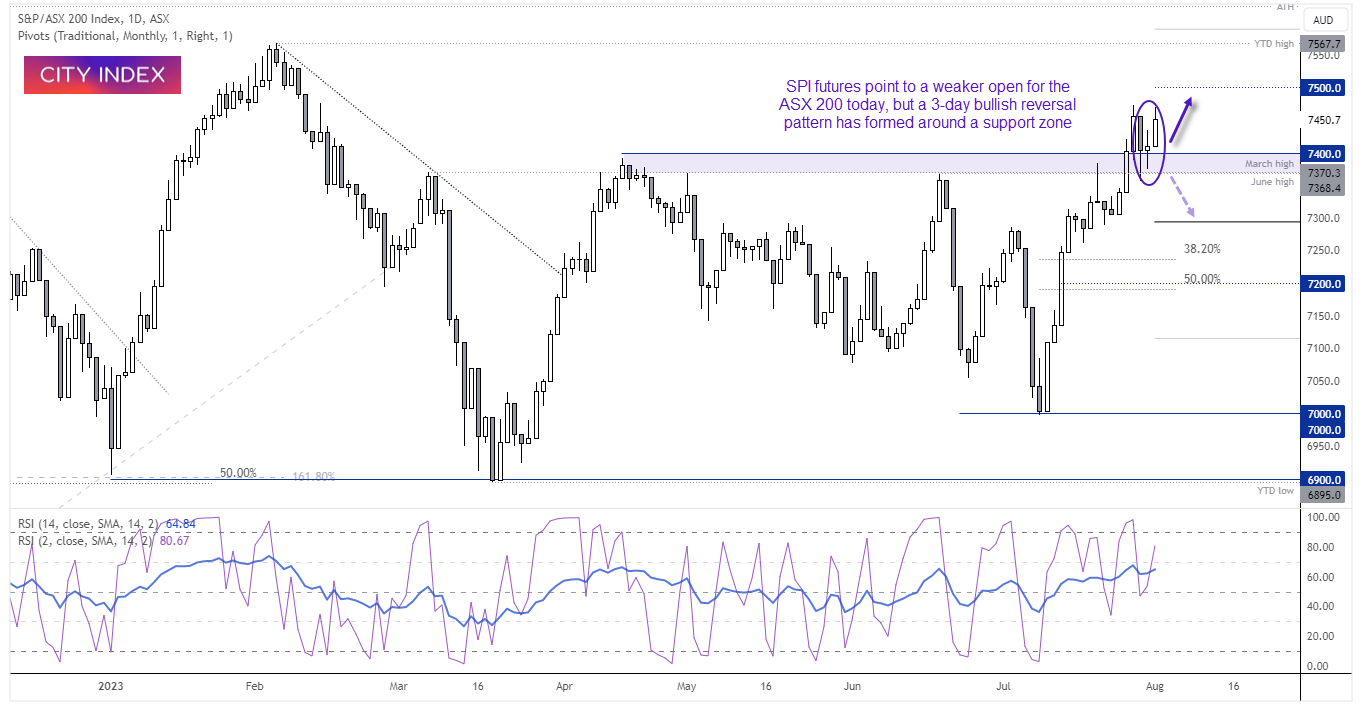
- It also formed a 3-day bullish reversal pattern (morning star reversal) around the 7370 – 7400 support zone
- SPI futures point to a weak open, and Emini futures also suggest some stress may come from the US downgrade
- Today, we want to see if the ASX can build another base above the 7370 – 7400 support zone for a potential long towards 7500
- If it holds above 7400, it suggests the fallout from the US downgrade is less significant
- A break below 7370 assumes a move back towards 7300
Gold 1-hour chart:
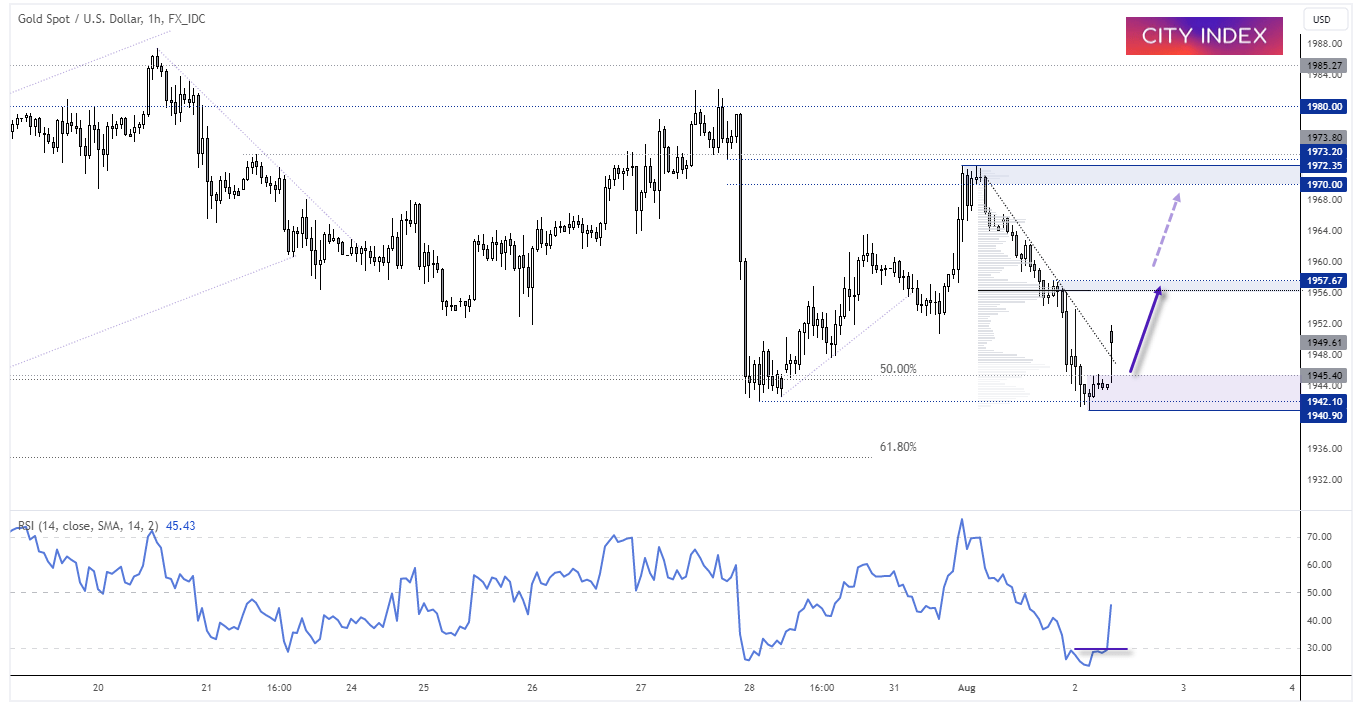
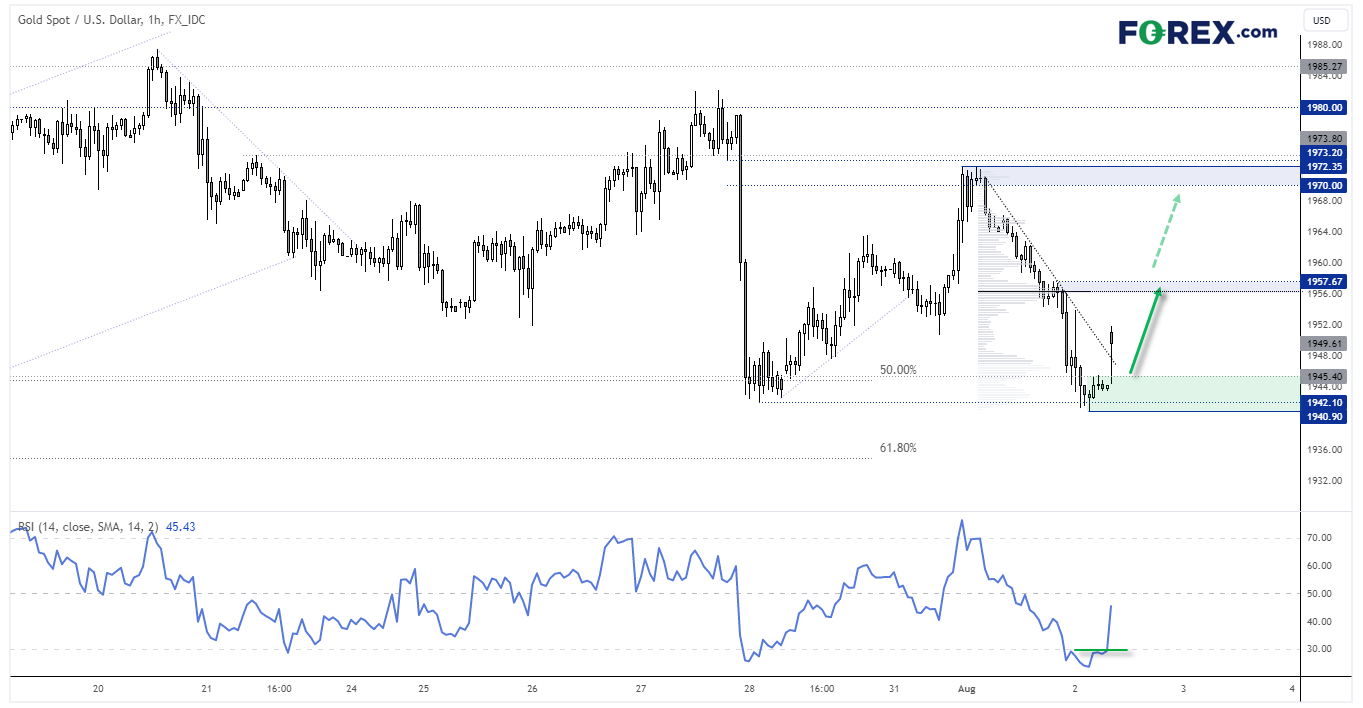
Whilst gold prices breached last week’s low and formed a bearish engulfing day, news of the US ratings downgrade has seen gold prices gap higher just after the futures open. They also gapped above trend resistance but are now trying to fill that gap, and RSI (14) has moved out of oversold to suggest a cycle low has formed. From here, we think it has the potential to move towards 1960 / the volume node around 1957, a break above which brings the cycle high around 1970 back into focus. And it success likely depends on the performance of the US and how seriously markets deem the ratings downgrade to be. A break below 1940 invalidates the near-term bullish bias.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Canadian Dollar Short-term Outlook: USD/CAD Plunge Stalls at Pivotal Support—Range Break in Focus 11 5 2026
Friday’s U.S. and Canadian employment reports could trigger a decisive USD/CAD move as bulls and bears battle for control at critical support.

US Dollar Technical Outlook: DXY Bulls Fight to Hold Critical Support Ahead of NFP 11 5 2026
DXY bulls are attempting to defend a pivotal technical threshold, with the next reaction likely to determine whether the broader recovery survives.
Nasdaq 100 forecast: Tech stocks remain under pressure despite mid terms rally
The Democratic sweep in the US midterms delivered the negative dollar reaction I had anticipated, but that upsurge in stocks was not something I or many others had anticipated. Fears that a Democrat-controlled Congress would trigger a broader sell-off in technology stocks proved premature. Nevertheless, the sector remains under pressure. The political outcome may help explain the Nasdaq’s relative underperformance with futures falling 0.8% today. Sharp falls in shares of Arm and Qualcomm following their results are certainly not helping. While the removal of midterm uncertainty provided a broad-based boost to risk appetite yesterday, investors may be starting to price in the prospect of tighter regulatory scrutiny of Big Tech, particularly around AI, under greater Democratic influence in Congress. This could become a headwind for technology valuations, even if the immediate impact on corporate earnings remains unclear.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.