



Hang Seng Tech Trades Higher, Iron Ore Rallies on Stimulus Optimism
China’s inflation data boosted hopes of further stimulus, while optimism for Fed rate cuts lifted risk appetite, sending Hang Seng Tech and iron ore higher on Wednesday.
Share this:
- China’s weak CPI and easing PPI raise chances of further stimulus
- Optimism for Fed rate cuts lifts risk appetite
- Hang Seng Tech, and iron ore rebound on Wednesday
Summary
China’s latest inflation figures increase the likelihood of further consumer-targeted stimulus, with weak demand still evident beneath the headline numbers. Combined with hopes for additional Fed rate cuts, the data helped Chinese markets rebound on Wednesday.
Mixed Messages from China’s Inflation Update
China’s deflationary pressures deepened in August with consumer prices falling at their fastest pace in six months. Headline CPI dropped 0.4% on year, sharper than the 0.2% decline economists expected, and down from flat in July. The drag came from food, where prices slumped 4.3%, while non-food prices rose a modest 0.5%. Core CPI edged up 1.2% from a year earlier, supported by government incentives such as the consumer goods trade-in scheme, though the improvement looks policy-driven rather than demand-led.
Producer prices also remained in negative territory, with PPI down 2.9% on year. That was an improvement from July’s 3.6% fall, reflecting Beijing’s efforts to restrict supply and curb excess capacity in sectors like coal and lithium. Even so, with PPI deflation now stretching towards three years, the narrowing pace owes more to supply management than stronger demand. As demonstrated by lithium markets which plunged on Wednesday on reports CATL plans to restart production at a giant mothballed mine, without a sustained pickup in domestic spending, neither consumer nor producer prices are likely to mount a lasting recovery.

Stimulus Hopes Boost Chinese Markets
The prospect of additional support measures helped lift Chinese assets, with the Hang Seng and Hang Seng Tech indices both rebounding sharply on Wednesday. Iron ore futures also firmed, supported by hopes that further stimulus could bolster demand in China’s struggling property sector.
Hang Seng Tech Trades at Fresh Highs
Source: TradingView
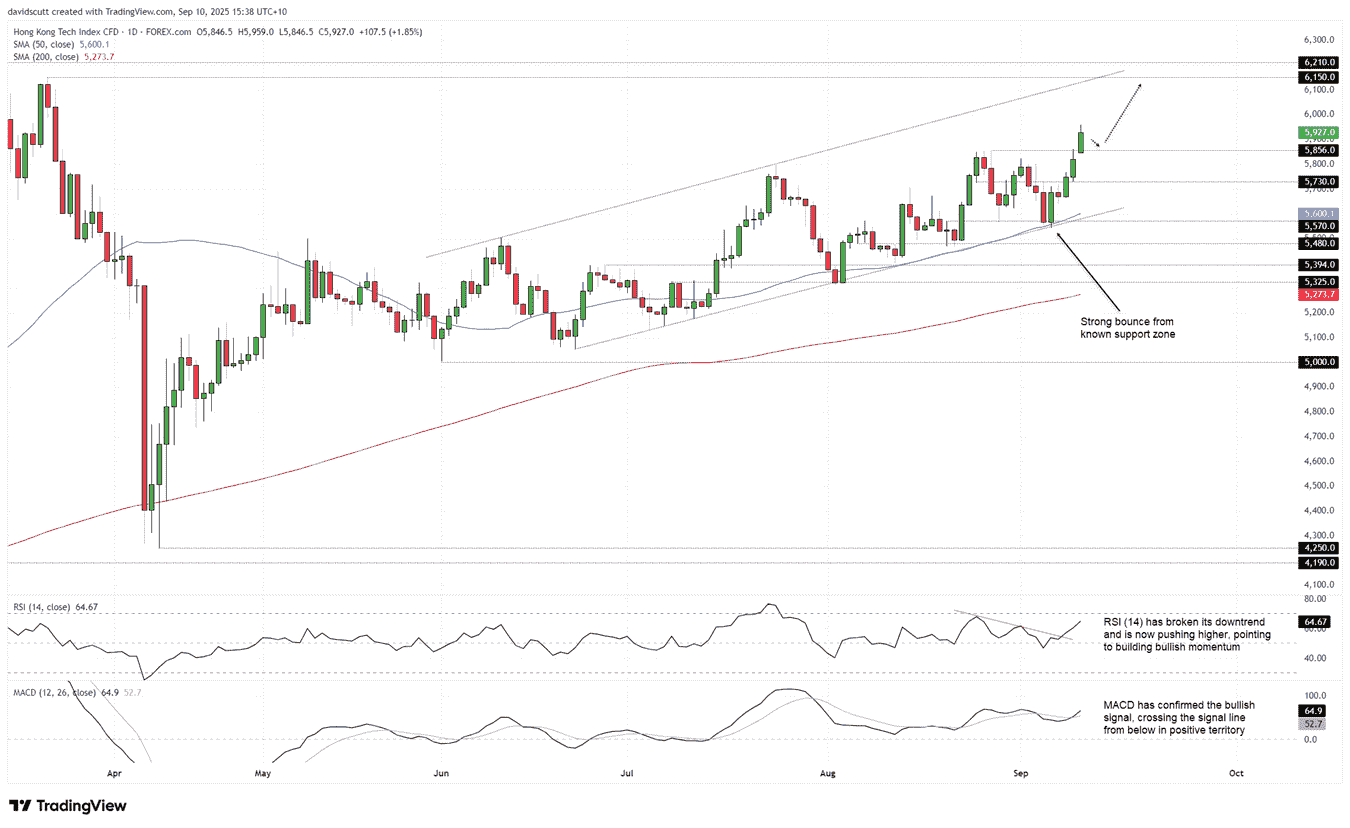
The Hang Seng Tech Index has rediscovered its mojo after bouncing strongly from a support zone consisting of the 50DMA and uptrend support last week, taking out minor resistance at 5730 before clearing the August high of 5856.
Those considering buying the break could look to enter above the August highs with a stop beneath for protection, targeting the intersection of horizontal and channel resistance at 6150.
Momentum indicators have turned bullish with RSI (14) breaking its downtrend before moving back above 50 while MACD has crossed the signal line from below in positive territory, bolstering the signal. That favours long setups over short in the near-term.
Iron Ore Breaks Out
Source: TradingView
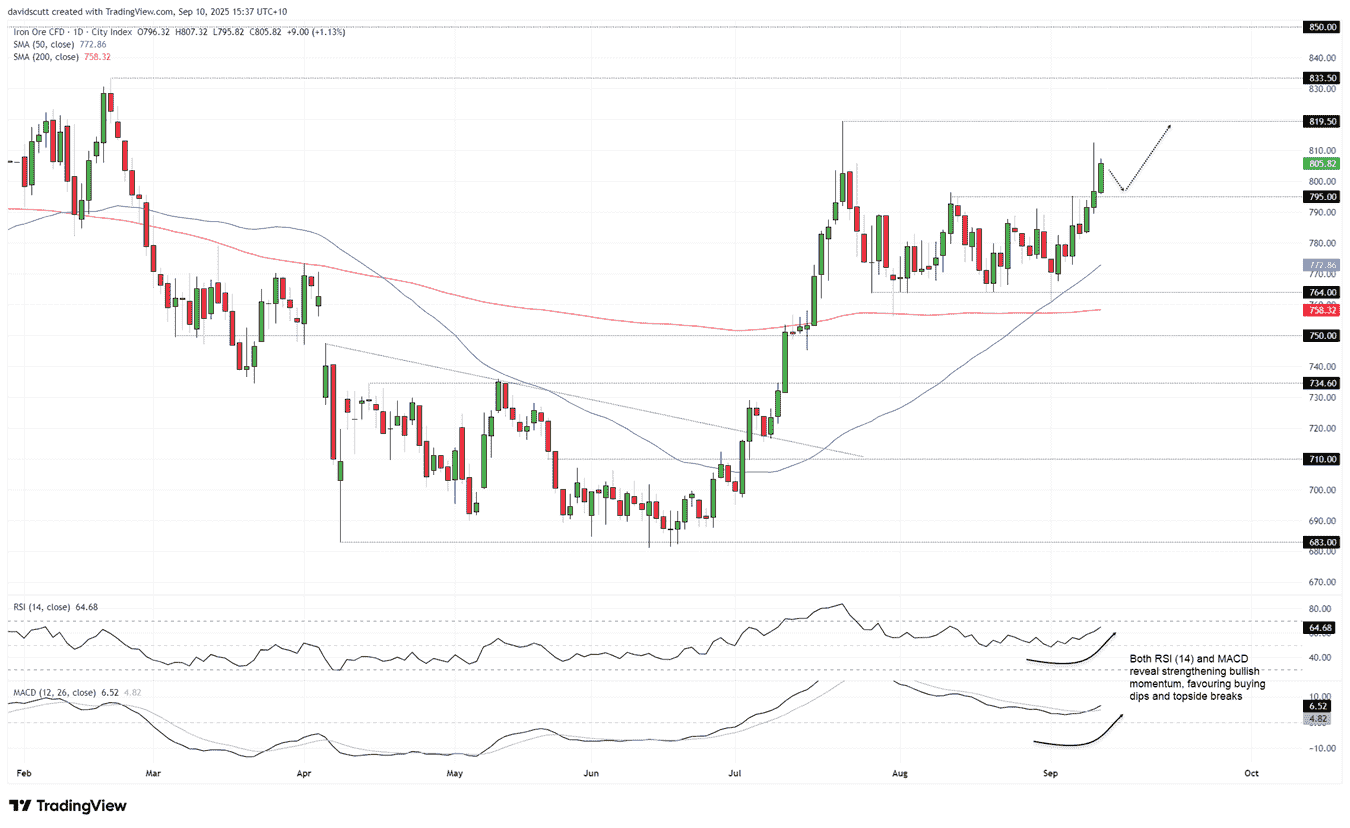
It’s not just tech stocks in China that are breaking higher with iron ore also up and about following a definitive move through resistance above ¥795. Given the shooting star candle that printed a day earlier, the preference would be to wait for a potential pullback towards ¥795 before considering long positions, allowing for time to assess whether it truly was a topping signal.
If the price retreats back towards the level but holds above, longs could be established with a stop below for protection, targeting the swing highs of ¥819.50 or ¥833.50 initially.
With RSI (14) and MACD providing strong bullish signals, buying dips and breakouts is favoured over selling rips.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.