


Iron Ore Outlook: Key Level Tested Amid Weak China Data
Price action around the 200DMA could dictate the next major move for iron ore as fundamentals turn sharply negative and technical signals lean bearish.
Share this:
- Chinese steel output slumps to a 21-month low
- Urban investment falls for first time since 2020
- Price repeatedly tested 200DMA without breaking
- Momentum signals favour downside
Summary
Chinese crude steel output cratered in September while fixed asset investment in urban areas declined for the first time since the pandemic, providing a troubling fundamental picture for iron ore demand. With the price now resting on a key technical level, movements in the short term could prove influential on the longer-term trajectory for prices.
Iron ore testing key 200DMA
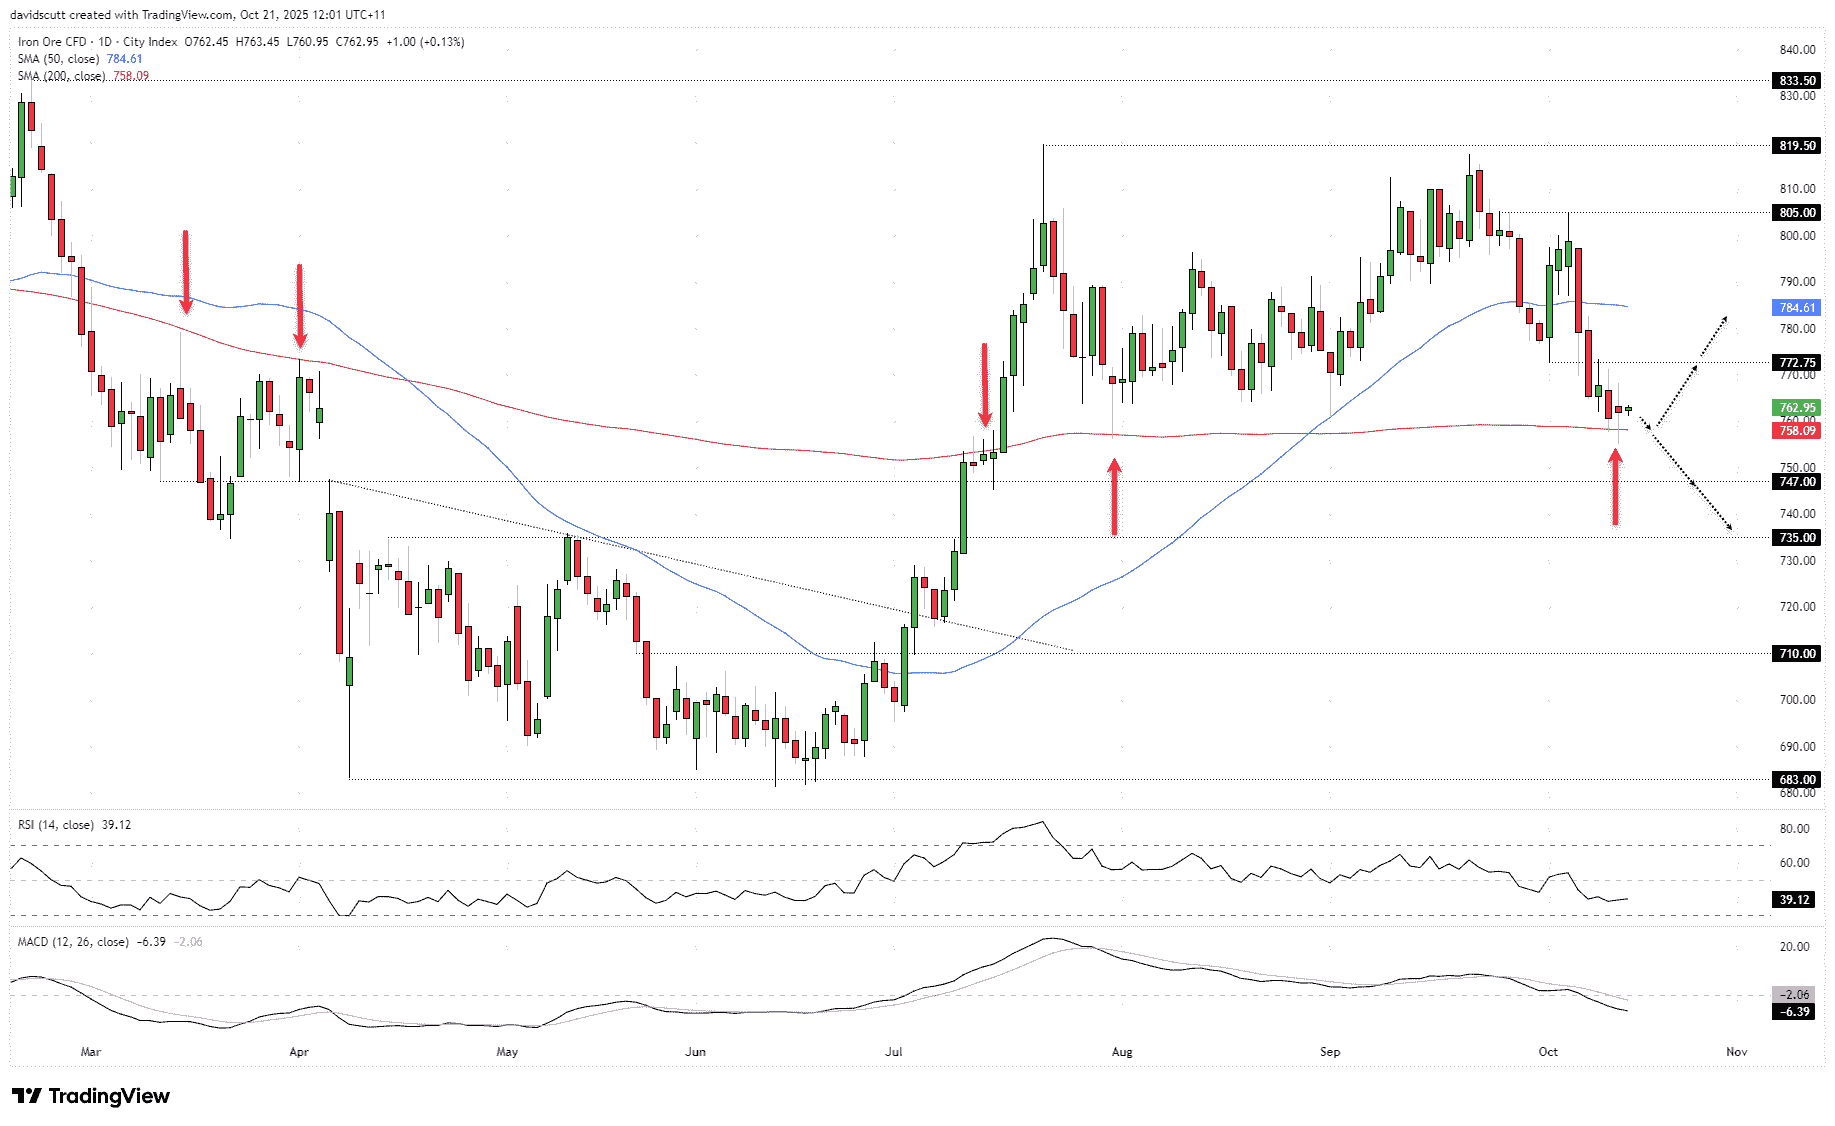
Before looking at potential trade ideas, it’s worthwhile pointing out just how respectful the iron ore contract has been of the 200-day moving average so far in 2025, often testing the level but rarely breaking sustainably through it.
Given that historic relationship, it suggests the level could be a good one to build setups around, allowing for entry on one side with a stop on the other to protect against reversal.
Source: TradingView
The price has traded through the 200DMA in each of the past two sessions only to reverse back higher, reinforcing its importance. Signals from RSI (14) and MACD reveal a picture of strengthening bearish momentum, with the former trending lower beneath 50 while the latter has pushed into negative territory having already crossed over from above earlier this month. The overall backdrop therefore favours downside over upside near term.
Should those downside risks materialise with the price breaking and closing beneath the 200DMA, shorts could be established beneath the level with a stop above for protection, targeting either ¥747 or ¥735, two levels that provided both support and resistance earlier this year.
However, if the price continues to bounce from the 200DMA as has been the case on the last three times of testing, it may provide enough confidence to initiate countertrend long trades, allowing for positions to be established above the level with a stop below for protection. ¥772.75 is a minor level above that could act as an initial target. Beyond, the 50DMA screens as another option along with ¥790 which saw plenty of price action either side of it during August and September.


Fundamental backdrop deteriorates
As mentioned in the summary, the fundamental backdrop appears anything but bullish for iron ore given recent news flow. Urban fixed asset investment—which measures spending on buildings, structures and equipment designed to last two years or more—contracted 0.5% between January to September relative to the same period a year earlier. It was the first decline since the pandemic shutdowns in early 2020. That’s clearly not good news for industrial commodities like iron ore. Nor was data showing crude steel output—of which iron ore is a key ingredient in conventional steelmaking—slumped to 73.49 million tonnes in September, a 21-month low and 4.6% below the levels of a year earlier.
Adding to the bearish demand picture, there remains no signs of an easing in China’s property market slump with data released on Monday revealing new and existing prices nationwide fell 0.4% and 0.6% respectively last month, accelerating on the pace seen in August. Once the single largest source of steel demand globally, declining construction activity, negative population growth and continued price weakness remains a clear negative for the iron ore price outlook.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.