



Japanese Yen Outlook: USD/JPY Surges as Fed Cut Bets Fade
Tokyo CPI lands soon, but U.S. data is steering USD/JPY. Rate-sensitive moves suggest spending and income figures matter more. Japan may take a back seat.
Share this:
- USD/JPY breaks higher as U.S. data reinforces short-end rate sensitivity
- Fed cut expectations unwind, giving bulls fresh momentum
- Tokyo CPI unlikely to shift the dial unless it delivers a major surprise
- Watch Fed speakers post-PCE for clues on policy direction
USD/JPY Outlook Summary
Upside risks flagged for USD/JPY in our weekly outlook guide have materialised nicely, with the pair breaking higher on Thursday following a string of stronger-than-expected U.S. economic data. Right now, correlation analysis reveals it’s U.S. interest rates driving the price action, particularly the front end of the curve where the relationship has been extremely tight over the past fortnight. If that continues, it suggests the U.S. personal consumption and expenditures report for August, rather than Tokyo consumer price inflation data for September, looms as the most likely risk event to generate volatility on Friday.
Fed pricing driving the price action
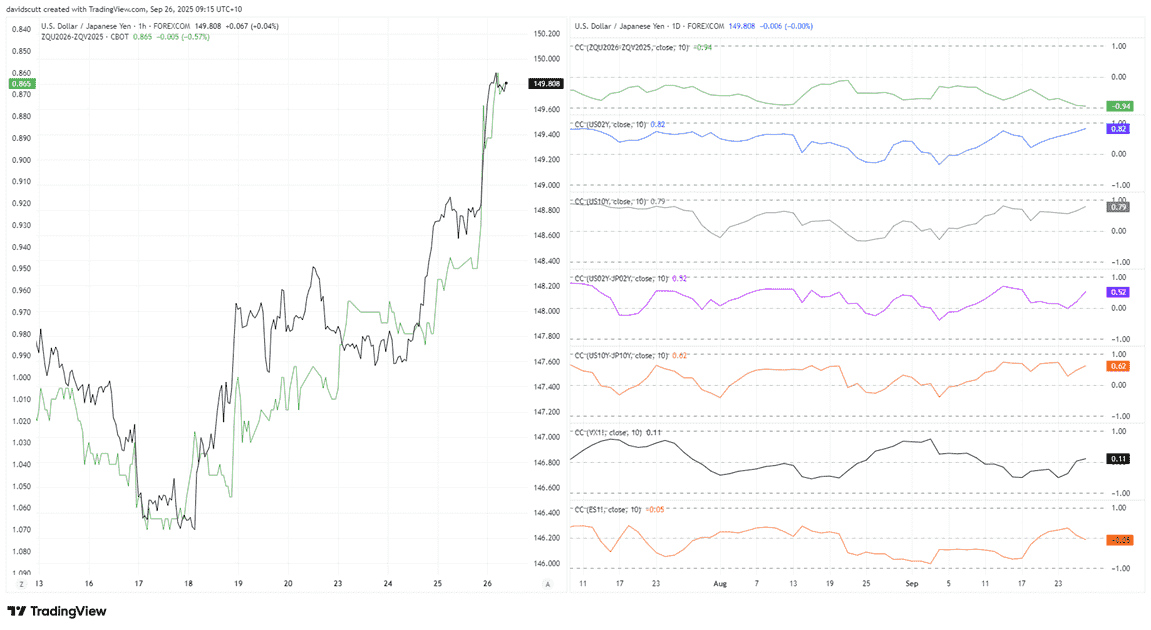
Market pricing for Fed rate cuts is driving USD/JPY, as demonstrated by the correlation coefficient of -0.94 with the shape of the Fed funds futures curve between October 2025 and September 2026, shown in green in the chart below. The left-hand pane visualizes the relationship, inverting the scale of Fed pricing over an hourly timeframe to show just how tight it’s been. Slightly weaker readings have been seen with two- and 10-year U.S. Treasury yields over the same period, shown in blue and grey respectively. In contrast, U.S.-Japanese yield differentials over the same tenors—along with other traditional drivers such as risk appetite and volatility measures—have shown far weaker or no relationship at all.
Source: TradingView
U.S. data is therefore key
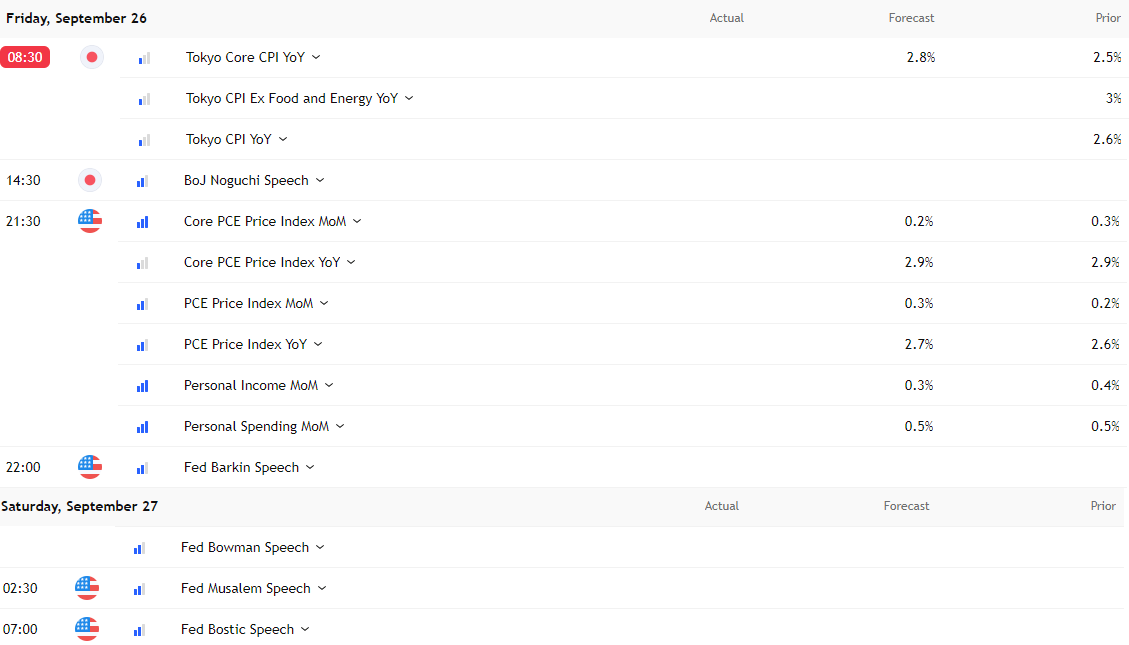
This points to U.S. data being the most likely catalyst to spark volatility in USD/JPY on Friday, barring a shock outcome from Tokyo CPI released at 8:30 a.m. in Japan. Core inflation, which excludes fresh food prices, is expected to accelerate to an annual pace of 2.8%, up from 2.5% in September. Core-core CPI, which also strips out energy prices, is forecast to moderate to an annual clip of 2.8%, down from 3% previously. After two board members voted for a 25 basis point rate cut last week, watch for any remarks related to the data from BOJ board member Asahi Noguchi, who voted to keep the overnight rate unchanged at 0.5%.
Source: TradingView


Realistically, the U.S. calendar screens as more significant for USD/JPY today given the strong linkages to short-end U.S. rates—but not necessarily the core PCE deflator. While it may be the Fed’s preferred underlying inflation measure, it rarely delivers major surprises nowadays. A stronger signal on future domestic inflationary pressures may instead come from separate spending and incomes data released within the report. If strong, it will further weaken the case for rate cuts given we’re talking about the largest and most important component of the U.S. economy.
Whatever the details, pay extra attention to Fed speakers scheduled after the data is released. If there’s a message to be sent, it will likely come via those speeches rather than appearances beforehand.
USD/JPY breaks higher
Source: TradingView
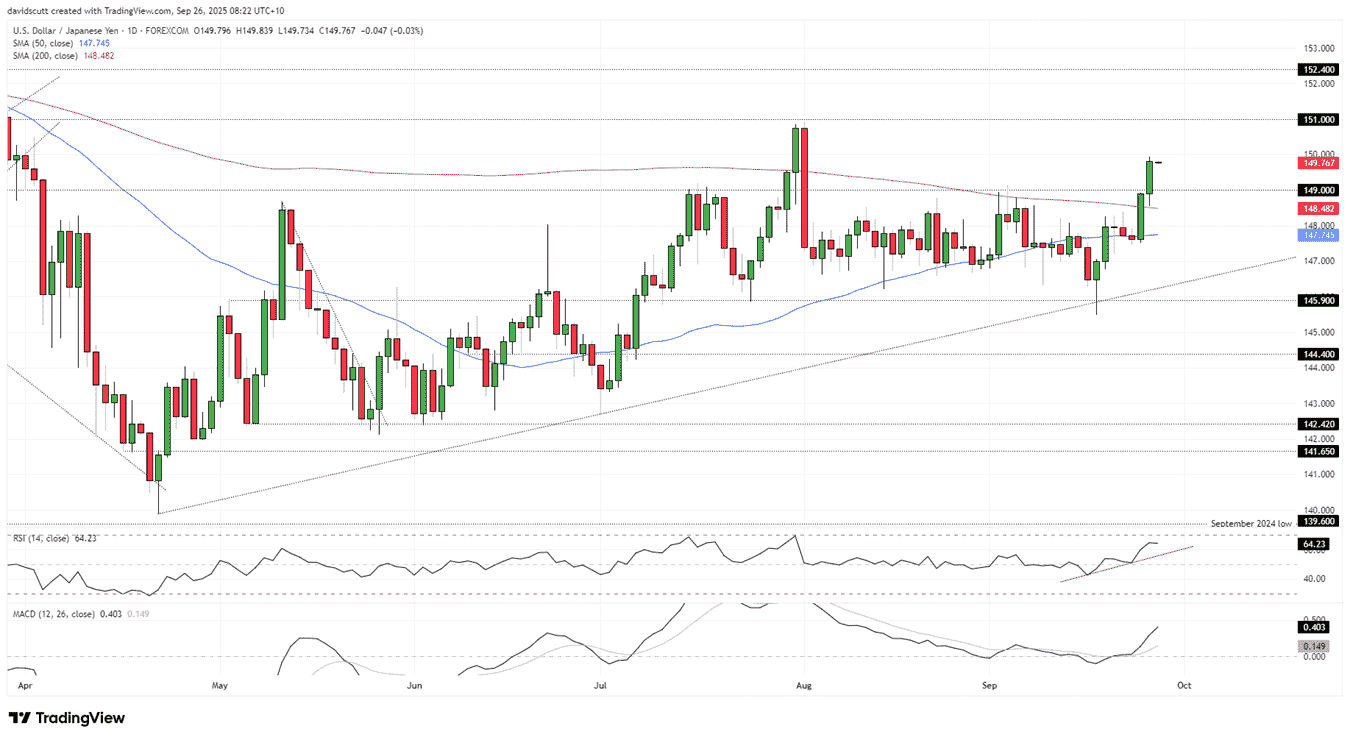
With Fed rate cut pricing dwindling, USD/JPY has finally broken out of the sideways range it was stuck in since the July payrolls report was released at the start of August, surging above the 200DMA on Wednesday before taking out resistance overhead at 149.00 on Thursday. That level may now act as support, providing a potential base for longs to be established by those seeking an eventual retest of resistance at 151.00 or even 152.40.
RSI (14) and MACD are trending higher in bullish territory, painting a picture of strengthening upside pressure. That favours longs over shorts in the near term.
While the price and momentum picture is entirely bullish, recent stays above the 200DMA have proved fleeting for USD/JPY this year, underlining the need to be selective on entry levels for those playing the pair from the long side.
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
dax-26000-bayer-siemens-energy-sektorrotation-us-zwischenwahlen
The DAX briefly reclaimed the 26,000 level as investors used post-election weakness as an opportunity to rotate into industrial, healthcare and energy-transition leaders. Strong gains in Bayer, Siemens and Siemens Energy helped offset weakness in consumer and AI-related growth stocks. With bond yields easing and the dollar weakening after the US midterm elections, investors are increasingly focusing on earnings quality, visible demand and infrastructure-related growth themes.
Blue wave adds to Nikkei’s AI troubles
The Nikkei 225 has taken another beating as a Democratic sweep adds to concerns about AI investment returns. But after the scale of the earlier declines, how much bad news is already priced in?

US dollar outlook: Nasdaq breakdown raises stakes for EUR/USD, USD/JPY
A potential Democratic sweep of Congress is adding to the AI trade's headaches, with Nasdaq 100 futures breaking below a major technical level. The implications for the dollar could be significant.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.