



Market Brief Pound Sets the Pace but Strength May Be ShortLived
See a summary of the top market themes and trends from today's US trading session!
Share this:

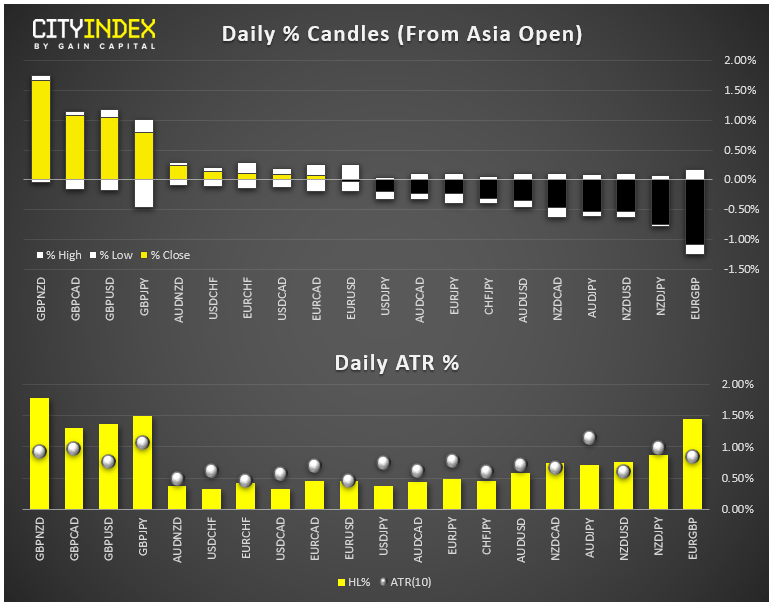
- FX: The pound was by far the strongest major currency on the day after German Chancellor Angela Merkel said that a solution on the Irish backstop is possible within 30 days (though it’s since been suggested that she was just being “polite”). The kiwi was the weakest major currency today.
- US data: Initial jobless claims came in at 209k, below estimates of 216k. Markit Manufacturing PMI missed estimates and dipped into contractionary territory at 49.9.
- In comments to media, two Fed Presidents (Kaplan and Harker) struck opposite notes on the economy and monetary policy (dovish and hawkish respectively). As we noted yesterday, Fed Chairman Powell’s speech at Jackson Hole tomorrow will be key given the diverging opinions among Fed policymakers.
- Commodities: Both gold and oil edged about 0.5% lower on the day.

- US indices recovered from a late morning swoon to finish mixed on the day.
- Financials (XLF) were the strongest sector on the day while Materials (XLB) were the weakest.
- Stocks on the Move:
- Boeing (BA) surged more than 4% on news that company’s 737 MAX plane may be just 4-6 weeks from getting reapproved by the Federal Aviation Administration.
- Retailers remained strong again today after strong earnings from BJ’s Wholesale Club (BJ, +17%) and Nordstrom (JWM, +16%).


- FX: The pound was by far the strongest major currency on the day after German Chancellor Angela Merkel said that a solution on the Irish backstop is possible within 30 days (though it’s since been suggested that she was just being “polite”). The kiwi was the weakest major currency today.
- US data: Initial jobless claims came in at 209k, below estimates of 216k. Markit Manufacturing PMI missed estimates and dipped into contractionary territory at 49.9.
- In comments to media, two Fed Presidents (Kaplan and Harker) struck opposite notes on the economy and monetary policy (dovish and hawkish respectively). As we noted yesterday, Fed Chairman Powell’s speech at Jackson Hole tomorrow will be key given the diverging opinions among Fed policymakers.
- Commodities: Both gold and oil edged about 0.5% lower on the day.
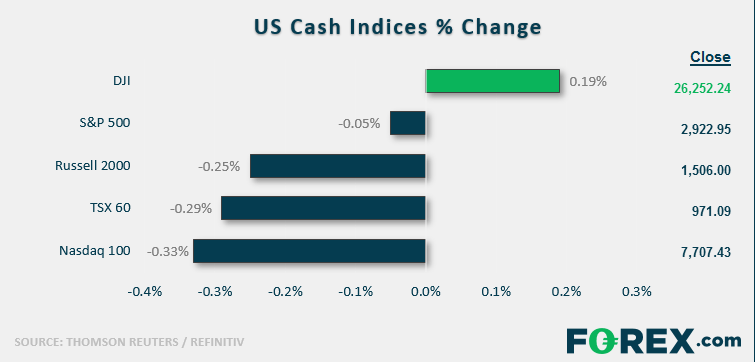
- US indices recovered from a late morning swoon to finish mixed on the day.
- Financials (XLF) were the strongest sector on the day while Materials (XLB) were the weakest.
- Stocks on the Move:
- Boeing (BA) surged more than 4% on news that company’s 737 MAX plane may be just 4-6 weeks from getting reapproved by the Federal Aviation Administration.
- Retailers remained strong again today after strong earnings from BJ’s Wholesale Club (BJ, +17%) and Nordstrom (JWM, +16%).
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.