




Market Brief Trade Optimism Sets The Tone
A summary of news and snapshot of moves from today’s Asia session.
Share this:

- News that US ad China are set to resume trade talks in Washington next month extended yesterday’s relief rally.
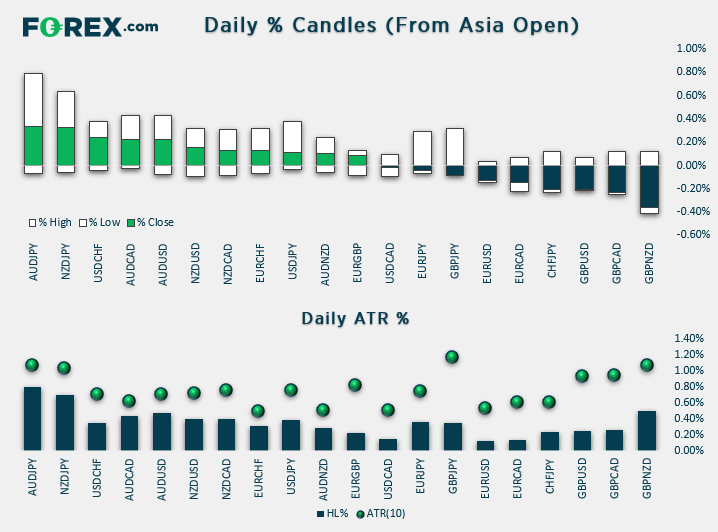
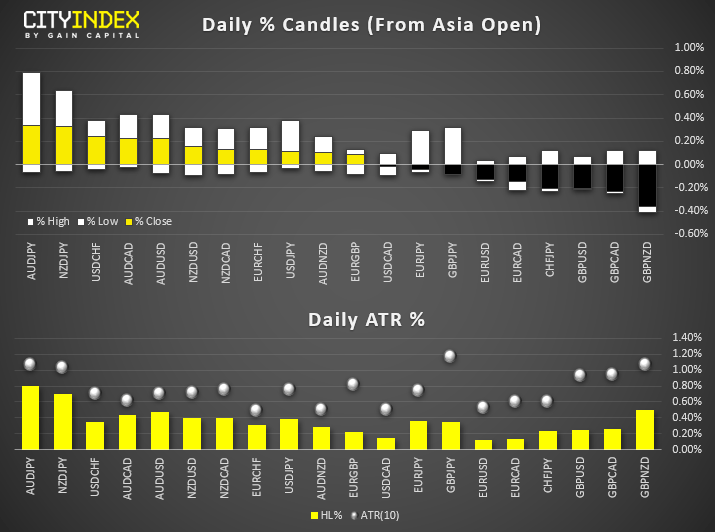
- Commodity currencies (AUD, NZD and CAD) were quick to react and are today’s strongest majors. AUD/USD rebounded to its highest level since 1st August although has stalled beneath 0.6832 resistance – a pivotal level traders should be keeping an eye on.
- The positive sentiment also saw PBOC weaken their FIX ad allow USD/CNH to fall to an 8-day low. USD/JPY hit resistance at 106.78, GBP/USD remains within its bearish channel but could be headed for a break higher. WTI trades in a tight range around $56. Gold and silver remain stubbornly high, despite the weaker USD pricing, although both trade slightly lower for the session.
- Equity markets were broadly higher on trade optimism today, adding to yesterday’s relief rally fuelled by improved Chinese data and Hong Kong’s withdrawal of the extradition treaty.
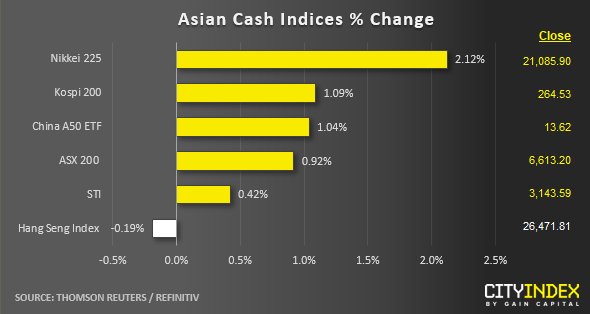
- The rebound was led by Japan and China, with the Topix and CSI gaining 1.84% and 1.62% respectively. The exception to the rally was the Hang Seng Index (HSI) which trades -0.13% lower. Index futures are also pointing higher, with the S&P500 E-mini breaking to a 1-month high.
- The Hang Seng, which rallied over 3.7% yesterday when Hong Kong’s PM officially withdrew the extradition treaty, failed to extend gains today. Whilst the withdrawal was a step in the right direction, protestors still want their four remaining demands met. Three of which include the PM stepping down, HK having control over the selection of a new leader and the end to police brutality
Up Next:
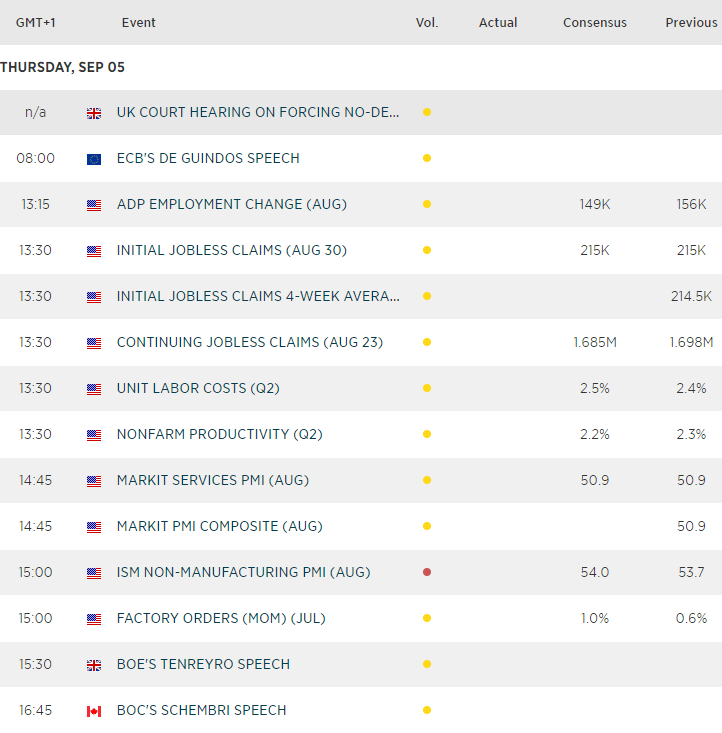
- UK's PM Boris Johnson is set to 'speak to the public' around 3pm GMT today, and is expected to say he wants an election and that the "surrender bill" would effectively overturn the largest democratic bill in UK's history.
- ISM non-manufacturing (services) is expected to rise to 54 from 53.7 prior, although the weak print from ISM manufacturing could have traders on edge for a soft print from services today. Whilst it remains expansive at 53.7, it has nose-dived since peaking at 60.8 in 2018. Keep USD crosses and US indices on your radar around this release.
- ISM aside, it’s mostly 2nd tier data, so it could be trade which remains at the forefront for traders. This places commodities, commodity FX and JPY pairs on trader’s radars.
- News that US and China are set to resume trade talks in Washington next month extended yesterday’s relief rally.
- Commodity currencies (AUD, NZD and CAD) were quick to react and are today’s strongest majors. AUD/USD rebounded to its highest level since 1st August although has stalled beneath 0.6832 resistance – a pivotal level traders should be keeping an eye on.
- The positive sentiment also saw PBOC weaken their FIX ad allow USD/CNH to fall to an 8-day low. USD/JPY hit resistance at 106.78, GBP/USD remains within its bearish channel but could be headed for a break higher. WTI trades in a tight range around $56. Gold and silver remain stubbornly high, despite the weaker USD pricing, although both trade slightly lower for the session.
- Equity markets were broadly higher on trade optimism today, adding to yesterday’s relief rally fuelled by improved Chinese data and Hong Kong’s withdrawal of the extradition treaty.
- The rebound was led by Japan and China, with the Topix and CSI gaining 1.84% and 1.62% respectively. The exception to the rally was the Hang Seng Index (HSI) which trades -0.13% lower. Index futures are also pointing higher, with the S&P500 E-mini breaking to a 1-month high.
- The Hang Seng, which rallied over 3.7% yesterday when Hong Kong’s PM officially withdrew the extradition treaty, failed to extend gains today. Whilst the withdrawal was a step in the right direction, protestors still want their four remaining demands met. Three of which include the PM stepping down, HK having control over the selection of a new leader and the end to police brutality
Up Next:
- UK's PM Boris Johnson is set to 'speak to the public' around 3pm GMT today, and is expected to say he wants an election and that the "surrender bill" would effectively overturn the largest democratic bill in he UK's history.
- ISM non-manufacturing (services) is expected to rise to 54 from 53.7 prior, although the weak print from ISM manufacturing could have traders on edge for a soft print from services today. Whilst it remains expansive at 53.7, it has nose-dived since peaking at 60.8 in 2018. Keep USD crosses and US indices on your radar around this release.
- ISM aside, it’s mostly 2nd tier data, so it could be trade which remains at the forefront for traders. This places commodities, commodity FX and JPY pairs on trader’s radars.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.