



Marketbrief: DAX rises, Europe Awaits CPI and Tech Volatility Dominates
Asian equities gained despite weak US tech sentiment and stalled Iran talks, while Europe braced for key inflation data. The DAX shows improving bullish momentum with higher lows and rising SMAs. US markets traded mixed as Nvidia’s rally faded, trade tensions resurfaced, and central banks struck a cautious tone. Geopolitical risks remain elevated, but markets stayed resilient.
Share this:

Market Summary – 27 February 2026
1. Global Market Overview
Asian equities finished mostly higher despite choppy trading, absorbing weaker US tech sentiment and the lack of a breakthrough in US–Iran talks in Geneva. Technical discussions between the US and Iran will resume in Vienna next week, with both sides citing “serious progress” but no agreement yet. The PBoC announced a cut to the FX Risk Reserve Ratio for forward FX sales from 20% to 0% effective March 2, aimed at supporting corporate FX risk management and slowing rapid currency appreciation.
European equity futures pointed to a flat open after Thursday’s slight declines, with markets awaiting German and French/Spanish CPI, German unemployment data, and Canadian GDP.
DAX Technical Analysis 4 hour chart
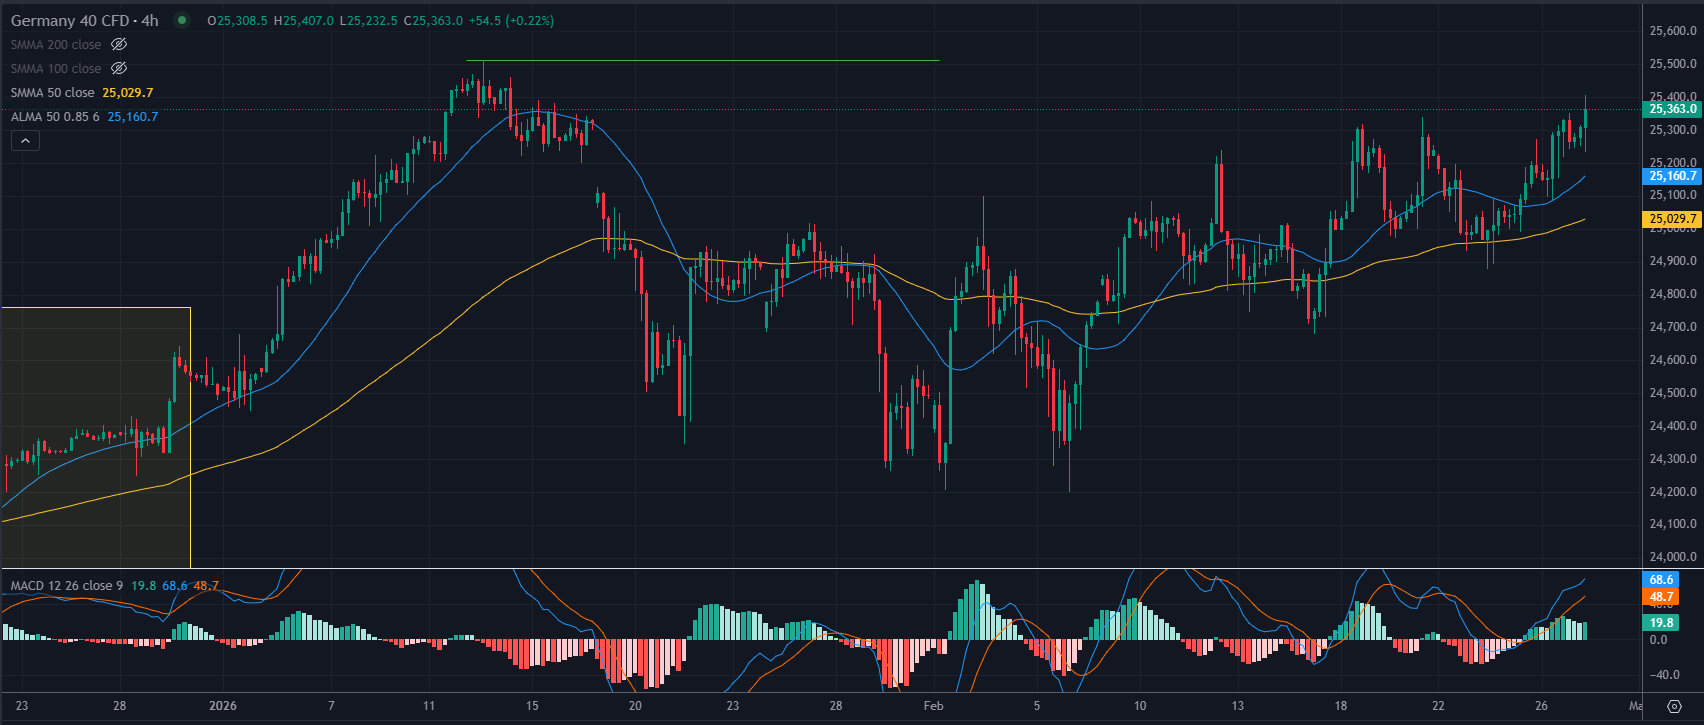
The Germany 40 continues to build a constructive higher‑low structure, supported by the 50‑SMA and 100‑SMA, both trending upward and currently aligned around the 25,050–25,100 region. Price has now broken above short‑term consolidation and is attempting to reclaim the February swing highs. The steady progression toward the 25,300 resistance level suggests improving bullish pressure, especially as the 200‑SMA remains well below price and rising—confirming a supportive medium‑term trend. As long as the index holds above 25,050, the bias favors continuation toward the 25,300–25,350 resistance zone.
Momentum indicators confirm strengthening bullish momentum. MACD has crossed decisively above its signal line and is widening in positive territory, reflecting increasing buying strength. RSI sits near 60, consistent with a bullish but not overstretched market, providing room for further upside. Overall, the technical picture is improving: sustaining price above the rising moving averages keeps bulls in control, with a break above 25,300 likely triggering a push toward the late‑January highs. A slip back below 25,000 would be the first sign of momentum fading.
2. US Equities & Corporate Earnings
US stocks ended mixed in a risk‑off session:
- S&P 500 −0.54%, Nasdaq −1.16%, Dow +0.03%, Russell 2000 +0.52%.
Nvidia’s initial post‑earnings strength faded, dragging the broader tech complex, particularly hardware. Software outperformed following strong recent earnings. Sentiment was also hit by reports that preparations for a Trump–Xi summit were faltering, and by early negative headlines from US–Iran talks before later improving.
Nvidia’s Q4 earnings beat expectations again:
- Revenue USD 68.1bn (exp. 66.1bn)
- Adj. EPS 1.62 (exp. 1.54)
Futures initially rose after the beat but later pared gains as geopolitics and tech volatility weighed on sentiment.
3. US Trade Policy & Tariffs
The US ITC launched a fact‑finding investigation into the implications of revoking permanent normal trade relations with China. Canada noted that early USMCA discussions remain constructive, with scope for bilateral arrangements. Nvidia confirmed it received a US license to ship a small amount of H200 chips to China, though these face a 25% tariff. China’s DeepSeek denied Nvidia and AMD access to its next model, granting early access instead to domestic champions such as Huawei.
The UK is set to announce a critical‑minerals partnership with Kazakhstan as part of a broader effort by Western nations to diversify supply chains away from China.
4. Central Banks & Policy
Fed’s Goolsbee reiterated that rate cuts are possible but should not be front‑loaded, highlighting solid economic conditions and a stable labour market. Separately, the Federal Reserve is reportedly challenging subpoenas related to a criminal probe involving Chair Powell.
The PBoC lowered its FX Risk Reserve Ratio to zero, signalling a desire to stabilise FX markets and support exporters.
The Bank of Japan continues to signal a gradual tightening bias. Tokyo CPI came in above expectations but declined meaningfully from prior months, falling back below the BoJ’s 2% target on core measures. BoJ board member Takata argued for continued gradual rate hikes. Meanwhile, the Korean central bank held rates unchanged at 2.50%, raising its GDP and CPI forecasts for 2026.
5. APAC Markets
The ASX 200 ended slightly higher on gains in tech and telecoms, offsetting weakness in financials and consumer stocks.
Japan’s Nikkei 225 traded indecisively amid currency strength and mixed domestic data: industrial production disappointed, retail sales exceeded expectations, and Tokyo CPI slowed.
Hong Kong outperformed on earnings (notably Baidu and Sun Hung Kai Properties), while the Shanghai Composite saw late gains after the Politburo signalled continued fiscal support and a moderately loose monetary policy stance.
US equity futures remained subdued as traders digested Nvidia’s inability to extend its rally and the continued geopolitical uncertainty.
6. FX Markets
The dollar drifted slightly lower in a narrow range.
- EUR/USD held around 1.18.
- GBP/USD traded near 1.35 amid weak UK consumer confidence.
- USD/JPY retreated following soft risk sentiment and Tokyo CPI.
Antipodeans (AUD/NZD) rebounded modestly, helped by firm Australian capex data.
The yuan weakened after the PBoC cut the FX reserve ratio and set a weaker‑than‑expected midpoint fixing at 6.9228.
7. Fixed Income
US Treasuries extended gains on safe‑haven demand and a strong 7‑year auction. Bunds moved toward the 130.00 handle as markets eyed Eurozone inflation data. Japanese government bonds rebounded from recent lows, supported by softer inflation momentum and mixed auction results.
8. Commodities
Oil prices traded rangebound after Thursday’s sharp moves, as progress in Geneva talks offset concerns about a potential US strike on Iran.
Gold held near USD 5,200/oz but remained capped.
Copper saw two‑way trade amid uneven sentiment in Asia.
9. Crypto
Bitcoin finally moved higher, reclaiming levels above USD 68,000, supported by improved risk appetite.
10. Geopolitics
US–Iran
Negotiations in Geneva were described as “serious” and “constructive” by both sides. While Iran emphasised sanctions relief and insisted it will never pursue nuclear weapons, the US pressed for permanent dismantling of nuclear sites, zero enrichment, and full uranium handover. Internal US discussions reportedly focus not on whether to strike Iran but how broadly, should talks fail. The US Navy’s 5th Fleet reduced staffing in Bahrain ahead of potential escalation.
Russia–Ukraine
Zelensky said trilateral talks with the US and Russia will likely resume in early March in the UAE.
Asia & Middle East
Pakistan declared “open war” on the Taliban government after border clashes.
China advised citizens to avoid travel to Japan.
US eyes closer ties with Cuba and is pressing Syria to reduce reliance on Chinese telecom systems.
11. EU & UK
The UK Green Party won the Gorton & Denton seat in a by-election, defeating Labour. The UK government is reportedly in talks with oil and gas companies about ending the windfall tax.
UK consumer confidence fell to −19, while the business barometer held steady at 44.
12. Macro Data Recap
Japan:
- Industrial Production: 2.2% (exp. 5.3%)
- Retail Sales: +1.8% (exp. −0.4%)
- Tokyo CPI (YoY): 1.6% (exp. 1.4%)
- Core: 1.8% (exp. 1.7%)
- Core ex‑fresh food & energy: 2.5%
UK:
- GfK Consumer Confidence: –19
- Lloyds Business Barometer: 44
13. US Macro & Trade Policy Developments
A recent Supreme Court decision struck down tariffs imposed under IEEPA, affecting roughly USD 175bn of revenue collected since 2025. The administration pivoted to Section 122 emergency tariffs—a 10% global rate for up to 150 days—while preparing investigations to restore tariffs near previous levels.
US Q4 GDP grew 1.4%, pulled down by the government shutdown; underlying domestic demand grew 2.4%. Headline PCE inflation rose to 2.9%, core to 3.0%, driven by food and core goods.
Nvidia’s strong earnings lifted Nasdaq‑100 earnings growth expectations to 17%, up from 16% last week.
Major US indexes remain flat to +1% over the past week; 10‑year Treasury yields eased to ~4%.
-Philip Papageorgiou – Markt Analyst
--X ex Twitter: PhilipForexCom
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.
S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

Canadian Dollar Forecast: USD/CAD Four-Week Rally Eyes Yearly Highs 9 30 2026
USD/CAD has advanced in 14 of the past 15 sessions, but stretched momentum raises the stakes as major resistance and NFP come into focus.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.