



Global Selloff Deepens as Nvidia Euphoria Fades; Crypto Crashes
Global markets reversed sharply from Nvidia-driven optimism as tech valuations and Fed uncertainty triggered a broad selloff. The Nikkei and MSCI Asia-Pacific dropped over 2%, while US and European futures declined. Bitcoin collapsed 30% from its highs, erasing $600 bn in value, and oil extended losses as Russia–Ukraine peace talks resumed. The DAX is stabilizing near its 200 EMA with oversold signals emerging. Meanwhile, Trump’s “national champions” initiative and stronger EM earnings provided selective support. Markets remain defensive heading into year-end amid policy and geopolitical crosscurrents.
Share this:

Market Summary – 21 November 2025
Global Markets
- Asia slumps: Regional equities tumbled, with the Nikkei and MSCI Asia-Pacific both down over 2 % as the delayed US jobs data failed to clarify the Fed’s next move.
- Tech-led global selloff: US and European futures fell sharply as AI valuations came under renewed pressure despite Nvidia’s strong guidance. The Nasdaq saw its widest swing since April, while Goldman Sachs warned of USD 39 bn in equity sales from trend-following hedge funds.
- US session recap: Wall Street opened higher on Nvidia optimism before reversing hard into the close.
- Early risk-on saw equities rally, high-beta FX rise, and crude strengthen.
- Later risk-off was broad and catalyst-free, driven by valuation fatigue in tech.
- US rates: September jobs data showed strong payroll gains but a higher jobless rate and downward revisions, leaving Fed expectations mixed; December rate-cut odds rose to ~40 % as Treasury yields fell.
- Japan:
- Announced a ¥21.3 tn stimulus plan, temporarily weighing on the yen and JGBs; yields eased after officials signaled issuance below last year’s level.
- Core inflation +3 % (Oct) intensified pressure on the BoJ to tighten, while authorities reiterated FX intervention risks as the yen hovered near a 10-month low.
- Commodities:
- Oil extended losses on optimism about Russia–Ukraine peace talks.
- Gold pulled back from highs as haven demand shifted toward the yen.
- DAX Technical Analysis:
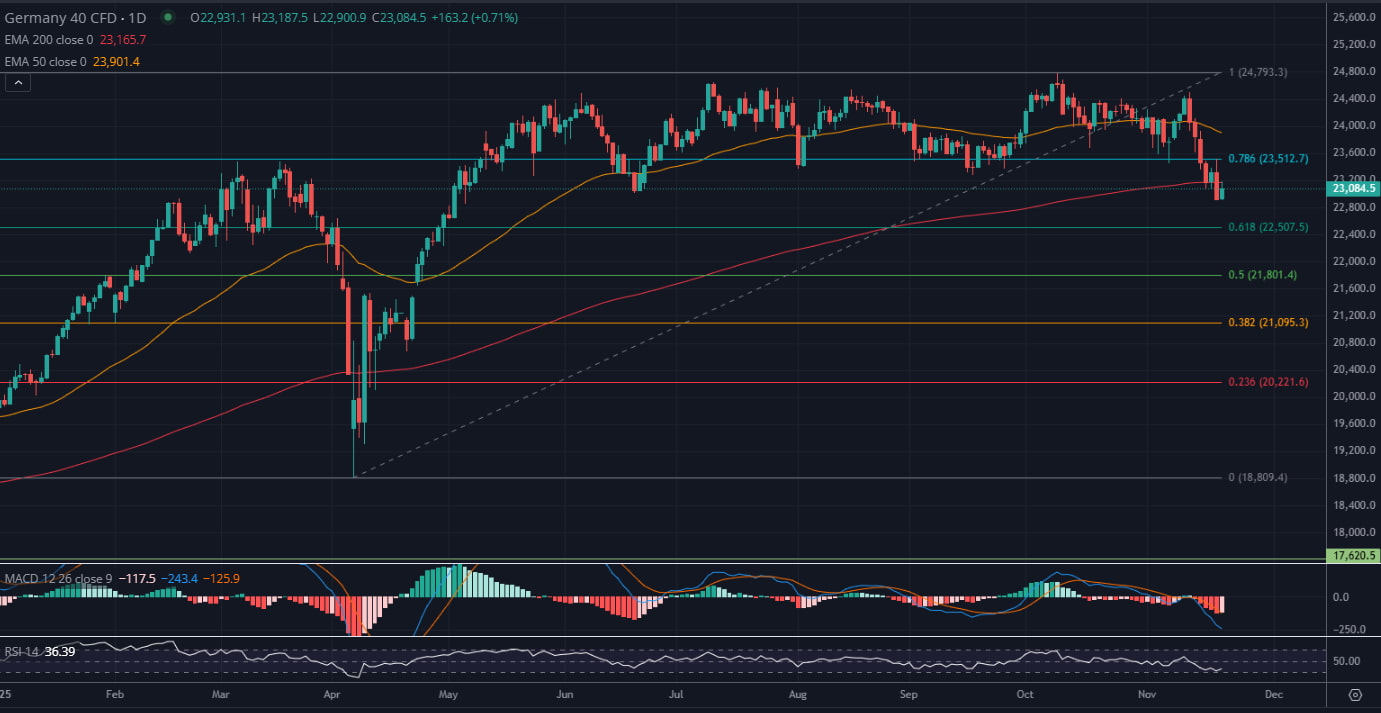 The Germany 40 CFD (daily) is attempting to stabilize near the 200 EMA (23,165) after a sharp correction from recent highs. The index bounced modestly from the 22,900–23,000 area, aligning closely with the 0.618 Fibonacci retracement (22,507) of the prior uptrend. The MACD remains deeply negative, confirming bearish momentum, while the RSI (36) is hovering just above oversold territory, signaling that selling may be losing intensity.
- Immediate resistance is at 23,500 (0.786 Fib), then 23,900 (50 EMA). A daily close above these levels would signal a recovery attempt, while failure to hold above 22,900–22,800 risks a deeper retracement toward 21,800 (0.5 Fib). Tone: bearish bias softening, potential for short-term base forming near the 200 EMA and key Fib support.
Cryptocurrencies
- Bitcoin collapse: Fell about 30 % from its early-October record high (~USD 126 k) to ~USD 88.3 k, its lowest since April — erasing ~USD 600 bn in market value and now –6 % YTD.
- Drivers: waning Fed-cut expectations, reduced risk appetite, and rising equity hedging.
- Options demand surged for downside protection at USD 85 k and 80 k strikes.
- Safe-haven rotation: Gold and the Swiss franc outperformed, underscoring Bitcoin’s limited use as an equity hedge.
- Latest leg lower: Bitcoin fell another 6 % Friday to USD 85,350, its seven-month trough, with weekly losses >9 %.
- Crypto market cap –USD 1.2 tn in six weeks (CoinGecko).
US Policy & Strategic Industry Moves
- National champions initiative:
- The Trump administration has acquired minority stakes and option-like structures in listed US firms across critical supply chains—rare earths, semiconductors, and nuclear energy.
- Aims: secure strategic independence, foster public-private partnerships, and shield domestic players from foreign competition.
- Short-term market reaction positive on expectations of preferential treatment, contracts, and regulatory relief.
- Long-term impact remains uncertain, but analysts see opportunity in tracking firms designated as “national champions.”
Emerging Markets Earnings
- MSCI EM Q3 season:
- ~85 % of companies (≈80 % of index mkt cap) have reported.
- Aggregate earnings +13 % YoY; one-third beat estimates, 28 % missed.
- Asia IT standout: regional IT profits +44 % YoY; South Korea +32 %, Taiwan +28 %.
- Central European names (Poland, Czech Republic) also strong (>20 % growth); Latin America lagged (–12 %).
- Analysts forecast EM profit growth rising from +11.4 % (2025) to +17.5 % (2026), led by Asian semiconductors (+33 %).
- Seoul market remains a top pick given robust earnings upgrades and moderate valuations.
Russia–Ukraine Developments
- Trump peace plan:
- 28-point framework would require Ukraine to cede eastern territory, cap military size, and forgo NATO membership, while providing a US-EU security guarantee modeled on NATO Article 5.
- White House said the plan is “acceptable to both sides” and ongoing talks are “positive.”
- Envoys Witkoff and Rubio met Ukrainian officials; President Zelensky confirmed coordination on next steps.
- Russian advances:
- Putin: Russian troops active in Kostiantynivka, claiming control of Kupyansk and 80 % of Vovchansk; urged Ukrainian forces to surrender.
Overall:
Global markets reversed from Nvidia-driven euphoria to broad risk aversion as valuation fears resurfaced and Fed uncertainty persisted. Asia and tech stocks bore the brunt of selling; oil and crypto slumped, while the yen and safe-havens regained footing. EM earnings momentum remains intact, but geopolitical and policy headlines dominate short-term sentiment.
Philip Papageorgiou – Market Analyst
X: PhilipForexCom



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.

Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.


Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.