



Marketbrief: DAX Eyes Breakout & Markets Pause Ahead of Key US Data
Global markets trade cautiously ahead of delayed US NFP and CPI. The S&P 500 and Nasdaq eased as investors digested soft macro data and mixed sector flows, while Asia posted modest gains on liquidity support from China. The DAX holds above key averages and presses major resistance near 25,000. USD weakens, oil rebounds, gold stays above $5,000, and Bitcoin drifts lower amid macro uncertainty.
Share this:

Morning Market Brief – February 11, 2026
Global markets enter mid‑week trading in a tentative mood as investors await a cluster of influential US data releases, notably the delayed Nonfarm Payrolls on Wednesday and CPI on Friday. After Monday’s tech‑driven rally, equity markets paused on Tuesday, reflecting digestion of mixed macro data, repositioning ahead of major catalysts, and continued sector rotation beneath the surface. Asia pushed modestly higher overnight, supported by liquidity signals from China but restrained by looming uncertainties. Europe is set for a quiet open.
US Markets: Consolidation Ahead of the Data Cascade
US equities finished broadly weaker on Tuesday, though losses remained contained. The S&P 500 fell 0.33%, the Nasdaq 100 slipped 0.56%, while the Dow eked out a 0.10% gain, securing a third consecutive record close. The Russell 2000 ended 0.34% lower, with small caps losing momentum after last week’s strong rebound.
Trading reflected subdued macro data: retail sales disappointed, import prices were tepid, export prices softened, and employment-cost components undershot expectations. ADP figures showed just 6.5k jobs added per week on average over the past month, reinforcing the sense of cooling in labour demand.
Sector performance was mixed. Utilities, Real Estate, and Materials outperformed, while Financials and Communications lagged, the latter pressured by continued weakness in Alphabet. In Financials, notable declines in Charles Schwab and Interactive Brokers late in the session lacked a clear catalyst, though some desks pointed to commentary about Altruist embedding AI tax‑planning tools. Datadog, meanwhile, surged 11% on strong earnings, providing support to software names.
Investors also weighed a series of Fed remarks. Governor Hammack argued policy is “in the vicinity” of neutral and could remain on hold for an extended period, while Dallas Fed’s Logan said further cuts may not be needed if inflation continues to ease and labour markets stabilise. President Trump reiterated his preference for the lowest rates in the world, praising current job numbers and pressing political narratives ahead of the Fed’s next phase under the incoming Chair.
Europe – Germany 40 attempting breakout above resistance
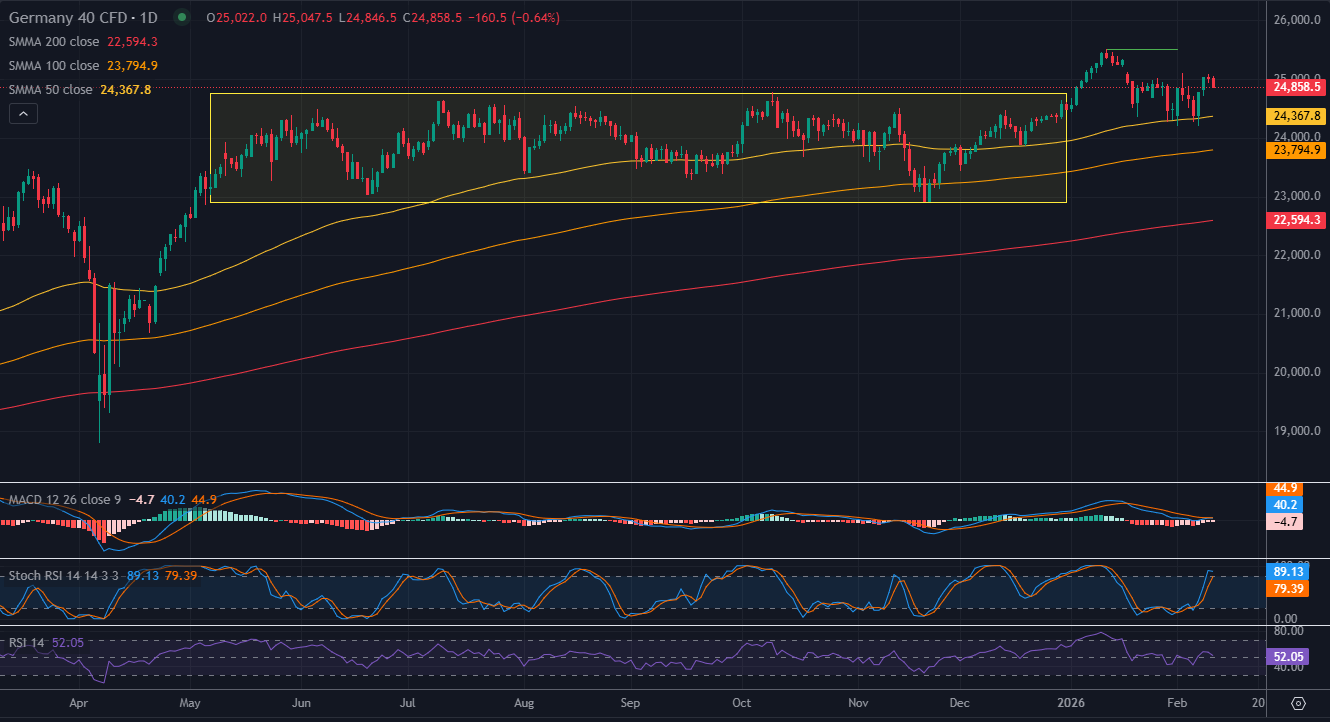
The Germany 40 continues to trade just below major horizontal resistance around the 25,000–25,100 zone, an area that capped price action throughout mid‑2025 and has again acted as a ceiling in early 2026. Despite the rejection seen today, the index remains above all key daily moving averages, with the 50‑SMA and 100‑SMA providing robust underlying support near 24,350–24,000. This suggests the broader structure remains bullish, and the recent breakout from the months‑long consolidation range (highlighted) still favors an eventual continuation higher as long as price holds above the 24,300 region.
Momentum indicators offer a mixed but constructive signal. MACD is flattening near the zero line, implying a lack of strong trend direction, while Stochastics is curling higher from oversold territory, supporting a renewed upside attempt. RSI sits in the mid‑50s, indicating neutral momentum and leaving room for a breakout if buying pressure resumes. Overall, the market remains in a bullish continuation pattern, with a decisive close above 25,100 needed to unlock the next leg higher toward the 25,500 region, while a drop below 24,300 would warn of a deeper pullback.
Tariffs & Trade: Adjustments and Tensions
Several trade developments remained in focus. The White House quietly revised its fact sheet on the US–India trade agreement, softening language around India’s proposed USD 500bn US‑imports program from a “commitment” to an “intent”—a subtle yet meaningful downgrade. The reference to tariff concessions on pulses was removed.
Separately, Treasury Secretary Bessent described US–China relations as “stable but competitive,” emphasising de‑risking rather than outright decoupling. He also highlighted the need for China to rebalance given the persistent USD 1 trillion trade gap. White House commentary on the contentious US–Canada bridge dispute continued, with Trump insisting the US should “own at least 50%” of the project.
Asia-Pacific: Modest Gains Amid Thin Liquidity
Asian equity markets traded higher overnight, though upside was capped by the soft US handover and the looming US jobs report. Japanese exchanges were closed for a holiday, while other regional markets were buoyed by sector‑specific strength and supportive liquidity conditions.
- ASX 200 outperformed, led by a 5% earnings‑driven surge in Commonwealth Bank of Australia, lifting the heavyweight financial sector.
- Hang Seng and Shanghai Composite ticked higher, supported by consecutive PBoC liquidity injections and its quarterly report pledging appropriately loose monetary policy. However, mixed Chinese inflation data—CPI at 0.2% YoY, below expectations, and PPI still in deep deflation—curbed enthusiasm.
- US futures firmed modestly during Asian hours, helped by repositioning ahead of the NFP release.
- Regional central bank dynamics also shaped sentiment. The RBI kept rates unchanged at 5.25%, projecting a slightly higher FY26 inflation outlook but noting improving domestic demand. RBA officials reiterated concerns about persistent inflation, bolstering the AUD, which reclaimed the 0.71 handle for the first time in three years.
FX: Dollar Weakens as Focus Shifts to US Jobs
The US Dollar Index softened, pressured by weak US data and broad strength in major counterparts.
- EUR/USD reclaimed 1.19, though ECB Vice President de Guindos reiterated a lack of urgency for policy adjustments.
- GBP/USD recovered mildly but remained range‑bound near 1.37 amid UK political uncertainty.
- USD/JPY extended post‑election declines as markets bet on faster BoJ normalisation following PM Takaichi’s sweeping mandate.
- AUD/USD strength reflected both risk appetite and RBA hawkishness.
PBoC again guided the yuan stronger, setting the midpoint at 6.9438 versus expectations for 6.9109.
Rates: Bonds Hold Gains Ahead of NFP
US 10‑year Treasury futures hovered near recent highs after soft macro data drove a bull‑steepening move. Cash trading was limited due to the Tokyo holiday. European bonds tracked global peers, though upside was capped ahead of German supply. JGB futures recovered after Monday’s election-driven decline.
Commodities: Oil Rebounds, Gold Holds Above $5,000
Oil prices advanced modestly after Monday’s drop, though gains were limited by the 13.4 million‑barrel crude inventory build reported by private data providers. Geopolitical risk remains elevated: President Trump said he is considering sending a second aircraft carrier to the Middle East if Iran talks falter.
Gold edged higher and held above $5,000/oz, supported by a softer USD and haven demand. Copper traded in tight ranges ahead of the NFP print; production figures from Chile showed double‑digit YoY declines at major mines (Collahuasi –12.1%, Escondida –16.5%).
Crypto: Soft Drift Continues
Bitcoin slipped back below $68,000, extending a series of incremental declines. Crypto market positioning remains cautious ahead of US macro data and amid renewed regulatory tightening signals.
Geopolitics: Tense but Contained
In the Middle East, the US signaled cautious optimism as Iran “wants to make a deal,” according to President Trump. However, Washington is weighing more aggressive enforcement, including the possible seizure of tankers carrying Iranian oil—a move that could invite retaliation. Iran reiterated that missile issues remain off‑the‑table for now.
In Europe, Ukraine is preparing for spring elections and a referendum linked to a US‑pushed peace framework. Russian strikes triggered new Ukrainian energy outages, while the EU explores creative models to grant Kyiv early membership benefits.
-Philip Papageorgiou – Markt Analyst
--X ex Twitter: PhilipForexCom



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.

Gold Price Forecast: XAU/USD Plunges 12.4% Toward Critical Support 10 1 2026
Softer inflation has revived expectations for a Fed pause, but Friday’s payrolls could put gold’s recovery prospects to the test.


Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.