



Nasdaq 100 forecast: Chipmakers and US jobs report in focus
Today looks to be the most important of the week for much of the financial markets. The US dollar eased lower amid potential intervention by Japan, while US stock futures traded mixed with ahead of today’s closely watched non-farm payrolls report. Investors were reluctant to take on fresh risk before one of the month’s most important economic releases, and ahead of a long weekend for US investors.
Share this:
Today looks to be the most important of the week for much of the financial markets. The US dollar eased lower amid potential intervention by Japan, while US stock futures traded mixed with ahead of today’s closely watched non-farm payrolls report. Investors were reluctant to take on fresh risk before one of the month’s most important economic releases, and ahead of a long weekend for US investors. The labour market figures could shape expectations for Federal Reserve policy over the coming months. Meanwhile the technology sector remains under pressure after another bout of selling in semiconductor shares, putting the Nasdaq 100 forecast into focus.
Labour market data takes centre stage
Markets received little additional guidance from Federal Reserve Chair Kevin Warsh during his appearance at the ECB Forum in Sintra yesterday. As expected, he avoided offering any clues on the likely direction of interest rates, preferring instead to reinforce the Fed’s data-dependent approach.
That leaves today’s June non-farm payrolls report firmly in the spotlight. Consensus forecasts suggest the US economy created around 115,000 jobs during June, down from 172,000 in May. However, economists have consistently underestimated payroll growth in recent months, with employment figures repeatedly surprising to the upside.
Warsh’s refusal to validate or challenge current market pricing effectively leaves investors to interpret incoming data for themselves. Rather than attempting to steer expectations through forward guidance, the Fed appears content to let economic releases dictate the narrative before policymakers meet again. That places even greater importance on today’s payroll figures.
How will the market react to NFP?
The stock market reaction to the NFP data may not be straightforward. A report broadly in line with expectations would likely reinforce hopes of a resilient economy without dramatically altering interest rate expectations, arguably the most favourable outcome for equities. Meanwhile, a significantly stronger report could reignite concerns that the Fed may need to tighten policy sooner than expected, pushing Treasury yields higher and weighing on risk assets. Conversely, a massively disappointing employment print would revive fears that economic momentum is fading, which could also undermine investor confidence.
With the Independence Day holiday approaching, traders may also be inclined to reduce exposure later in the session, particularly if volatility picks up following the payroll release.
Semiconductor sell-off rattles technology sector
Yesterday, the new month and quarter began. It was an uncomfortable start for technology investors, with semiconductor stocks leading declines across Wall Street. Micron Technology and SanDisk both suffered double-digit losses, while heavyweight names including Nvidia and Broadcom also finished firmly in negative territory. Although the declines among the largest companies were more measured, the weakness was broad enough to drag the Nasdaq lower.
Selling pressure then spread into Asian markets overnight. South Korea’s technology-heavy market came under particular strain as Samsung Electronics and SK Hynix both posted sharp declines, pulling the Kospi lower given their substantial weighting within the benchmark. Similar weakness was also evident across Chinese and Hong Kong technology shares as investors reassessed sentiment towards the sector.
While one poor session hardly changes the longer-term picture, it does highlight how sensitive technology stocks have become after an extended period of exceptional gains.
AI enthusiasm faces a reality check
The latest weakness reflects more than simple profit-taking. Investors are increasingly questioning whether current valuations across parts of the AI supply chain fully reflect the commercial returns that have yet to materialise. After months of relentless optimism, markets appear to be placing greater emphasis on execution rather than future potential.
Recent corporate announcements have added to those concerns. Apple’s decision last week, for example, to raise prices on several products highlighted the impact that higher semiconductor costs are beginning to have across the technology industry. As companies continue investing heavily in AI infrastructure, the cost of processors, data centres and energy consumption is becoming increasingly difficult to ignore.
The scale of investment remains extraordinary. Technology companies continue to commit hundreds of billions of dollars towards AI development, yet meaningful earnings growth has not kept pace. Investors have so far been prepared to look beyond near-term profitability in anticipation of future gains, but patience may become harder to sustain if returns fail to emerge.
Unlike previous technology cycles, AI requires enormous upfront spending before businesses can generate meaningful cash flows. That creates greater sensitivity to financing costs and leaves companies more exposed if economic conditions become less supportive.
Higher borrowing costs complicate the Nasdaq 100 forecast
Expectations that US interest rates could remain elevated have strengthened following recent Fed commentary, even without explicit policy signals from Warsh. Should incoming data continue to demonstrate economic resilience, investors may increasingly price out the prospect of near-term policy easing.
That matters for AI-related companies because many of their expansion plans rely on sustained capital investment. Higher borrowing costs raise the hurdle for future projects and reduce the present value of expected earnings, particularly for growth companies whose valuations depend heavily on future cash flows.
Taken together, elevated valuations, rising infrastructure costs and tighter monetary conditions have prompted investors to reassess one of this year’s strongest market themes. The long-term opportunity surrounding artificial intelligence remains substantial, but markets are becoming less willing to ignore the growing gap between investment spending and realised profits.
Technical analysis: Nasdaq 100 forecast and levels to watch
From a technical analysis perspective, the Nasdaq 100 forecast is not entirely bearish just yet. The index remains in a consolidation phase rather than showing clear signs of a broader correction. The 29,600 level continues to act as an important pivot, with buyers and sellers battling for control around that area.
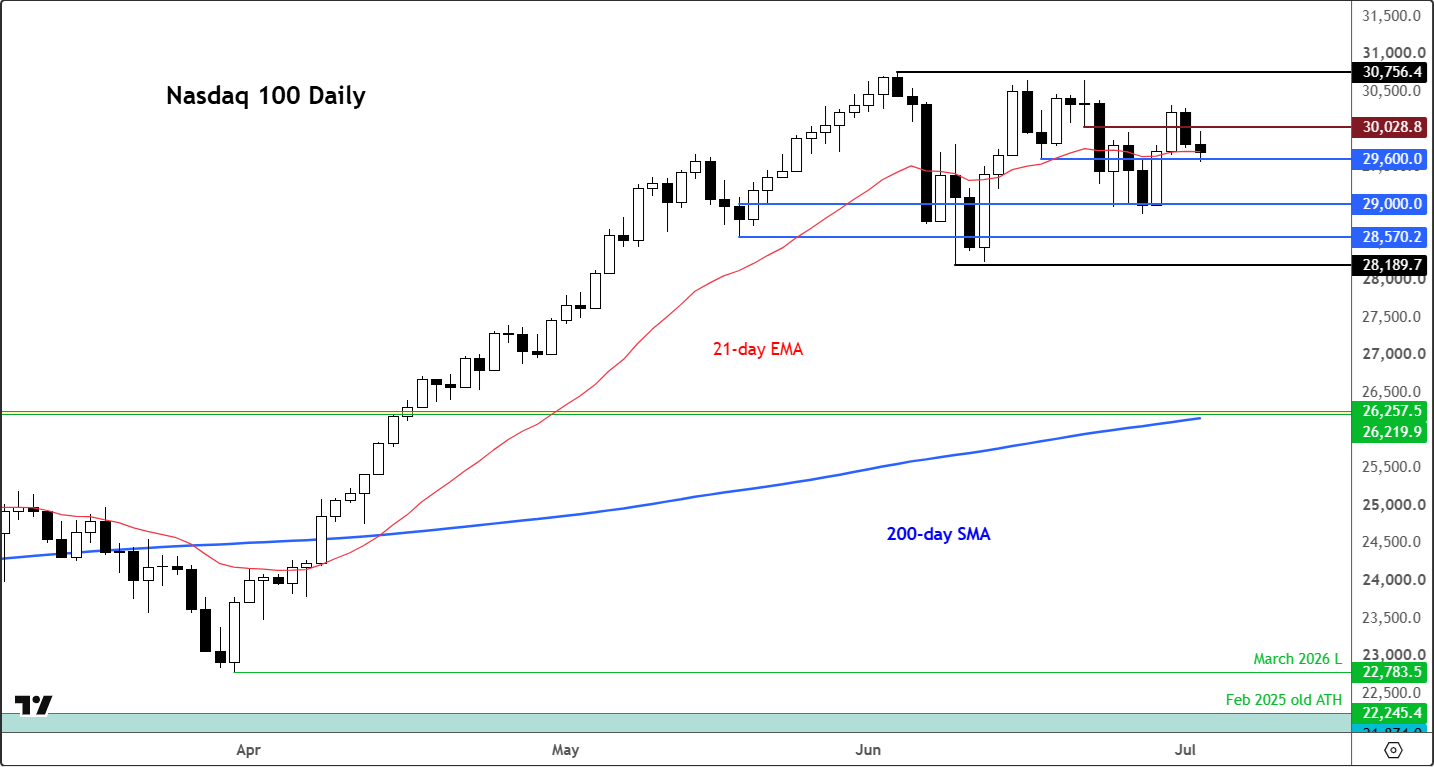
Although recent price action has produced a sequence of lower highs, our US Tech 100 index, which is based on the Nasdaq 100 futures, remains above its 21-day exponential moving average, while key support levels also remain intact.
Therefore, the broader uptrend has not been broken – for now. However, seasonal profit-taking, combined with growing uncertainty surrounding AI valuations, could encourage additional volatility over the coming weeks.
The next support below 29,000, is at 29,000, followed by 28,570. The June swing low around 28,190 remains the key technical floor. A decisive break beneath that level would mark a deterioration in the medium-term outlook and could trigger a deeper corrective move.
On the upside, resistance is located around the psychological level of 30,000, followed by 30,500. A move above that barrier would bring the record high near 30,756 back into focus.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.


Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.


GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.