



Nasdaq 100 Forecast: “Magnificent Seven” Q2 2025 Earnings Preview
The Nasdaq 100 remains in a bullish channel and could target 24,000 or 25,000 if Big Tech stocks can deliver on earnings expectations.
Share this:
Nasdaq 100 Key Points
- With over $400B in AI and datacenter investments projected this year, the Magnificent Seven continue to drive the digital infrastructure boom…though any cap-ex slowdown could spark a sharp rerating.
- Despite pockets of consumer weakness, especially for Apple and Tesla, enterprise tech spending and digital advertising remain robust, setting the stage for another bifurcated earnings season.
- The Nasdaq 100 remains in a bullish channel and could target 24,000 or 25,000 if Big Tech stocks can deliver on earnings expectations.
Magnificent Seven Earnings Preview – MSFT, AAPL, GOOG, AMZN, NVDA, META, TSLA
Throughout most of the last few years, the “Magnificent Seven” big technology stocks (Microsoft, Apple, Nvidia, Alphabet/Google, Meta/Facebook, and Tesla) broadly moved as a monolithic unit, rising and falling in unison with the (mostly) ups and (fewer) downs of the broader market, albeit to differing extents
Since flipping the calendar to 2025, the individual differences between these massive entities have become more stark, with growth laggards like Apple and Tesla falling despite generally bullish conditions and standouts like Nvidia and Microsoft gaining more than 20% year-to-date:
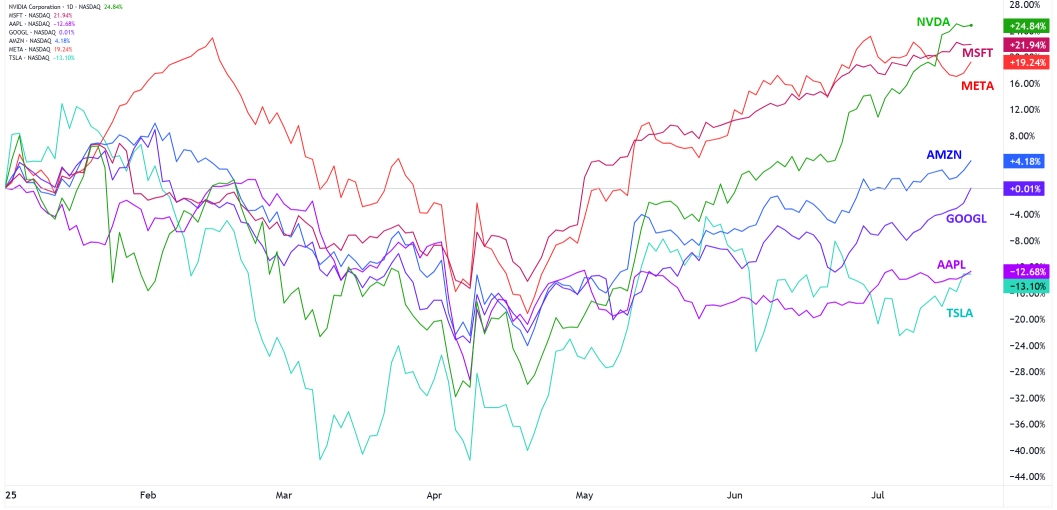 Source: StoneX, TradingView
Each of the Magnificent Seven stocks faces its own set of opportunities and challenges, but some common themes to monitor are the health of the consumer and timing of any interest rate cuts from the Federal Reserve, as well as the impact of AI and growth of augmented/virtual reality devices.
Magnificent 7 Earnings “Cheat Sheet”
|
COMPANY |
Report date / time |
CONSENSUS EPS ESTIMATE* |
Y/Y REVENUE DRIVERS |
TOP ISSUES |
|
Tesla (TSLA) |
Wed 23 Jul after - close |
$0.44 |
-13% unit vols, weaker price/mix |
Auto-gross-margin trough? ˑ Robo-taxi roadmap ˑ China demand & tariffs |
|
Alphabet (GOOGL) |
Wed 23 Jul after - close |
$2.17 |
Search & YouTube ads + low-teens Cloud |
Gen-AI search monetisation ˑ TAC inflation ˑ EU DMA impact |
|
Microsoft (MSFT) |
Wed 30 Jul after - close |
$3.38 |
Azure +13% cc, O365 +11% |
AI-attached Azure growth, Copilot seat uptake, Activision synergies |
|
Meta (META) |
Wed 30 Jul after - close |
$5.84 |
Re-accelerating ad spend (retail & gaming) |
AI-inference cap-ex ($35-40 bn run-rate) ˑ Reels monetisation |
|
Amazon (AMZN) |
Thu 31 Jul after - close |
$1.31 |
AWS +23%, Retail +8% |
Gen-AI services attach, ad-net high-teens growth, fulfilment cost leverage |
|
Apple (AAPL) |
Thu 31 Jul after - close |
$1.42 |
iPhone rebound in China, Services +12% |
Gross-margin slip from discounting, visionOS / “Apple Intelligence” clues |
|
NVIDIA (NVDA) |
Wed 27 Aug after - close |
$1.00 (post-split†) |
Data-centre +80%, gaming normalises |
Supply vs. Blackwell demand; China export licences; buy-back cadence |
*EPS consensus = current Zacks/FactSet or equivalent public-source average unless otherwise noted.
†10-for-1 split effective 9 Jun 2025.
Key Magnificent Seven Themes to Watch This Earnings Season
- AI Infrastructure Tidal Wave
Wall Street’s biggest storyline remains the sheer scale-up in datacenter spending. Bank of America now projects the four “hyperscalers” (Amazon Web Services (AWS), Microsoft Azure, Google Cloud Platform (under Alphabet/Google) and Meta Platforms) will plough about $414 billion into AI and general datacenter cap-ex in 2025, rising to roughly $432 billion in 2026—double the 2023 run-rate. Gartner’s fresh IT-budget survey corroborates the trend, flagging a 42% jump in datacenter outlays next year, far outpacing every other line-item in corporate tech budgets.
With Nvidia still effectively sold-out through its Blackwell cycle and AMD, Broadcom and TSMC signalling back-end bottlenecks well into 2026, any management hints of a “pause” in rack installs could ricochet across the entire Mag-7 narrative.
- Ad Market Resilience Amidst Macroeconomic Wobbles
Advertising demand continues to shrug off the stop-start economy. GroupM estimates that global ad revenue will surpass the $1 trillion mark this year and grow another 7.7% in 2025, with digital formats capturing nearly three-quarters of the total.
The combination of AI-driven targeting tools, retail-media momentum and Shorts/Reels video inventory is letting the platforms raise impressions even as some brands edge budgets lower. Investors will therefore focus less on Q2 prints and more on color around Q4 holiday bookings, where any abrupt pull-back could force the first material guidance resets in six quarters.
- Consumer Wallets vs. Enterprise War Chests
The gap between household and corporate spending power is becoming glaring. In China, a bellwether for discretionary tech demand, iPhone shipments fell 9% year-on-year in Q1 2025, making Apple the only top five vendor to shrink in the world’s second-largest smartphone market.
On the auto side, Tesla’s automotive gross margin has already slid from 16% in early 2024 to about 13.6% in Q4, with UBS warning it could sink near 10% in Q1 2025 as price cuts persist. By contrast, CIOs keep the checkbook open: Gartner forecasts overall IT spending to climb by 7.9% in 2025, propelled largely by AI-optimized infrastructure budgets.
Expect earnings calls to paint a bifurcated picture—consumer-facing names defending volumes and discounting, while enterprise-exposed cloud providers boast healthy double-digit growth.
- Policy & Regulation Watch
The legal and political backdrop is as busy as the P&L sheets. The Department of Justice has moved into the remedies phase of its search-antitrust win against Google, signaling possible structural changes to how the company bundles advertising and search services. In Europe, Apple is appealing a €500 million fine under the Digital Markets Act even as it tweaks App-Store commission rules—investors will parse any further concession language.
Across the Atlantic, a federal judge last week postponed Texas’s $100 billion ad-tech case against Google until a related Virginia verdict is final, potentially pushing headline risk into 2026.
On the trade front, Nvidia is rolling out export-compliant H20 and RTX 6000D GPUs to keep Chinese revenues flowing amid shifting US licensing rules, underscoring how supply-chain workarounds are now part of the earnings script.
Finally, Washington’s 100% tariff on Chinese EV imports remains a wildcard for Tesla and, indirectly, Apple’s China-centric supply chain if retaliatory measures materialize later this year.
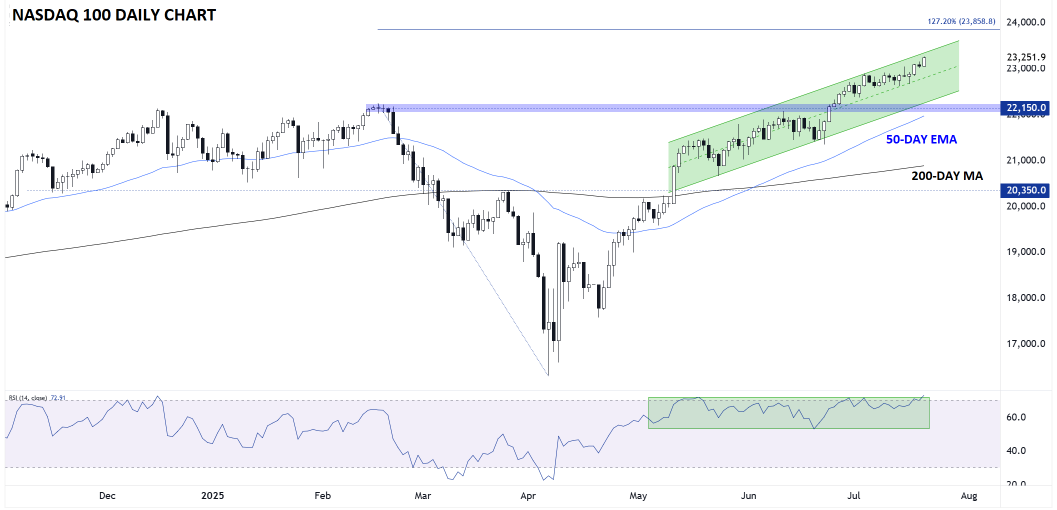
Nasdaq 100 Technical Analysis – NDX Daily Chart
Source: TradingView, StoneX
As the chart above shows, the Nasdaq 100 has more than recovered from its Q1 swoon to trade at fresh record highs, despite the mixed performance of the technology behemoths so far this year.
More immediately, the index is trending consistently higher within a bullish channel, keeping the technical bias tilted toward the topside as long as this season’s earnings results at least meet analyst expectations. To the topside, the next level of resistance to watch is the 127% Fibonacci extension of the Q1 drop near 24,000, followed by the round 25,000 handle after that.
However, if weak earnings reports start to accumulate and the index breaks down from its channel to fall below the 50-day EMA, a deeper retracement toward the 200-day MA near 21,000 could be in the cards.
-- Written by Matt Weller, Global Head of Research
Follow Matt on Twitter: @MWellerFX
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.