


Nasdaq 100 Forecast: NDX falls in nervous trade ahead of Trump's deadline for Iran
US stocks are heading for a lower open on Tuesday as investors look nervously ahead to President Trump’s 8 PM ET deadline for Iran to reopen the Strait of Hormuz.
Share this:
US futures
Dow futures -0.36%, S&P futures -0.64% & Nasdaq futures -0.65%
In Europe
FTSE -0.35% & DAX -0.5%
- US stocks edge lower in cautious trade
- Trump set an 8 PM ET deadline for Iran to agree to a deal and open the Strait
- Broadcom jumps after a deal with Google
- Oil rises on supply worries


US stocks set for lower open ahead of Iran deadline
US stocks are heading for a lower open on Tuesday as investors look nervously ahead to President Trump’s deadline for Iran to reopen the Strait of Hormuz.
The deadline, set for 8:00 PM ET (midnight GMT), comes as Tehran has so far refused to comply. Trump has warned that the US could target Iranian power plants and bridges if the Strait is not reopened, although he has also suggested that negotiations may still be ongoing.
Markets are increasingly concerned about the risk of escalation, which could send oil prices sharply higher and have broad implications across financial markets.
At the same time, any sign of a climbdown from either Washington or Tehran could trigger a sharp relief rally in equities, alongside lower energy prices.
Global markets have already come under pressure over the past six weeks amid the Middle East conflict, rising oil prices, and growing concerns over the inflationary impact.
This week’s US inflation data (March CPI) will be key in assessing how much of the recent surge in energy prices is feeding through into consumer prices — a development that could further complicate the outlook for the Federal Reserve, which is no longer expected to cut rates this year.
Corporate news
- Broadcom is rising around 4% premarket after announcing a long-term agreement with Google to develop and supply custom AI chips. The deal reinforces Broadcom’s position as a key partner in powering advanced AI infrastructure.
- Energy stocks are in focus, with Exxon Mobil and Chevron moving higher as oil prices remain elevated above $100 per barrel.
- Healthcare stocks are also gaining after the Centres for Medicare & Medicaid Services finalised payment increases for privately run Medicare Advantage plans.
Nasdaq – technical analysis
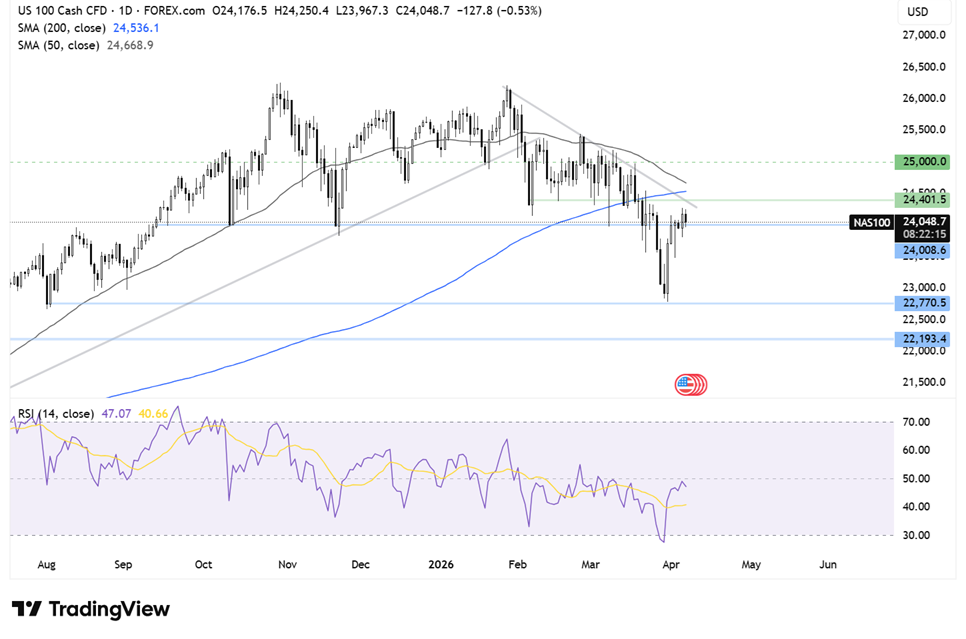
After breaking below the 200-day SMA, the Nasdaq found support around 22,800 and has since rebounded. The price has risen above resistance near 24,000, which aligns with the October–November lows, exposing 24,400 the falling trendline resistance and the horizontal resistance. Above here, 24,500 (200-day SMA) comes into focus. A break above this zone would improve the near-term outlook and bring 25,000 into focus. On the downside, a move back below 24,000 would shift attention back to 22,800, the recent low.
FX markets – USD falls, GBP/USD rises
The US dollar is easing, giving back earlier gains as investors remain cautious ahead of Trump’s deadline. The softer dollar may reflect some optimism that a deal could still be reached.
EUR/USD is rising despite weak eurozone data. The services PMI fell to 50.2 in March (from 51.9), marking a 10-month low, as demand deteriorated and input prices rose — a stagflationary signal.
GBP/USD is also rising on dollar weakness, despite a downward revision in UK data. The services PMI fell to 50.5 (from 53.9), while the composite PMI was revised to 50.3. Notably, input costs surged, highlighting growing inflation pressures.
Oil remains elevated on supply risks
Oil prices remain elevated, trading around $110 per barrel, after pulling back from earlier highs near $116.50.
Markets remain focused on the Strait of Hormuz, through which roughly 20% of global oil supply transits.
Failure to reopen the Strait on today’s deadline could lead to further attacks on Iranian energy infrastructure, exacerbating supply disruptions. Exports from several Gulf producers have already been constrained, with storage limits being reached due to restricted flows.
Even in the event of de-escalation, the recovery in supply is likely to be gradual, meaning oil prices could remain elevated for some time.
Meanwhile, the UN Security Council is expected to vote on a resolution aimed at protecting commercial shipping through the Strait. However, the proposal has been significantly diluted, limiting its immediate impact.


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

DAX Tests 26,000 as Markets Await AMD and US Election Results
The DAX remains close to 26,000 points after extending its recovery, but the market's attention is shifting away from geopolitics and back toward earnings, economic data and US politics. Reports from Bayer, Lufthansa and Fresenius Medical Care highlight a market increasingly rewarding profit growth while punishing weak guidance. With US midterm elections, JOLTS job openings and AMD earnings on today's agenda, the next move in equities may depend less on technicals and more on whether earnings and economic data justify current valuations.


US Midterm Forecast: The Key Risks for Traders to Watch Through the US Elections
Prediction markets are pricing in nearly 75% odds of a Democratic sweep in this week’s US midterm elections, a development that would result in a split from the single party Republican rule of the past two years - what will it mean for markets?


Nasdaq 100 Forecast: NDX rebounds as oil prices fall and ahead of Apple earnings
U.S. stock indices are moving higher on Monday as tech and AI-related stocks steady following a shocking October. The mood remains cautious following the AI wobble, with more tech earnings due this week, U.S. midterm elections and a full U.S. economic data calendar.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.