



DAX Tests 26,000 as Markets Await AMD and US Election Results
The DAX remains close to 26,000 points after extending its recovery, but the market's attention is shifting away from geopolitics and back toward earnings, economic data and US politics. Reports from Bayer, Lufthansa and Fresenius Medical Care highlight a market increasingly rewarding profit growth while punishing weak guidance. With US midterm elections, JOLTS job openings and AMD earnings on today's agenda, the next move in equities may depend less on technicals and more on whether earnings and economic data justify current valuations.
Share this:
EU Market Brief | Tuesday, 3 November 2026
1. DAX 40: Intraday weakness challenges the broader recovery
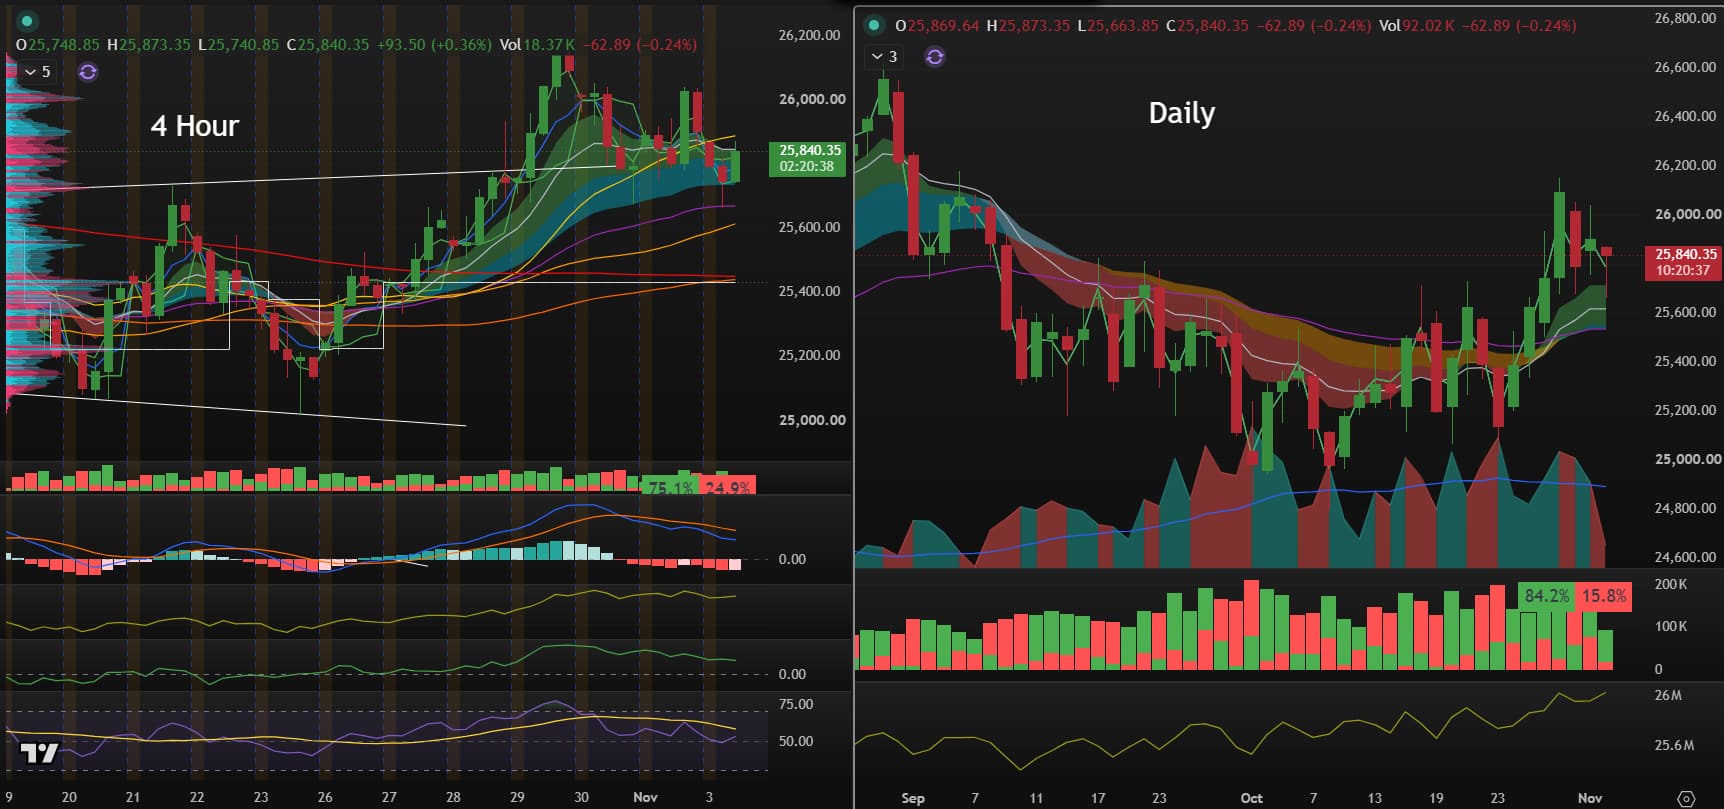
The DAX closed Monday at 25,983, gaining 0.64%, extending its recovery alongside broader European equities. However, the positive momentum has weakened overnight. The index was trading around 25,842 in the latest available snapshot.
Technically, the picture is mixed. The daily chart remains bullish, with the index trading above its 20, 50, 100 & 200-EMAs, around 25,460 to 25,590. The daily RSI is near 56 and the MACD is positive indicating that the broader recovery remains intact. However, the shorter-term 4 hour picture has turned bearish, with the index trading below its intraday pivot at 25,981.
Immediate support is located at 25,670 (EMA 34), followed by 25,620 (EMA 50) and 25,440 (EMA 20). On the upside, the DAX needs to reclaim 25,981 to improve the intraday outlook, with resistance at 26,119 and 26,201. A sustained break above these levels would reopen the path towards the ATH at 26,600.
2. Corporate movers
European corporate results are producing a mixed reaction, with investors rewarding companies delivering stronger profitability and improved guidance while penalising those lowering expectations.
• Bayer: Shares are trading approximately 3.7% higher after adjusted EBITDA of €1.62bn exceeded expectations of €1.42bn. The company raised its full-year EBITDA guidance, supported by stronger pharmaceutical performance.
• Fresenius Medical Care: Shares are trading 1.7% higher. Quarterly revenue and operating profit beat expectations, the company narrowed its full-year operating income outlook however.
• Zalando: Shares are trading 1.7% lower despite slightly beating revenue and adjusted EBIT estimates. The company maintained its full-year guidance, but investors are cautious about the outlook for consumer demand.
• Hugo Boss: Shares are trading 0.9% lower after the company cut its full-year sales and EBIT forecasts, reflecting weaker consumer demand and higher technology-related depreciation costs.
• Lufthansa: Shares are trading 3.5% higher. Quarterly revenue and earnings exceeded expectations, but the airline reduced its full-year adjusted EBIT forecast to €1.7–2.0bn, citing higher fuel costs.
• Evonik: Trading 1.25% higher. Evonik delivered stronger-than-expected quarterly results and expressed confidence in achieving the upper half of its full-year EBITDA guidance.
• Schaeffler: Trading 2.68% lower although confirming its full-year guidance but announced plans to cut 3,460 jobs in Europe and close four German sites.
Outside Germany, Shell agreed to sell its North West Shelf stake for $1.45bn.
3. Geopolitics: Iran tensions, oil volatility and US midterms
President Trump has claimed that the US has defeated Iran and suggested that further military action could follow. Reports of US strikes on Iran’s Qeshm Island have complicated hopes for diplomatic progress, although markets are still looking for signs that negotiations could eventually reduce tensions.
Therefore Crude Oil prices fell more than 7% on Monday amid renewed optimism surrounding diplomacy, before recovering modestly. Brent was last indicated around $105.25 per barrel, up approximately 0.5%.
US midterm elections take place today, with control of Congress at stake. Polls favour Democrats in the House, while the Senate remains more uncertain. Investors are looking at Treasury yields, the US dollar, defence and clean-energy stocks for potential reactions. The election adds another layer of uncertainty to markets already unsettled by technology-sector weakness.
In Asia, the MSCI Asia-Pacific index excluding Japan fell 1.4%, with South Korea’s KOSPI declining as much as 4.1% and Taiwan’s market falling 3.3%. Concerns about the profitability of AI investment remain central to the technology sell-off.
4. Events and earnings: Today and tomorrow
The focus today is firmly on US politics, labour-market data and the technology earnings cycle. Tomorrow brings another important batch of economic releases and semiconductor results.
3. Geopolitics: Iran tensions, oil volatility and US midterms
President Trump has claimed that the US has defeated Iran and suggested that further military action could follow. Reports of US strikes on Iran’s Qeshm Island have complicated hopes for diplomatic progress, although markets are still looking for signs that negotiations could eventually reduce tensions.
Therefore Crude Oil prices fell more than 7% on Monday amid renewed optimism surrounding diplomacy, before recovering modestly. Brent was last indicated around $105.25 per barrel, up approximately 0.5%.
US midterm elections take place today, with control of Congress at stake. Polls favour Democrats in the House, while the Senate remains more uncertain. Investors are looking at Treasury yields, the US dollar, defence and clean-energy stocks for potential reactions. The election adds another layer of uncertainty to markets already unsettled by technology-sector weakness.
In Asia, the MSCI Asia-Pacific index excluding Japan fell 1.4%, with South Korea’s KOSPI declining as much as 4.1% and Taiwan’s market falling 3.3%. Concerns about the profitability of AI investment remain central to the technology sell-off.
4. Events and earnings: Today and tomorrow
The focus today is firmly on US politics, labour-market data and the technology earnings cycle. Tomorrow brings another important batch of economic releases and semiconductor results.
|
Date |
Key economic and political events |
Notable earnings |
|
Tuesday, 3 November |
US midterm elections; US JOLTS job openings (September); RBA decision (already raised rates by 25bps to 4.85%) |
AMD, Pfizer, Shopify, Eaton, Amgen, Arista Networks, Super Micro Computer, Ferrari, Bayer, Intesa Sanpaolo |
|
Wednesday, 4 November |
Eurozone flash CPI; Riksbank rate decision; US ADP employment; US trade balance; US ISM Services PMI; US Treasury quarterly refunding announcement |
Qualcomm, Arm, Uber, Novo Nordisk, McDonald’s, CVS Health, AppLovin, Datadog, BMW |
Looking further ahead: Thursday brings the Bank of England’s policy decision, with markets expecting a rate increase to 4.0%, alongside the Norges Bank decision. Friday’s US October employment report is likely to be the week’s most important economic release, potentially influencing expectations for the Federal Reserve’s next policy move.
Around 127–138 S&P 500 companies are scheduled to report this week, depending on the earnings calendar used. AMD is particularly important today: its results and forward guidance will provide another indication of whether demand for AI accelerators can justify the sector’s substantial investment expectations.
Trade safely,
By Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Dollar Tests a Cliff’s Edge as Gold Challenges $3,870 Support
Dollar, Gold Outlook: The dollar is testing a critical 10-month trendline, while gold is challenging its 2026 low and support near $3,870. The U.S. elections, nonfarm payrolls and bond yields are key volatility catalysts to watch this week.

DAX Tests 26,000 as Markets Await AMD and US Election Results
The DAX remains close to 26,000 points after extending its recovery, but the market's attention is shifting away from geopolitics and back toward earnings, economic data and US politics. Reports from Bayer, Lufthansa and Fresenius Medical Care highlight a market increasingly rewarding profit growth while punishing weak guidance. With US midterm elections, JOLTS job openings and AMD earnings on today's agenda, the next move in equities may depend less on technicals and more on whether earnings and economic data justify current valuations.

GBP/USD, DAX Forecast: Two trades to watch
GBP/USD holds above 1.34 with US midterms and BoE in focus. DAX slips as the global tech selloff continues.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.