



NZDUSD surpasses 70 cents as the uptrend continues
The pair has not broken 0.70 since June of 2018.
Share this:
The US Dollar was bearish against all of its major pairs on Tuesday. On the US economic data front, the Conference Board's Consumer Confidence Index fell to 96.1 on month in November (98.0 expected), from a revised 101.4 in October.
Wednesday will be a busy day regarding U.S. Eco data ahead of the Thanksgiving holiday Thursday where U.S. markets will be closed.
We can expect the Mortgage Bankers Association's Mortgage Applications data for the week ending November 20th.
Initial Jobless Claims for the week ending November 21st are expected to fall to 730K, from 742K in the week before. Continuing Claims for the week ending November 14th are expected to decline to 6,000K, from 6,372K in the prior week.
Wholesale Inventories for the October preliminary reading are expected to rise 0.4% on month, in line with the September final reading.
GDP for the third quarter second reading is expected to remain at +33.1% on quarter, in line with the third quarter advanced reading. Durable Goods Orders for the October preliminary reading are expected to increase 0.9% on month, compared to +1.9% in the September final reading.
Personal Income for October is expected to be unchanged on month, compared to +0.9% in September. Personal Spending for October is expected to rise 0.4% on month, compared to +1.4% in September.
The University of Michigan's Consumer Sentiment Index for the November final reading is expected to remain at 77.0 on month, in line with the November preliminary reading. New Home Sales for October are expected to rise to 975K on month, from 959K in September.
Finally, the Federal Open Market Committee's Meeting Minutes are expected.
The Euro was bullish against most of its major pairs with the exception of the NZD, AUD and CAD. In Europe, the German Federal Statistical Office has posted final readings of 3Q GDP at +8.5% (vs +8.2% on quarter expected). Germany's IFO Business has released November Climate Index at 90.7 (vs 90.3 expected) and Expectations Index at 91.5 (vs 93.5 expected). Also, France's INSEE has reported November indicators on business confidence at 79 (vs 84 expected) and manufacturing confidence at 92 (vs 91 expected).
The Australian dollar was bullish against all of its major pairs.
Looking at active pairs, the NZDUSD broke above our first resistance target as the pair continues its uptrend. On a daily chart, look for the 20-day moving average to act as support. The next major levels to watch on the upside are 0.7065 and 0.7150.

Source: GAIN Capital, TradingView
Wednesday will be a busy day regarding U.S. Eco data ahead of the Thanksgiving holiday Thursday where U.S. markets will be closed.
We can expect the Mortgage Bankers Association's Mortgage Applications data for the week ending November 20th.
Initial Jobless Claims for the week ending November 21st are expected to fall to 730K, from 742K in the week before. Continuing Claims for the week ending November 14th are expected to decline to 6,000K, from 6,372K in the prior week.
Wholesale Inventories for the October preliminary reading are expected to rise 0.4% on month, in line with the September final reading.
GDP for the third quarter second reading is expected to remain at +33.1% on quarter, in line with the third quarter advanced reading. Durable Goods Orders for the October preliminary reading are expected to increase 0.9% on month, compared to +1.9% in the September final reading.
Personal Income for October is expected to be unchanged on month, compared to +0.9% in September. Personal Spending for October is expected to rise 0.4% on month, compared to +1.4% in September.
The University of Michigan's Consumer Sentiment Index for the November final reading is expected to remain at 77.0 on month, in line with the November preliminary reading. New Home Sales for October are expected to rise to 975K on month, from 959K in September.
Finally, the Federal Open Market Committee's Meeting Minutes are expected.
The Euro was bullish against most of its major pairs with the exception of the NZD, AUD and CAD. In Europe, the German Federal Statistical Office has posted final readings of 3Q GDP at +8.5% (vs +8.2% on quarter expected). Germany's IFO Business has released November Climate Index at 90.7 (vs 90.3 expected) and Expectations Index at 91.5 (vs 93.5 expected). Also, France's INSEE has reported November indicators on business confidence at 79 (vs 84 expected) and manufacturing confidence at 92 (vs 91 expected).
The Australian dollar was bullish against all of its major pairs.
Looking at active pairs, the NZDUSD broke above our first resistance target as the pair continues its uptrend. On a daily chart, look for the 20-day moving average to act as support. The next major levels to watch on the upside are 0.7065 and 0.7150.
Source: GAIN Capital, TradingView
The US Dollar was bearish against all of its major pairs on Tuesday. On the US economic data front, the Conference Board's Consumer Confidence Index fell to 96.1 on month in November (98.0 expected), from a revised 101.4 in October.
Wednesday will be a busy day regarding U.S. Eco data ahead of the Thanksgiving holiday Thursday where U.S. markets will be closed.
We can expect the Mortgage Bankers Association's Mortgage Applications data for the week ending November 20th.
Initial Jobless Claims for the week ending November 21st are expected to fall to 730K, from 742K in the week before. Continuing Claims for the week ending November 14th are expected to decline to 6,000K, from 6,372K in the prior week.
Wholesale Inventories for the October preliminary reading are expected to rise 0.4% on month, in line with the September final reading.
GDP for the third quarter second reading is expected to remain at +33.1% on quarter, in line with the third quarter advanced reading. Durable Goods Orders for the October preliminary reading are expected to increase 0.9% on month, compared to +1.9% in the September final reading.
Personal Income for October is expected to be unchanged on month, compared to +0.9% in September. Personal Spending for October is expected to rise 0.4% on month, compared to +1.4% in September.
The University of Michigan's Consumer Sentiment Index for the November final reading is expected to remain at 77.0 on month, in line with the November preliminary reading. New Home Sales for October are expected to rise to 975K on month, from 959K in September.
Finally, the Federal Open Market Committee's Meeting Minutes are expected.
The Euro was bullish against most of its major pairs with the exception of the NZD, AUD and CAD. In Europe, the German Federal Statistical Office has posted final readings of 3Q GDP at +8.5% (vs +8.2% on quarter expected). Germany's IFO Business has released November Climate Index at 90.7 (vs 90.3 expected) and Expectations Index at 91.5 (vs 93.5 expected). Also, France's INSEE has reported November indicators on business confidence at 79 (vs 84 expected) and manufacturing confidence at 92 (vs 91 expected).
The Australian dollar was bullish against all of its major pairs.
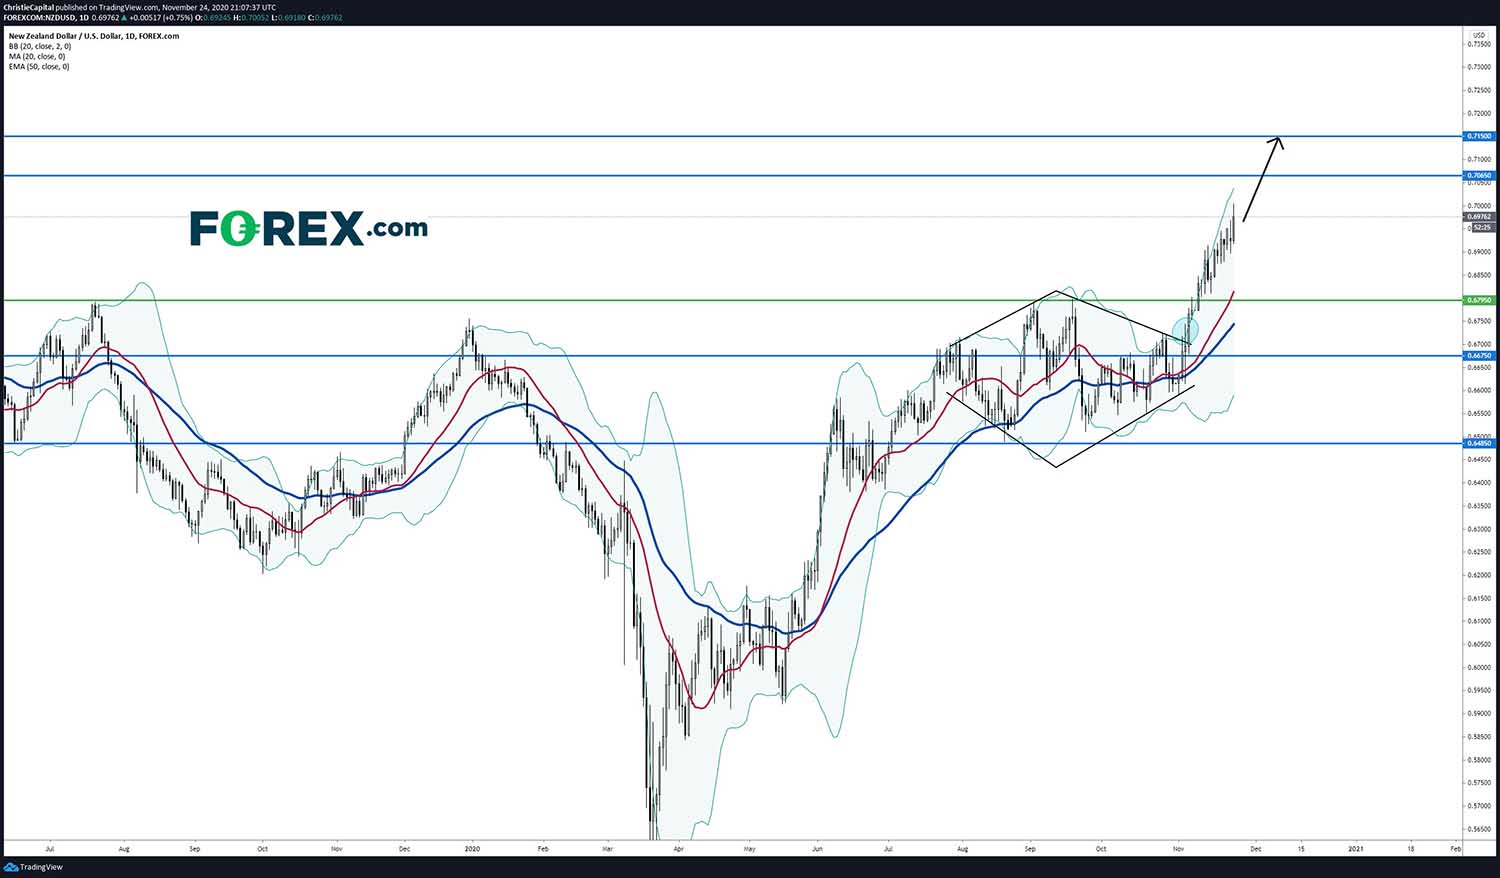
Looking at active pairs, the NZDUSD broke above our first resistance target as the pair continues its uptrend. On a daily chart, look for the 20-day moving average to act as support. The next major levels to watch on the upside are 0.7065 and 0.7150.
Source: GAIN Capital, TradingView
Wednesday will be a busy day regarding U.S. Eco data ahead of the Thanksgiving holiday Thursday where U.S. markets will be closed.
We can expect the Mortgage Bankers Association's Mortgage Applications data for the week ending November 20th.
Initial Jobless Claims for the week ending November 21st are expected to fall to 730K, from 742K in the week before. Continuing Claims for the week ending November 14th are expected to decline to 6,000K, from 6,372K in the prior week.
Wholesale Inventories for the October preliminary reading are expected to rise 0.4% on month, in line with the September final reading.
GDP for the third quarter second reading is expected to remain at +33.1% on quarter, in line with the third quarter advanced reading. Durable Goods Orders for the October preliminary reading are expected to increase 0.9% on month, compared to +1.9% in the September final reading.
Personal Income for October is expected to be unchanged on month, compared to +0.9% in September. Personal Spending for October is expected to rise 0.4% on month, compared to +1.4% in September.
The University of Michigan's Consumer Sentiment Index for the November final reading is expected to remain at 77.0 on month, in line with the November preliminary reading. New Home Sales for October are expected to rise to 975K on month, from 959K in September.
Finally, the Federal Open Market Committee's Meeting Minutes are expected.
The Euro was bullish against most of its major pairs with the exception of the NZD, AUD and CAD. In Europe, the German Federal Statistical Office has posted final readings of 3Q GDP at +8.5% (vs +8.2% on quarter expected). Germany's IFO Business has released November Climate Index at 90.7 (vs 90.3 expected) and Expectations Index at 91.5 (vs 93.5 expected). Also, France's INSEE has reported November indicators on business confidence at 79 (vs 84 expected) and manufacturing confidence at 92 (vs 91 expected).
The Australian dollar was bullish against all of its major pairs.
Looking at active pairs, the NZDUSD broke above our first resistance target as the pair continues its uptrend. On a daily chart, look for the 20-day moving average to act as support. The next major levels to watch on the upside are 0.7065 and 0.7150.
Source: GAIN Capital, TradingView
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.