






Gold consolidates after recent recovery
Gold is recovering after its past sell-off but has probably rallied enough, and now needs to consolidate. True to form, silver moved before gold and by a larger percentage. US economic data last week showed a slowing labour market and reduced consumer confidence. European economic confidence is floundering, while China continues to struggle. Core inflation was below expectations but perhaps not enough to satisfy the Fed.
Share this:
Gold is recovering after its past sell-off but has probably rallied enough, and now needs to consolidate. True to form, silver moved before gold and by a larger percentage. US economic data last week showed a slowing labor market and reduced consumer confidence. European economic confidence is floundering, while China continues to struggle. Core inflation was below expectations but perhaps not enough to satisfy the Fed.
Gold recovery
The first half of August saw gold and silver prices moving lower in the face of a stronger dollar and higher bond yields. A mid-month rally reversed this trend, continuing to the end of August. Gold gained 3.4% from $1,884 to $1,953, before correcting. This was a perfect Fibonacci 38.2% retracement from the high ($2,063 per ounce), posted on 5th April to the low ($1,884 per ounce), on 17th August.
Technically, gold is forming a double bottom. For this to be confirmed, spot gold would have to reach $1,990 per ounce, from $1,935 per ounce at the time of writing, setting up a short-term target of $2,097 per ounce. While technically feasible, the fundamentals suggest this is unlikely. The gold market has already seen some short covering on COMEX, spurring the rally that we have just seen – barring unforeseen exogenous shocks it doesn’t currently look as if gold will rally further.
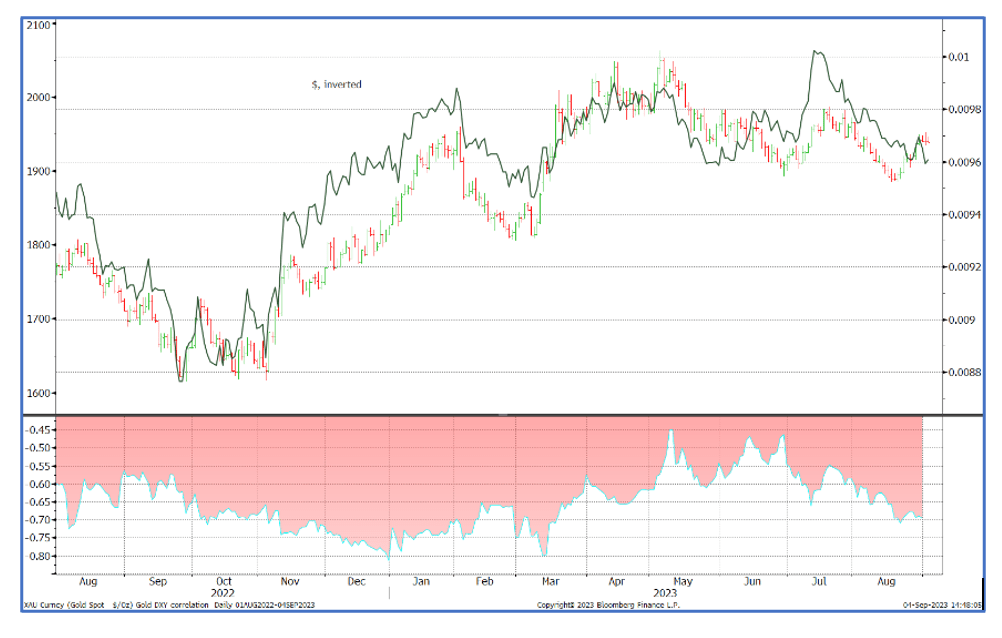
Gold versus US dollar relationship, one-year view
Source: Bloomberg, StoneX
What might take the gold price higher?
A rising gold price, driven by a flight to quality, would require a substantial drop in the US dollar, lower Treasury yields (if we were to see dire US economic data), or evidence of renewed stress in the US banking system (which remains a possibility, as highlighted by the recent credit downgrades to that sector.)
Economic data
As usual the US economy has commanded a lot of attention and a heavy raft of data hit the markets last week. The underlying tone, with faltering confidence, a slowing in the job market and PMIs still below 50 has meant that the markets are now more or less writing off the possibility of a rate hike in the FOMC meeting of 19-20 September. It will be particularly interesting to see how the dot plot projections shape up this time (this is the grid, produced once a quarter, on which each FOMC member adds a “dot” to show where they expect the fed funds target rate to be at the end of the current and following year, plus further out).
Bond markets’ Implied fed funds target rate
Source: Bloomberg
Inflation risks sill on the Fed’s mind
The Core PCE (Personal Consumption Expenditure) is a key parameter reviewed by the FOMC when it comes to framing monetary policy. While trending down, last week’s number was 4.23%, still way above the Fed’s 2% target, and a cautionary note when it comes to the outlook for rates. Whether September signifies the end of the Fed’s tightening cycle, or whether it turns out to be another “pause”, will remain data-dependent, but one thing we can be sure of is that the Fed is unlikely to be in a hurry to start cutting rates.
The Fed’s balance sheet and the core PCE
Source: Bloomberg, StoneX
Silver
Gold’s exuberant sister metal was, as usual, more volatile. Silver rallied by 12.7% in the period while gold rallied by just 3.7%. As we noted last week, silver will often move before gold because of the size of the market, and its more volatile nature. COMEX data, below, shows a sharp turnaround from a net short to a net long position in silver.
Gold/silver ratio, short-term
Source: Bloomberg, StoneX
Trading activity
ETPs
There has been tentative interest in the precious metal ETPs after recent price falls. From the spot low on 21st August, four out of ten trading days saw gold ETP fund creations at a rate of just 40%, albeit that is higher than the 30% rate over the year up to that point. That said, the period in question still resulted in a net redemption of 9.7 tonnes of gold.
- Silver ETP investors were reluctant to come back into the market, with only three days of creations since silver started its rally on the 17th August, and a net reduction of 432 tonnes in the period. Given the fact that holdings exceed 22,000 tonnes, the silver ETP position is effectively flat.
Physical investment
The latest numbers from the Commodity Futures Trading Commission (CFTC), which date to August 29th – effectively a week out of date, but still an indication – shows that the gold price rally in the week ending August 29th (to $1,938 from $1,889) was accompanied by the addition of fresh longs for gold and silver in the Managed Money sector, the first time in six weeks.
Gold
- Longs were increased by 48 tonnes, or 15%, to 375 tonnes, and shorts were reduced by 46 tonnes, or 15%, to 253 tonnes.
- Net long gold positions increased from 28 tonnes to 122 tonnes (compared to a 12month average of 150 tonnes long). This was the first net long position since mid-July.
Silver
- Outright longs gained again, following from the bullish change of the previous week, so that over the fortnight outright longs rose by 1,892 tonnes (37%) and shorts were reduced by 1,830 tonnes (30%)
- This takes the net position from a short of 44 tonnes a fortnight previously, to a net long of 1,122 tonnes (not that far from the twelve-month average of 1,386 tonnes)
Taken from analysis by Rhona O’Connell, Head of Commodity Market Analysis for EMEA & Asia, StoneX Financial Ltd.
Contact: [email protected].
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.