





UK banks earnings Q4 2021 preview BOE befuddles
UK banks have been tugged to and fro by the latest comments from the Bank of England lately...
Share this:

UK banks earnings Q4 2021 preview: BOE befuddles
Background
As we noted in our US bank earnings preview report, banks are the primary repository for excess cash and the go-to place for new loans, making them a bellwether for the health of the broad economy. Following a generally upbeat earnings season from US banks, traders will cast their eyes across the Atlantic to see if UK banks can keep the momentum going over the next two weeks.
In terms of the key sector-wide theme to watch, UK banks have been tugged to and fro by the latest comments from the Bank of England. Alarmingly, the central bank warned commercial banks to prepare for negative interest rates in the coming months, though it emphasized that policymakers hope not to resort to such dramatic measures. Further cuts to interest rates would directly reduce banks’ lending revenue.
In a seeming contradiction, the BOE also issued an optimistic 5% GDP growth forecast for the year, which implies that there may be no need for negative interest rates after all. From our perspective, the strong growth scenario may be more likely, with the UK among the world leaders in vaccine distribution and the uncertainty (though not necessarily all the disruption) of Brexit behind it.
Four UK banks in focus
Barclays PLC (BARC) – Reports 18 Feb
EPS Expectation: -$0.01
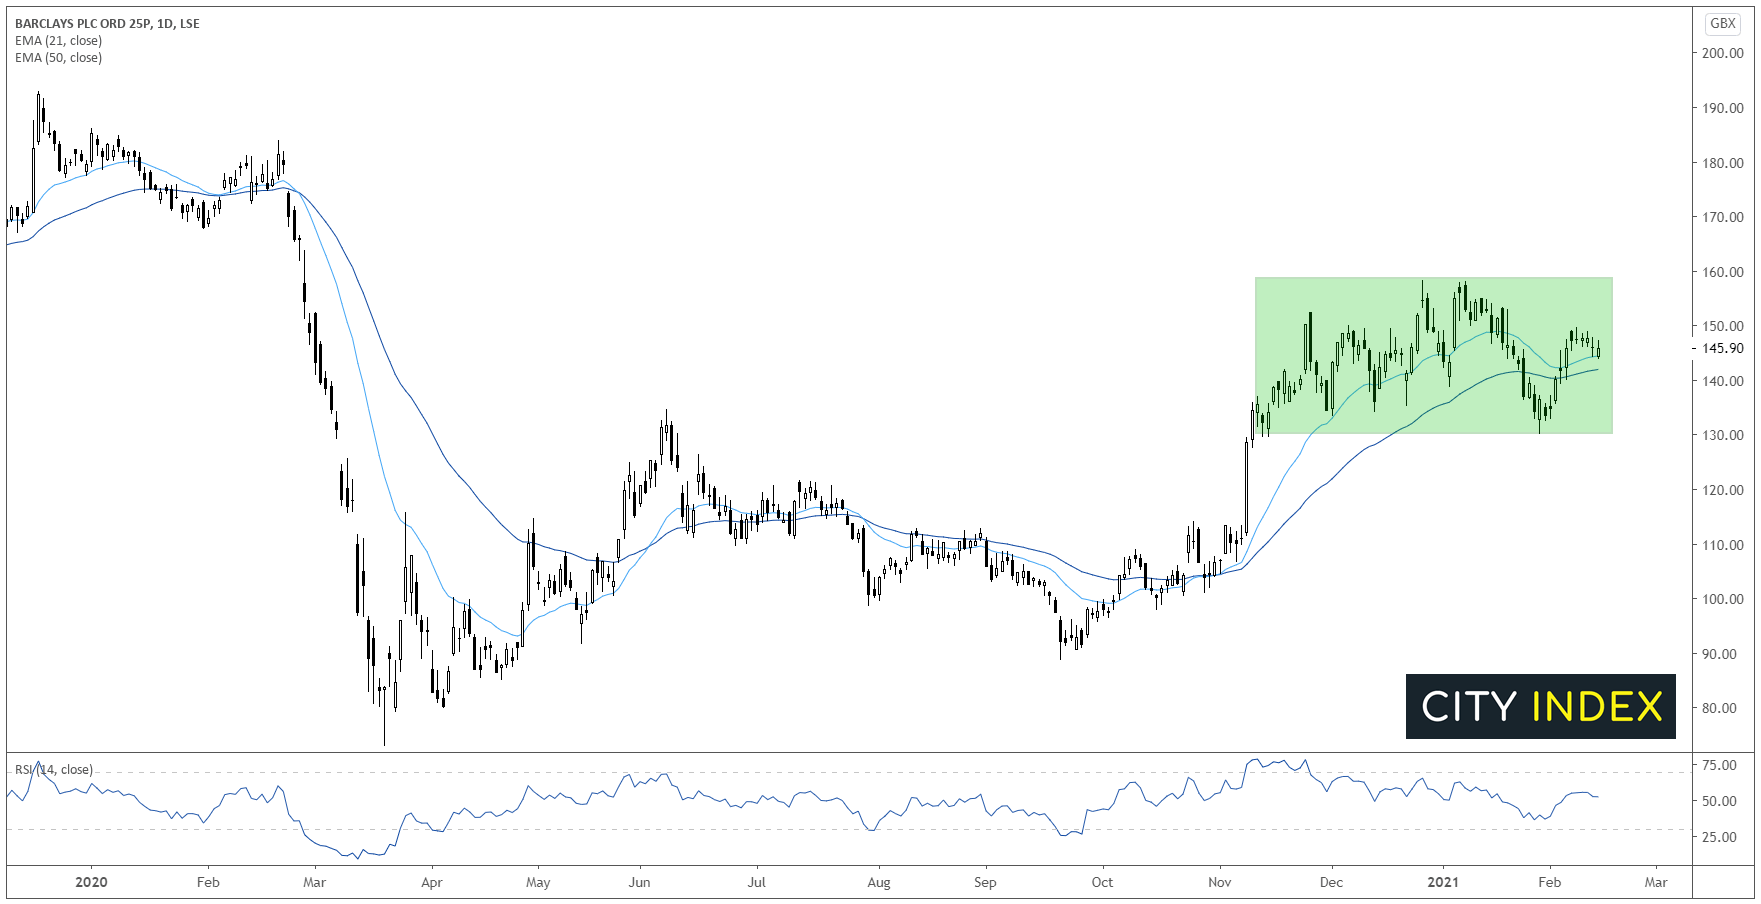
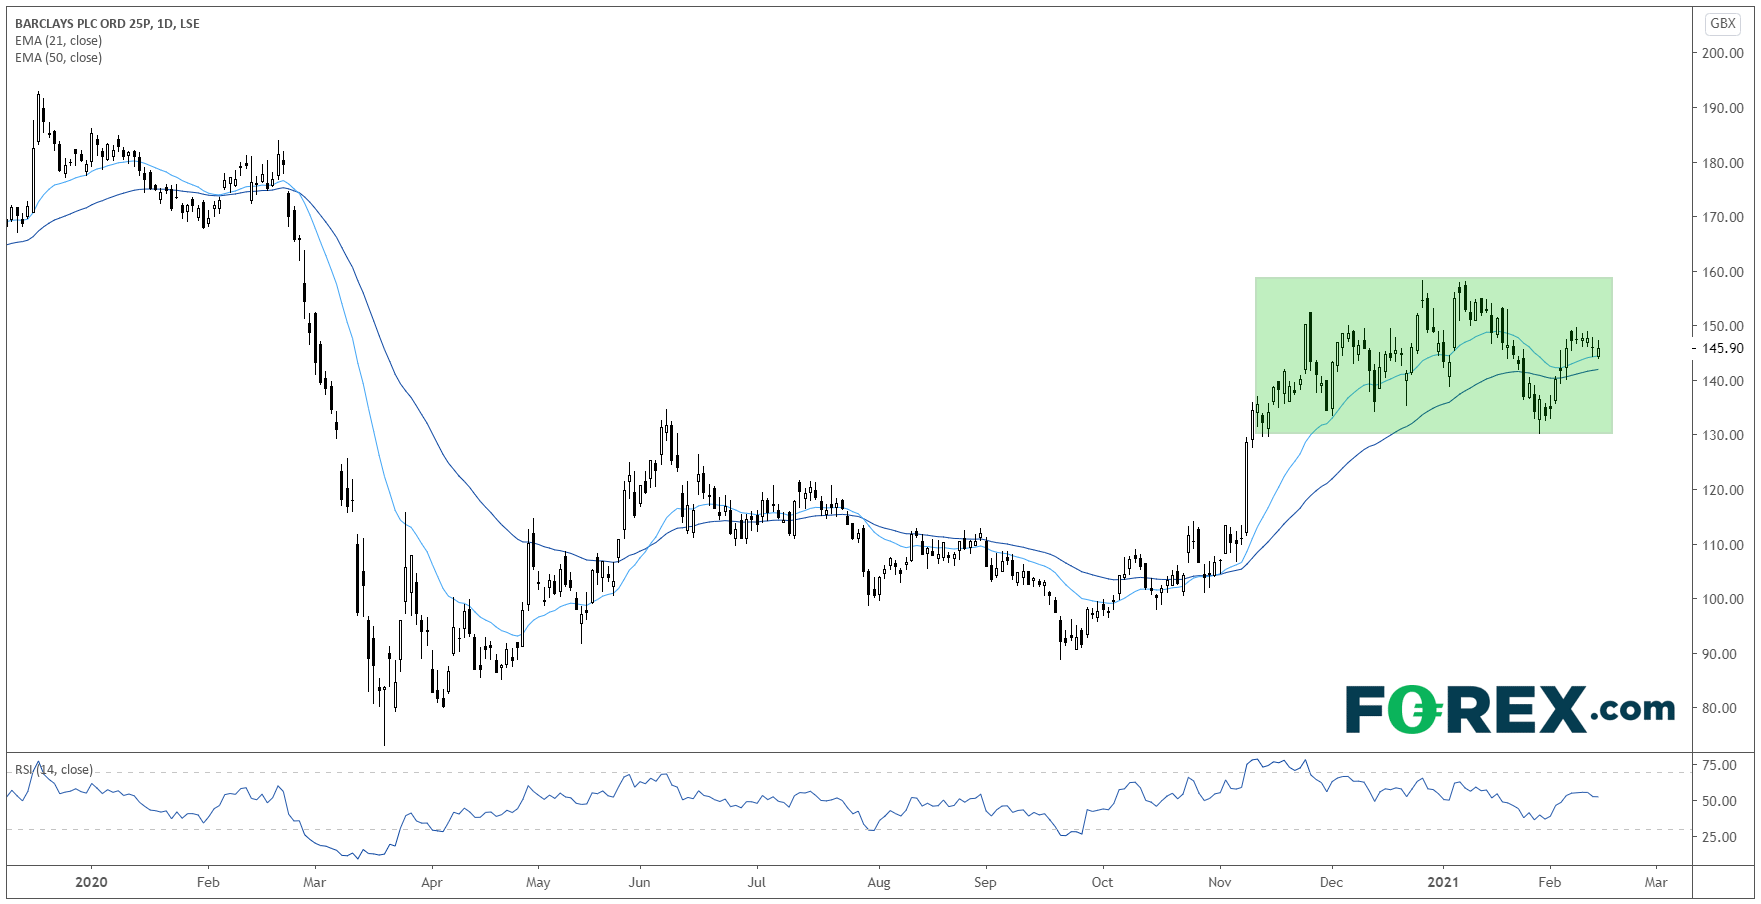
Looking at the chart, BARC has been consolidating in the middle of a sideways range since mid-November (note this will be a common trend for all the UK banks). With no clear momentum (RSI near 50) and prices near the middle of their established range, readers may prefer to wait for a post-earnings breakout below 130 or above 160 to signal the more likely next move in the stock:
Source: TradingView, GAIN Capital
NatWest Group (NWG) – Reports 19 Feb
EPS Expectation: -$0.03
From a technical perspective, the rebranded RBS saw the biggest decline of the four major UK banks on the back of the COVID pandemic, though its also seen the most impressive, rallying roughly 90% off its September lows. Looking ahead, the stock is testing the top of its consolidation range, presenting a clear risk management level for bulls to consider buying breakouts above or bears to “hide” stops above if earnings come out softer than expected:
Source: TradingView, GAIN Capital
HSBC Holdings (HSBC) – Reports 23 Feb
Expectation: $0.07
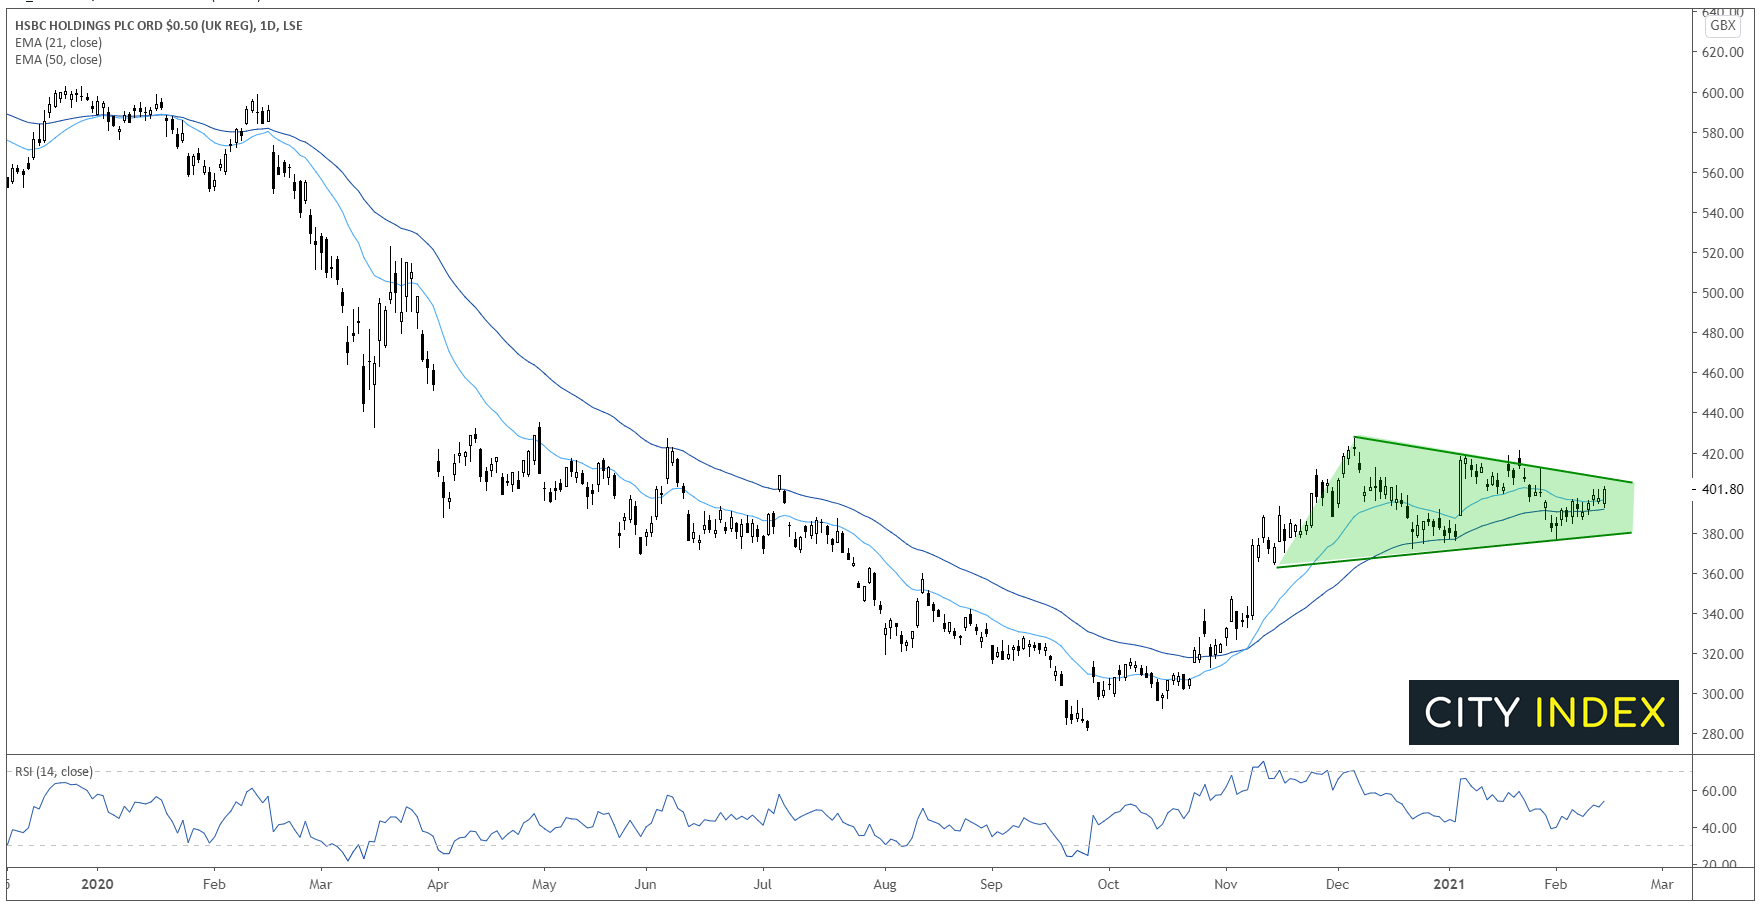
In direct contrast to NatWest, HSBC saw its stock hold up better than each of its major rivals in 2020, losing “just” roughly 50% off its highs to the September trough, though its recovery has also been the most tepid at just over 40%. In other words, HSBC has generally been less volatile and more steady over the last year+. Now, prices are consolidating in a symmetrical triangle pattern, signaling the potential for a bigger move if earnings lead to a breakout in either direction:
Source: TradingView, GAIN Capital
Lloyds Banking Group (LYG) – Reports 24 Feb
Expectation: $0.02
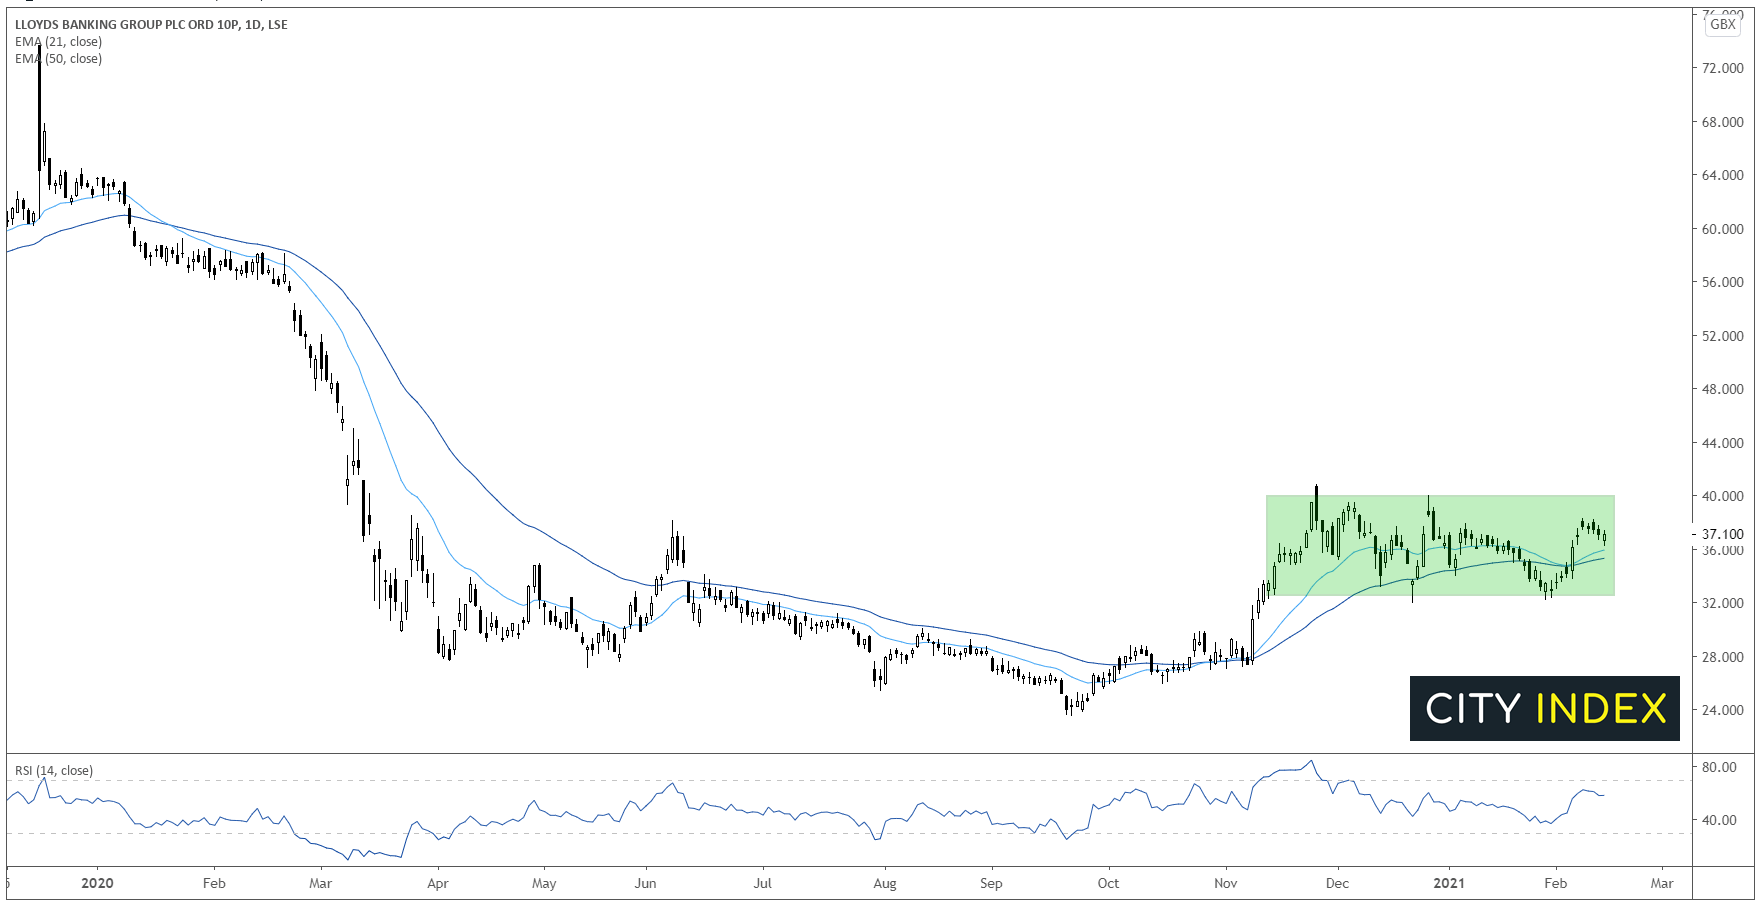
Last but not least, Lloyds has been hit hard by Brexit, the pandemic, and the so-far tepid recovery. The stock is currently trading at about half of its 2019 high, meaning that it may be the UK bank with the most potential to rally if the UK economy is able to get into gear later this year. The chart itself isn’t too compelling at the moment, with prices consolidating in the middle of the well-established 32-40 range. Bulls will be watching closely to see if this laggard can break above 40 as an early sign that it may play “catch up” in the coming weeks:
Source: TradingView, GAIN Capital
Learn more about equity trading opportunities.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD, Dow Jones Forecast: Key Technical Scenarios to Watch
GBP/USD and the Dow Jones are approaching critical technical levels amid earning optimism, Fed rate hike expectations, US-Iran developments, and persistent geopolitical risks.

The U.S. Dollar Is Rising Again and Nasdaq Is Feeling It
Nasdaq, the U.S. Dollar Index and Federal Reserve expectations are driving market sentiment ahead of a pivotal FOMC meeting. Razan Hilal, StoneX Market Analyst, explains how rising expectations for a hawkish Federal Reserve, persistent U.S.-Iran tensions and key technical levels on the U.S. Dollar Index could influence currencies, equities and precious metals in the weeks ahead.
US Dollar and Nasdaq Forecast: Fed, Microsoft, Meta, and Iran Talks in Focus
The US Dollar Index (DXY) continues to hold above the 101.00 mark, reinforcing its bullish structure, while the Nasdaq remains capped below the 29,000 resistance and its June-July consolidation range, reflecting cautious risk appetite ahead of the Federal Reserve's policy decision and major earnings releases on Wednesday.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.