




US open Futures mixed in cautious trade ISM services data in focus
US stocks are pointing to a cautious start to trade after the extended 4th July weekend. Rising oil prices threaten to undermine the global economic recovery. Nasdaq trades at record high. ISM services PMI in focus.
Share this:

US futures
Dow futures -0.27% at 34750
S&P futures -0.02% at 4348
Nasdaq futures +0.2% at 14740
In Europe
FTSE -0.18% at 7150
Dax -0.4% at 15606
Euro Stoxx -0.28% at 4078
Nasdaq hits fresh record high
US stocks are pointing to a mixed start after the holiday lengthened weekend. Cautious trade dominates after the OPEC+ group failed to agree to curb output cuts, sending oil prices to almost three year highs. Rising oil prices are positive for oil majors. However, the good news stops there. Rising oil prices add to lingering concerns over rising inflationary pressures and could undermine the global economic recovery.
Tech stocks are firmly in favour with the Nasdaq hitting fresh all-time highs. Meanwhile the Dow is edging lower as investors ditch value stocks reflecting concerns over the economic recovery.
Attention will now turn to the ISM services PMI, which is expected to show a slight dip lower in June to 63.5, down from 64. This would still be a very robust number. The employment subcomponent is expected to rise, whilst prices paid are due to ease slightly to 79.3 down from 80.6 in May.
Where next for the Nasdaq?
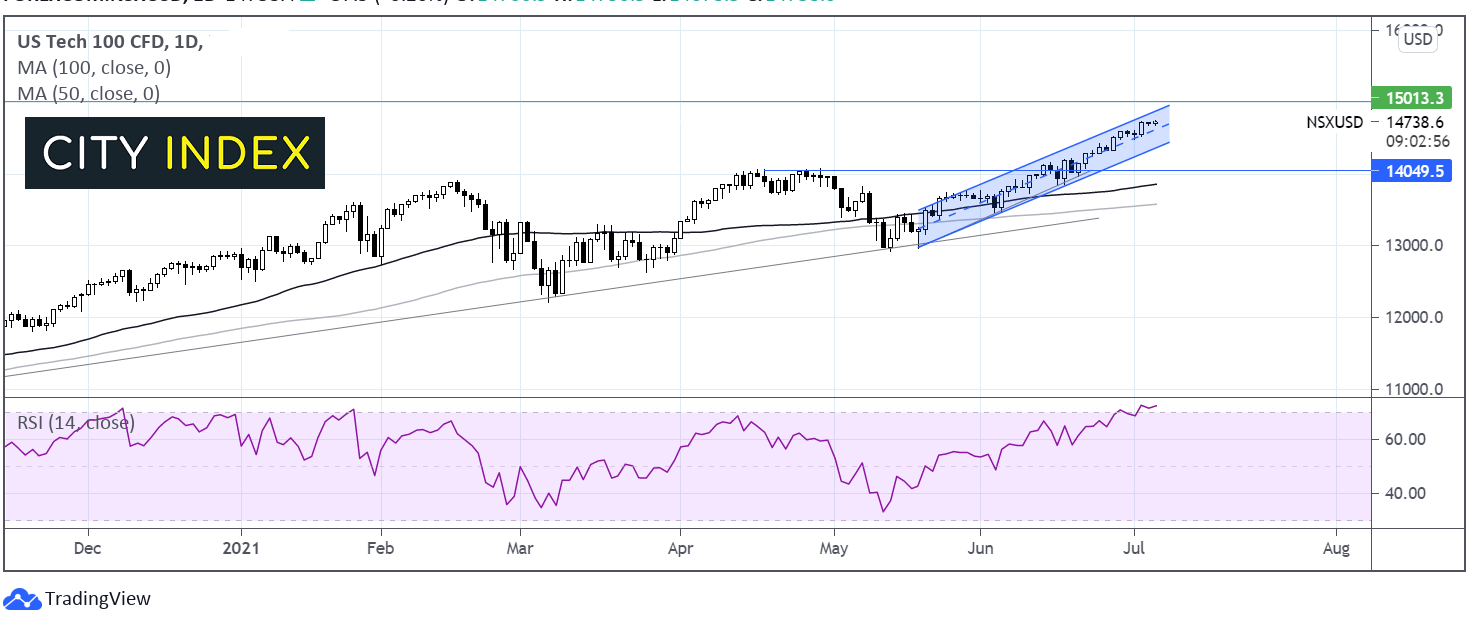
The Nasdaq continues to trade within its ascending channel dating back to mid-May. The index charged through previous resistance at 14050 the all time high reached in April with buyers looking to target 15000 the key psychological level. The RSI has moved into overbought territory suggesting the price could be vulnerable to a pull back. It would take a move below 14050 to negate the near-term uptrend.
FX – Euro trades lower on mixed data
The US Dollar is charging higher, paring some losses from Friday following the NFP numbers on safe haven flows. Attention will turn to the ISM services data, ahead of tomorrow’s release of the minutes from the latest FOMC meeting.
EUR/USD trades lower after a mixed bag of data. Whilst Eurozone retail sales numbers were better than expected, the good news stopped there. German factory order unexpectedly declined in May by -3.7%, down from -0.2% in April and well below the 5% rebound expected. German ZEW economic sentiment also fell by more than forecast to 63.3 in July, down from 79.8 in June and short of the 75.4 forecast. The data comes following impressive PMI numbers on Monday.
GBP/USD +0.07% at 1.3850
EUR/USD -0.31% at 1.1846
Oil surges as OPEC+ talks collapse
Oil prices trads around 3-year highs after the OPEC+ group failed to agree to increase oil production. After 3 days of intense talks, the group abandoned the meeting meaning that the expected increase in oil output won’t be happening as expected.
The oil market remains tight. Demand is rising as economies reopen but supply remains limited by OPEC+. Inventories are being drained and the situation is only expected to worsen as demand picks up further across the summer months. As a result, oil prices jumped higher. WTI crude hit a high of $77 whilst Brent hit $77.80.
US crude trades +1.4% at $76.22
Brent trades 0.0% at $77.17
Looking ahead
14:45 US Markit Services PMI (June)
15:00 ISM Services PMI
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
US futures
Dow futures -0.27% at 34750
S&P futures -0.02% at 4348
Nasdaq futures +0.2% at 14740
In Europe
FTSE -0.18% at 7150
Dax -0.4% at 15606
Euro Stoxx -0.28% at 4078
Learn more about trading indices
Nasdaq hits fresh record high
US stocks are pointing to a mixed start after the holiday lengthened weekend. Cautious trade dominates after the OPEC+ group failed to agree to curb output cuts, sending oil prices to almost three year highs. Rising oil prices are positive for oil majors. However, the good news stops there. Rising oil prices add to lingering concerns over rising inflationary pressures and could undermine the global economic recovery.
Tech stocks are firmly in favour with the Nasdaq hitting fresh all-time highs. Meanwhile the Dow is edging lower as investors ditch value stocks reflecting concerns over the economic recovery.
Attention will now turn to the ISM services PMI, which is expected to show a slight dip lower in June to 63.5, down from 64. This would still be a very robust number. The employment subcomponent is expected to rise, whilst prices paid are due to ease slightly to 79.3 down from 80.6 in May.
Where next for the Nasdaq?
The Nasdaq continues to trade within its ascending channel dating back to mid-May. The index charged through previous resistance at 14050 the all time high reached in April with buyers looking to target 15000 the key psychological level. The RSI has moved into overbought territory suggesting the price could be vulnerable to a pull back. It would take a move below 14050 to negate the near-term uptrend.
FX – Euro trades lower on mixed data
The US Dollar is charging higher, paring some losses from Friday following the NFP numbers on safe haven flows. Attention will turn to the ISM services data, ahead of tomorrow’s release of the minutes from the latest FOMC meeting.
EUR/USD trades lower after a mixed bag of data. Whilst Eurozone retail sales numbers were better than expected, the good news stopped there. German factory order unexpectedly declined in May by -3.7%, down from -0.2% in April and well below the 5% rebound expected. German ZEW economic sentiment also fell by more than forecast to 63.3 in July, down from 79.8 in June and short of the 75.4 forecast. The data comes following impressive PMI numbers on Monday.
GBP/USD +0.07% at 1.3850
EUR/USD -0.31% at 1.1846
Oil surges as OPEC+ talks collapse
Oil prices trads around 3-year highs after the OPEC+ group failed to agree to increase oil production. After 3 days of intense talks, the group abandoned the meeting meaning that the expected increase in oil output won’t be happening as expected.
The oil market remains tight. Demand is rising as economies reopen but supply remains limited by OPEC+. Inventories are being drained and the situation is only expected to worsen as demand picks up further across the summer months. As a result, oil prices jumped higher. WTI crude hit a high of $77 whilst Brent hit $77.80.
US crude trades +1.4% at $76.22
Brent trades 0.0% at $77.17
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
14:45 US Markit Services PMI (June)
15:00 ISM Services PMI
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.