



US open: Stocks rise cautiously ahead of the Fed
Futures are edging higher, shrugging off Putin's call for mobilisation and looking ahead to the Fed's rate announcement.
Share this:

US futures
Dow futures +0.36% at 30819
S&P futures +0.37% at 3863
Nasdaq futures +0.11% at 11868
In Europe
FTSE +0.75% at 7234
Dax -0.06% at 12665
Euro Stoxx -0.8% at 3462
Central banks are the only game in town
US stocks are heading carefully higher after booking losses in the previous session and as investors prepare themselves for another large rate hike.
The US central bank will conclude its 2-day monetary policy meeting later today and is expected to raise rates by 75 basis points, its third straight 75 bps points hike. Some are preparing for a 100 basis point hike, but this is not the base case scenario.
The Fed’s growth and inflation projections will also be in focus and could help the market assess how hawkish the Fed is likely to be going forward. With this in mind, it is unlikely to be the rate hike itself that is market moving. Instead, it will be the outlook for further hikes and how hawkish the Fed is expected to be at the future meetings. A more aggressive Fed means the central bank will have more problems engineering a soft landing.
The broader market recovered from weakness early in the European session following a speech by Russian President Putin, who said he was mobilizing troops to defend the annexed part of Ukraine.
Corporate news:
General Mills rises 2% pre-market after raising complete year sales and profits forecasts, amid expectations of resilient demand for cereals, snack bars, and pet food even as prices rise.
Beyond Meat falls 1.4% pre-market after the immediate suspension of its COO following reports of his arrest following an altercation where he bit a man’s nose.
Where next for the S&p500?
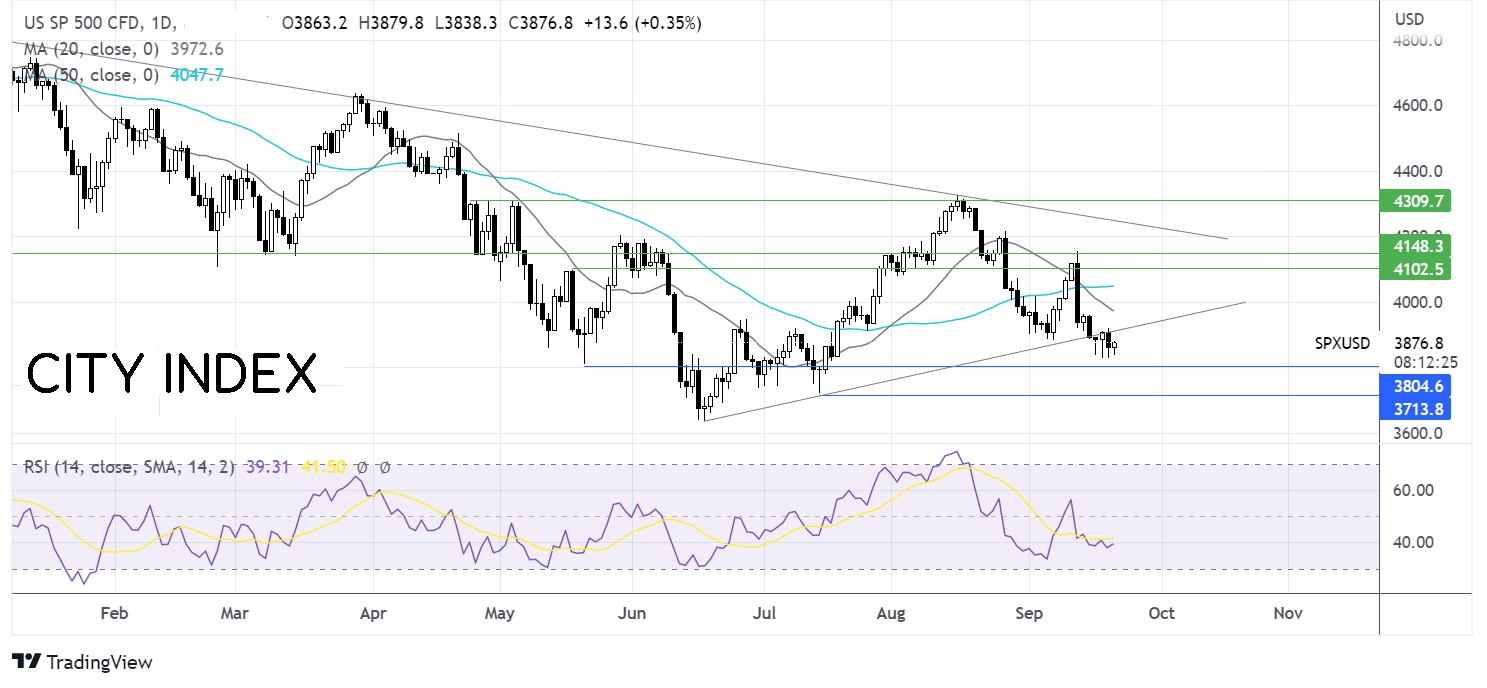
The S&P500 fell below the multi-month rising trend line support and has been unable to rise back above the trendline resistance. The RSI supports further downside. Sellers will need to break below 3827, the weekly low, to extend the bearish trend towards 3810, the May low, and 3720, the July 14 low. Buyers could be encouraged by the long lower wicks suggesting that demand is weak at these lower levels. Buyers will look for a rise over 3940, the weekly high to expose the 20 sma at 3966 and the 50 sma at 4047.

FX markets – USD rises, EUR falls.
The USD rises firmly for a second straight day and trades around a 20-year high. The USD is benefiting from a combination of hawkish Fed bets and safe haven flows in a win-win trade. Part of the allure of the USD is also because there is no real other alternative.
EUR/USD is falling, underperforming its major peers as investors sell out of the euro after Putin’s announcement. The news, combined with hawkish Federal Reserve bets, leaves few reasons for investors to want to buy into euros.
GBP/USD is also trading under pressure after data showed that the UK government borrowed almost double to forecast amount in August. The UK public sector’s net borrowing jumped to £11.8 billion. Borrowing is likely to increase further to fund PM Liz Truss’s energy support package and additional tax cuts, which will be announced on Friday.
GBP/USD -0.32% at 1.1340
EUR/USD -0.63% at 0.99
Oil jumps as Russia fears rise.
Oil prices have jumped higher on news that Putin is mobilizing more troops. The escalation of the war in Ukraine raises fears of a tighter oil and gas supply.
This move by Putin raises the risk of a more prolonged war in Russia. Any hopes of a sooner end to the conflict have been put firmly to bed. This means that supply worries will be here for the longer term.
Separately, there appears to be little hope of a breakthrough to revive the Iran nuclear deal at this week’s UN General Assembly. This effectively reduces the prospect of Iranian barrels returning to the market soon.
WTI crude trades +2.6% at $86.01
Brent trades +2.5% at $91.81
Looking ahead
15:30 EIA crude oil stockpiles
19:00 Fed rate decision
19:30 Fed Press Conference
US futures
Dow futures +0.36% at 30819
S&P futures +0.37% at 3863
Nasdaq futures +0.11% at 11868
In Europe
FTSE +0.75% at 7234
Dax -0.06% at 12665
Euro Stoxx -0.8% at 3462
Learn more about trading indices
Central banks are the only game in town
US stocks are heading carefully higher after booking losses in the previous session and as investors prepare themselves for another large rate hike.
The US central bank will conclude its 2-day monetary policy meeting later today and is expected to raise rates by 75 basis points, its third straight 75 bps points hike. Some are preparing for a 100 basis point hike, but this is not the base case scenario.
The Fed’s growth and inflation projections will also be in focus and could help the market assess how hawkish the Fed is likely to be going forward. With this in mind, it is unlikely to be the rate hike itself that is market moving. Instead, it will be the outlook for further hikes and how hawkish the Fed is expected to be at the future meetings. A more aggressive Fed means the central bank will have more problems engineering a soft landing.
The broader market recovered from weakness early in the European session following a speech by Russian President Putin, who said he was mobilizing troops to defend the annexed part of Ukraine.
Corporate news:
General Mills rises 2% pre-market after raising complete year sales and profits forecasts, amid expectations of resilient demand for cereals, snack bars, and pet food even as prices rise.
Beyond Meat falls 1.4% pre-market after the immediate suspension of its COO following reports of his arrest following an altercation where he bit a man’s nose.
Where next for the S&p500?
The S&P500 fell below the multi-month rising trend line support and has been unable to rise back above the trendline resistance. The RSI supports further downside. Sellers will need to break below 3827, the weekly low, to extend the bearish trend towards 3810, the May low, and 3720, the July 14 low. Buyers could be encouraged by the long lower wicks suggesting that demand is weak at these lower levels. Buyers will look for a rise over 3940, the weekly high to expose the 20 sma at 3966 and the 50 sma at 4047.
FX markets – USD rises,EUR falls
The USD rises firmly for a second straight day and trades around a 20-year high. The USD is benefiting from a combination of hawkish Fed bets and safe haven flows in a win-win trade. Part of the allure of the USD is also because there is no real other alternative.
EUR/USD is falling, underperforming its major peers as investors sell out of the euro after Putin’s announcement. The news, combined with hawkish Federal Reserve bets, leaves few reasons for investors to want to buy into euros.
GBP/USD is also trading under pressure after data showed that the UK government borrowed almost double to forecast amount in August. The UK public sector’s net borrowing jumped to £11.8 billion. Borrowing is likely to increase further to fund PM Liz Truss’s energy support package and additional tax cuts, which will be announced on Friday.
GBP/USD -0.32% at 1.1340
EUR/USD -0.63% at 0.99
Oil jumps as Russia fears rise.
Oil prices have jumped higher on news that Putin is mobilizing more troops. The escalation of the war in Ukraine raises fears of a tighter oil and gas supply.
This move by Putin raises the risk of a more prolonged war in Russia. Any hopes of a sooner end to the conflict have been put firmly to bed. This means that supply worries will be here for the longer term.
Separately, there appears to be little hope of a breakthrough to revive the Iran nuclear deal at this week’s UN General Assembly. This effectively reduces the prospect of Iranian barrels returning to the market soon.
WTI crude trades +2.6% at $86.01
Brent trades +2.5% at $91.81
Learn more about trading oil here.
Looking ahead
15:30 EIA crude oil stockpiles
19:00 Fed rate decision
19:30 Fed Press Conference
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.

Gold forecast: Rising yields become too hot for gold, but the outlook is far from bearish
Gold and silver prices took a plunge today, with the former down 3% and the latter falling some 5% by mid European session, before bouncing off their lows. The losses come after the metals remained largely supported until last week, despite the big dollar rally and surging bond yields as we have seen in recent weeks. But it simply got too much, and the metals succumbed to pressure today.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.