




Week Ahead Will there be more Middle East drama
Going into the weekend, some market participants will be wondering whether more Middle East drama will unfold over the next couple of days, and if so, what might that mean for their open positions.
Share this:

After a turbulent start to 2020 with a sharp escalation in US-Iran tensions, things calmed down from the middle of the week. Oil prices, which had spiked sharply higher, fell even more sharply as investors remembered increasing non-OPEC oil output - and not to forget the willingness from other OPEC members to step up - would more than offset any potential supply disruptions in Iran or Iraq. Gold, silver and yen also gave back some of their gains as demand for safe haven assets fell, which helped to fuel the ongoing rally on Wall Street where the major indices hit fresh record highs.
Going into the weekend, some market participants will be wondering whether more Middle East drama will unfold over the next couple of days, and if so, what might that mean for their open positions. Thus, it is reasonable to expect some profit-taking of risky positions such as stocks later on today - and possibly the opening of few opportunistic long positions in crude oil and gold, in case you-know-what hits the fan again.
If tensions escalate again over the weekend, then expect the markets to again open with big gaps - especially for crude oil and gold. Otherwise, the start of next week could be a continuation of this: risk ON. If that’s the case then expect things like copper and the FTSE 100 to rally, for the reasons we have discussed HERE and HERE.
Meanwhile, next week’s data highlights include U.S. CPI and a handful of U.K. macro numbers. Overall, there won’t be too many market-moving macro numbers to look forward to. So, the focus will continue to remain on Middle East tensions, ongoing US-China trade situation and Brexit. Still, some of next week’s data releases should move currencies. So, here are the data highlights for next week:
Monday
- A handful of UK economic data including monthly GDP – expected flat; manufacturing production, expected to print -0.3% m/m; construction output, +0.6% expected following a 2.3% drop the month before, and the NIESR’s GDP estimate, among a few other things.
Tuesday
- China’s latest trade figures
- US CPI – with headline expected at 0.2% vs. +0.3% last time, while core is seen at +0.2%, similar to the previous month.
Wednesday
- UK CPI – both headline and core expected unchanged at 1.5% and 1.7% y/y respectively
- Eurozone industrial production seen at +0.3% expected vs. -0.2% last
- Crude oil inventories
Thursday
- ECB’s Monetary Policy Meeting Account
- US retail sales – headline expected at +0.3% vs. +0.2% last and core seen at +0.5% vs. +0.1% last. In addition to retail sales, there will be a number of other second-tier US macro pointers that will be published on Thursday.
Friday
- China’s GDP – expected unchanged at 6.0% q/y; Industrial output is also expected to have remained flat at 6.2%, while retail sales are seen easing to 7.9% y/y growth from 8.0% in the month before.
- UK retail sales – expected to print +0.8% m/m vs. -0.6% the month before.
- More second-tier US data, including Building Permits, Housing Permits, Industrial Production and Prelim UoM Consumer Sentiment.
Chart to watch: gold
Source: Trading View and City Index.
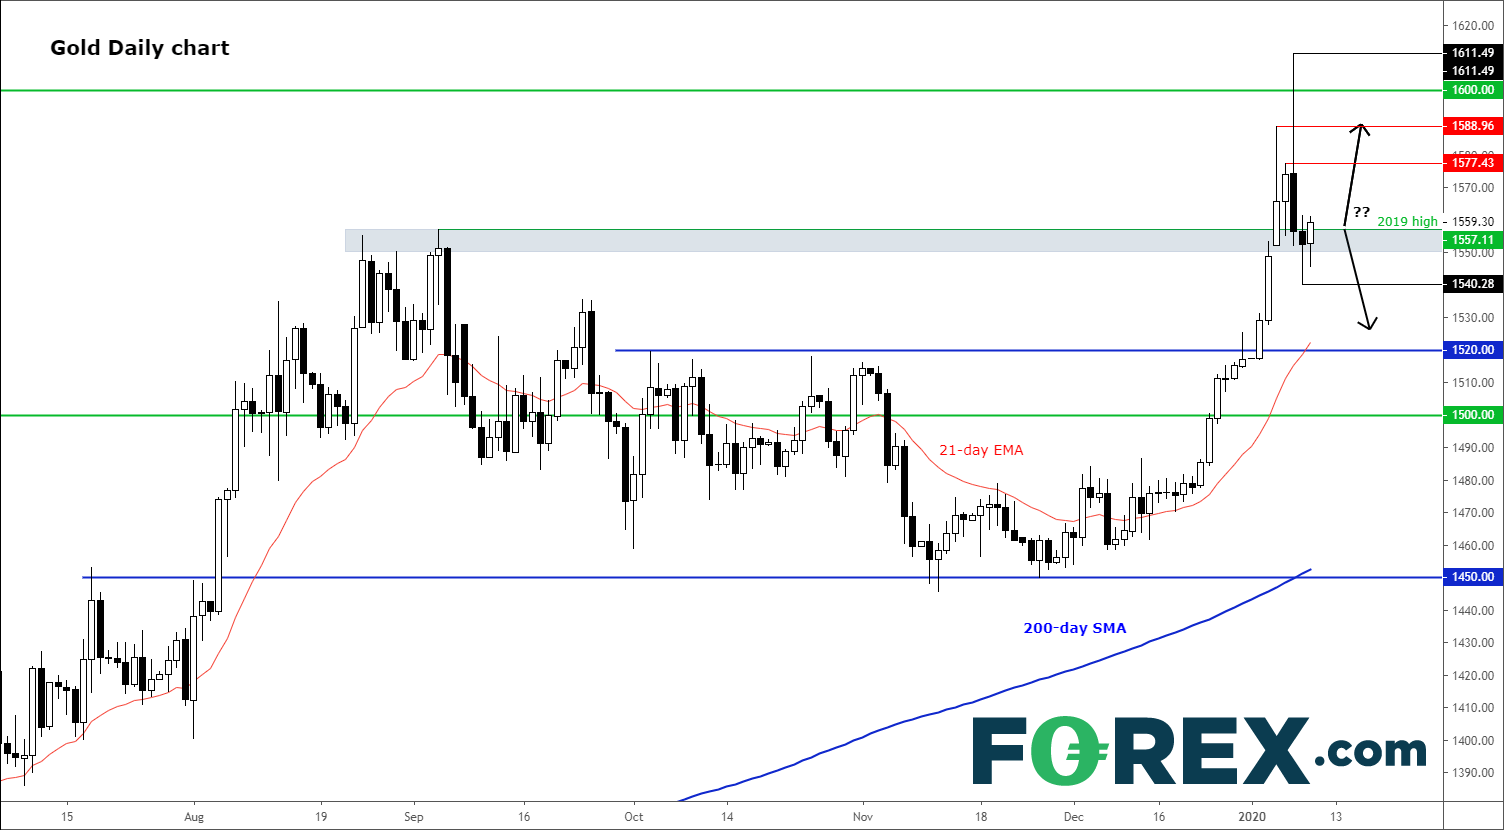
Our featured chart to watch for the week ahead is that of gold. The yellow metal broke last year’s high and key resistance at $1555/57, and investors will be looking to see what happens next. If the precious metal holds above this area then more gains should be expected, especially in light of Friday’s disappointing US jobs report and ongoing central bank support with interest rates and yields being depressed. However, a clean break back below this level would be bearish in the near-term outlook.
After a turbulent start to 2020 with a sharp escalation in US-Iran tensions, things calmed down from the middle of the week. Oil prices, which had spiked sharply higher, fell even more sharply as investors remembered increasing non-OPEC oil output - and not to forget the willingness from other OPEC members to step up - would more than offset any potential supply disruptions in Iran or Iraq. Gold, silver and yen also gave back some of their gains as demand for safe haven assets fell, which helped to fuel the ongoing rally on Wall Street where the major indices hit fresh record highs.
Going into the weekend, some market participants will be wondering whether more Middle East drama will unfold over the next couple of days, and if so, what might that mean for their open positions. Thus, it is reasonable to expect some profit-taking of risky positions such as stocks later on today - and possibly the opening of few opportunistic long positions in crude oil and gold, in case you-know-what hits the fan again.
If tensions escalate again over the weekend, then expect the markets to again open with big gaps - especially for crude oil and gold. Otherwise, the start of next week could be a continuation of this: risk ON. If that’s the case then expect things like copper and the FTSE 100 to rally, for the reasons we have discussed HERE.
Meanwhile, next week’s data highlights include U.S. CPI and a handful of U.K. macro numbers. Overall, there won’t be too many market-moving macro numbers to look forward to. So, the focus will continue to remain on Middle East tensions, ongoing US-China trade situation and Brexit. Still, some of next week’s data releases should move currencies. So, here are the data highlights for next week:
Monday
- A handful of UK economic data including monthly GDP – expected flat; manufacturing production, expected to print -0.3% m/m; construction output, +0.6% expected following a 2.3% drop the month before, and the NIESR’s GDP estimate, among a few other things.
Tuesday
- China’s latest trade figures
- US CPI – headline expected at 0.2% vs. +0.3% last time, while core is seen at +0.2%, similar to the previous month.
Wednesday
- UK CPI – both headline and core expected unchanged at 1.5% and 1.7% y/y respectively
- Eurozone industrial production seen at +0.3% expected vs. -0.2% last
- Crude oil inventories
Thursday
- ECB’s Monetary Policy Meeting Account
- US retail sales – headline expected at +0.3% vs. +0.2% last and core seen at +0.5% vs. +0.1% last. In addition to retail sales, there will be a number of other second-tier US macro pointers that will be published on Thursday.
Friday
- China’s GDP – expected unchanged at 6.0% q/y; Industrial output is also expected to have remained flat at 6.2%, while retail sales are seen easing to 7.9% y/y growth from 8.0% in the month before.
- UK retail sales – expected to print +0.8% m/m vs. -0.6% the month before.
- More second-tier US data, including Building Permits, Housing Permits, Industrial Production and Prelim UoM Consumer Sentiment.
Chart to watch: gold
Source: Trading View and FOREX.com.
Our featured chart to watch for the week ahead is that of gold. The yellow metal broke last year’s high and key resistance at $1555/57, and investors will be looking to see what happens next. If the precious metal holds above this area then more gains should be expected, especially in light of Friday’s disappointing US jobs report and ongoing central bank support with interest rates and yields being depressed. However, a clean break back below this level would be bearish in the near-term outlook.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Analysis: What's Next for the Australian Dollar After the RBA Decision?
Recent trading sessions have reflected a more neutral tone around the Australian dollar. This can be seen in AUD/USD price action, which has posted moves of roughly 0.2% over the last two sessions without establishing a clear direction. Much of this lack of momentum is linked to expectations surrounding the next policy moves from both the Reserve Bank of Australia (RBA) and the Federal Reserve.
Gold forecast: Rising yields become too hot for gold, but the outlook is far from bearish
Gold and silver prices took a plunge today, with the former down 3% and the latter falling some 5% by mid European session, before bouncing off their lows. The losses come after the metals remained largely supported until last week, despite the big dollar rally and surging bond yields as we have seen in recent weeks. But it simply got too much, and the metals succumbed to pressure today.

USD into a Massive Week as Yields Fly and Gold Breaks
It’s a huge week with PCE and NFP, but it’s what’s happening off of the calendar that demands attention with US yields flying to fresh multi-decade highs.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.