



asia morning nov 2
Twitter (-21.11%) becomes the top loser...
Share this:

On Friday, U.S. stocks ended in the red again. The Dow Jones Industrial Average fell 157 points (-0.59%) to 26501, the S&P 500 dropped 40 points (-1.21%) to 3270, and the Nasdaq 100 slumped 297 points (-2.62%) to 11052.
S&P 500 Index (Daily Chart) : Downside Prevails
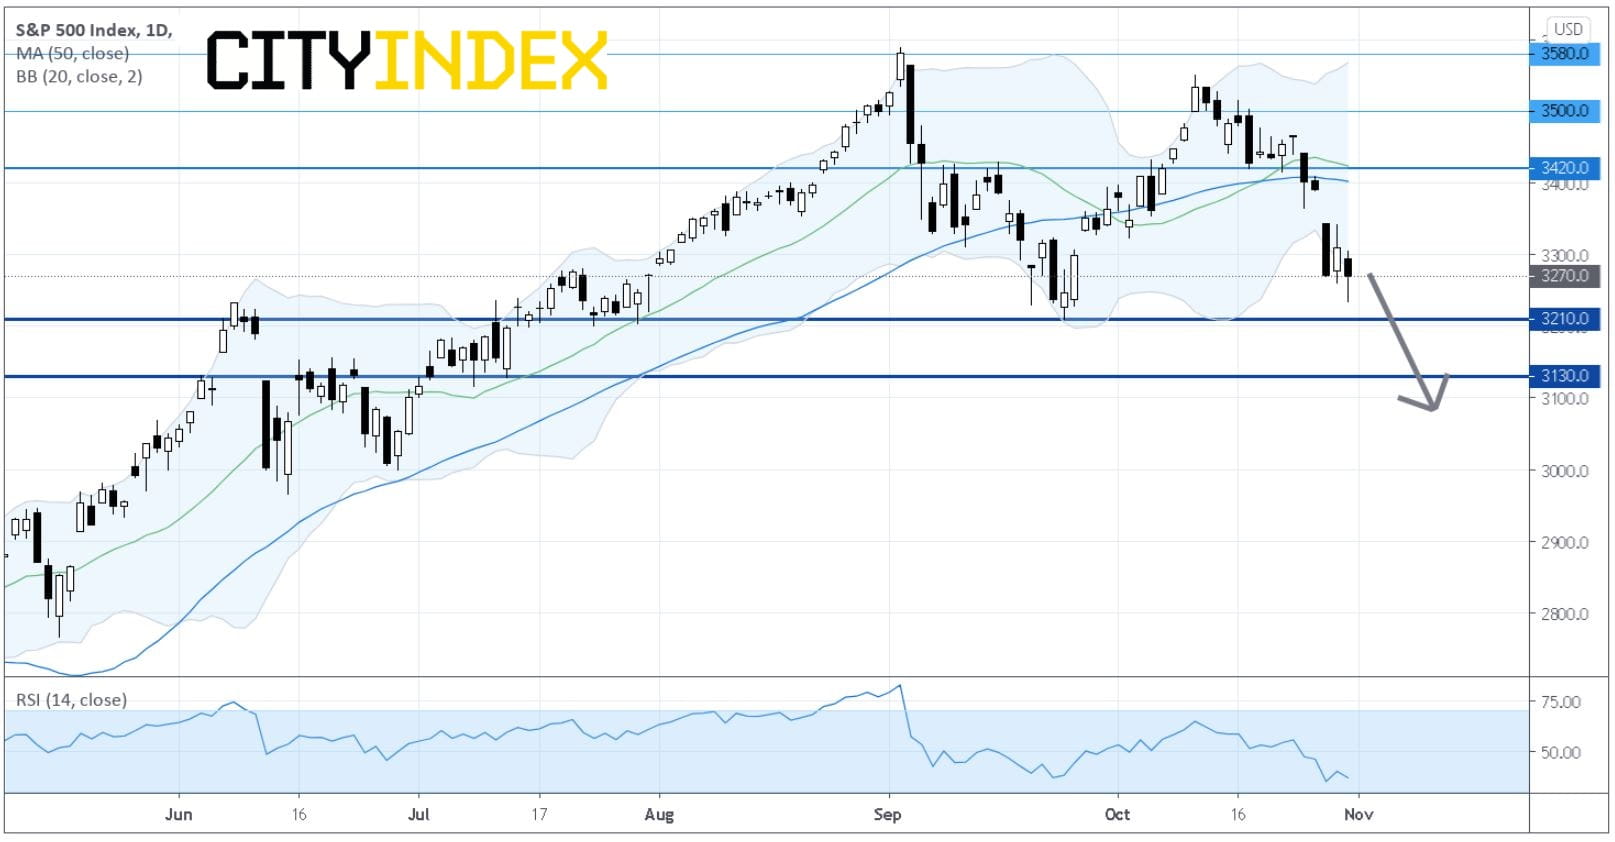
Sources: GAIN Capital, TradingView
Investors became cautious ahead of the November 3 presidential election, and remained concerned over the record-breaking COVID-19 cases around the world.
At the weekend, U.K. Prime Minister Boris Johnson announced a second lockdown for England in order to curb rising coronavirus cases. Pubs, restaurants, gyms and non-essential shops will have to close for four weeks, while schools, colleges and universities can stay open.
Technology Hardware & Equipment (-4.52%), Retailing (-3.7%) and Semiconductors & Semiconductor Equipment (-1.94%) sectors lost the most. Facebook (FB -6.31%), Amazon.com (AMZN -5.45%) and Apple (AAPL -5.60%) were down heavily despite posting better-than-expected results. Alphabet (GOOGL +3.80%) ended higher.
Twitter (TWTR -21.11%) was the top loser after third-quarter daily active-user amount missed market expectations.
Approximately 60% (58% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 16% (12% in the prior session) were trading above their 20-day moving average.
Regarding U.S. economic data, Personal Income rose 0.9% on month in September (+0.4% expected) and Personal Spending increased 1.4% (+1.0% expected). The University of Michigan's Consumer Sentiment Index advanced to 81.8 in October (81.2 expected), and the Market News International Chicago Business Barometer slipped to 61.1 in October (58.0 expected).
European stocks ended mixed. The Stoxx Europe 600 added 0.18%, France's CAC 40 climbed 0.54%, while Germany's DAX 30 slipped 0.36% and the U.K.'s FTSE 100 dipped 0.08%.
U.S. Treasury prices remained under pressure, as the benchmark 10-year Treasury yield charged higher to 0.855% from 0.835% Thursday.
Spot gold gained $11 (+0.60%) to $1,878 an ounce.
U.S. WTI crude futures (December) sank a further $0.57 (-1.58%) to $35.6 a barrel.
On the forex front, the U.S. dollar was still firm against other major currencies. The ICE Dollar Index has regained the 94.00 level.
EUR/USD declined 0.24% to 1.1646 extending its losing streak to a fifth session. Official data showed that the eurozone's GDP grew 12.7% on quarter in the third quarter (+9.6% expected), consumer prices added 0.2% on month in October (+0.1% expected) and jobless rate rose to 8.3% in September (8.2% expected).
Germany's GDP increased 8.2% on quarter in the third quarter (+7.3% expected), while retail sales declined 2.2% on month in September (-0.6% expected).
France's GDP jumped 18.2% on quarter in the third quarter (+15.0% expected), and consumer prices edged down 0.1% on month in October (+0.0% expected).
GBP/USD added 0.14% to 1.2949. In the U.K., the Nationwide Building Society House Price Index rose 0.8% on month in October (+0.4% expected). Meanwhile, investors should beware the impact on the pound of the U.K. government's latest announcement of a new round of pandemic-induced lockdown measures.
USD/JPY edged higher to 104.66, while both AUD/USD and USD/CAD closed flat at 0.7028 and 1.3322 respectively.
S&P 500 Index (Daily Chart) : Downside Prevails
Sources: GAIN Capital, TradingView
Investors became cautious ahead of the November 3 presidential election, and remained concerned over the record-breaking COVID-19 cases around the world.
At the weekend, U.K. Prime Minister Boris Johnson announced a second lockdown for England in order to curb rising coronavirus cases. Pubs, restaurants, gyms and non-essential shops will have to close for four weeks, while schools, colleges and universities can stay open.
Technology Hardware & Equipment (-4.52%), Retailing (-3.7%) and Semiconductors & Semiconductor Equipment (-1.94%) sectors lost the most. Facebook (FB -6.31%), Amazon.com (AMZN -5.45%) and Apple (AAPL -5.60%) were down heavily despite posting better-than-expected results. Alphabet (GOOGL +3.80%) ended higher.
Twitter (TWTR -21.11%) was the top loser after third-quarter daily active-user amount missed market expectations.
Approximately 60% (58% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 16% (12% in the prior session) were trading above their 20-day moving average.
Regarding U.S. economic data, Personal Income rose 0.9% on month in September (+0.4% expected) and Personal Spending increased 1.4% (+1.0% expected). The University of Michigan's Consumer Sentiment Index advanced to 81.8 in October (81.2 expected), and the Market News International Chicago Business Barometer slipped to 61.1 in October (58.0 expected).
European stocks ended mixed. The Stoxx Europe 600 added 0.18%, France's CAC 40 climbed 0.54%, while Germany's DAX 30 slipped 0.36% and the U.K.'s FTSE 100 dipped 0.08%.
U.S. Treasury prices remained under pressure, as the benchmark 10-year Treasury yield charged higher to 0.855% from 0.835% Thursday.
Spot gold gained $11 (+0.60%) to $1,878 an ounce.
U.S. WTI crude futures (December) sank a further $0.57 (-1.58%) to $35.6 a barrel.
On the forex front, the U.S. dollar was still firm against other major currencies. The ICE Dollar Index has regained the 94.00 level.
EUR/USD declined 0.24% to 1.1646 extending its losing streak to a fifth session. Official data showed that the eurozone's GDP grew 12.7% on quarter in the third quarter (+9.6% expected), consumer prices added 0.2% on month in October (+0.1% expected) and jobless rate rose to 8.3% in September (8.2% expected).
Germany's GDP increased 8.2% on quarter in the third quarter (+7.3% expected), while retail sales declined 2.2% on month in September (-0.6% expected).
France's GDP jumped 18.2% on quarter in the third quarter (+15.0% expected), and consumer prices edged down 0.1% on month in October (+0.0% expected).
GBP/USD added 0.14% to 1.2949. In the U.K., the Nationwide Building Society House Price Index rose 0.8% on month in October (+0.4% expected). Meanwhile, investors should beware the impact on the pound of the U.K. government's latest announcement of a new round of pandemic-induced lockdown measures.
USD/JPY edged higher to 104.66, while both AUD/USD and USD/CAD closed flat at 0.7028 and 1.3322 respectively.
On Friday, U.S. stocks ended in the red again. The Dow Jones Industrial Average fell 157 points (-0.59%) to 26501, the S&P 500 dropped 40 points (-1.21%) to 3270, and the Nasdaq 100 slumped 297 points (-2.62%) to 11052.
S&P 500 Index (Daily Chart) : Downside Prevails

Sources: GAIN Capital, TradingView
Investors became cautious ahead of the November 3 presidential election, and remained concerned over the record-breaking COVID-19 cases around the world.
At the weekend, U.K. Prime Minister Boris Johnson announced a second lockdown for England in order to curb rising coronavirus cases. Pubs, restaurants, gyms and non-essential shops will have to close for four weeks, while schools, colleges and universities can stay open.
Technology Hardware & Equipment (-4.52%), Retailing (-3.7%) and Semiconductors & Semiconductor Equipment (-1.94%) sectors lost the most. Facebook (FB -6.31%), Amazon.com (AMZN -5.45%) and Apple (AAPL -5.60%) were down heavily despite posting better-than-expected results. Alphabet (GOOGL +3.80%) ended higher.
Twitter (TWTR -21.11%) was the top loser after third-quarter daily active-user amount missed market expectations.
Approximately 60% (58% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 16% (12% in the prior session) were trading above their 20-day moving average.
Regarding U.S. economic data, Personal Income rose 0.9% on month in September (+0.4% expected) and Personal Spending increased 1.4% (+1.0% expected). The University of Michigan's Consumer Sentiment Index advanced to 81.8 in October (81.2 expected), and the Market News International Chicago Business Barometer slipped to 61.1 in October (58.0 expected).
European stocks ended mixed. The Stoxx Europe 600 added 0.18%, France's CAC 40 climbed 0.54%, while Germany's DAX 30 slipped 0.36% and the U.K.'s FTSE 100 dipped 0.08%.
U.S. Treasury prices remained under pressure, as the benchmark 10-year Treasury yield charged higher to 0.855% from 0.835% Thursday.
Spot gold gained $11 (+0.60%) to $1,878 an ounce.
U.S. WTI crude futures (December) sank a further $0.57 (-1.58%) to $35.6 a barrel.
On the forex front, the U.S. dollar was still firm against other major currencies. The ICE Dollar Index has regained the 94.00 level.
EUR/USD declined 0.24% to 1.1646 extending its losing streak to a fifth session. Official data showed that the eurozone's GDP grew 12.7% on quarter in the third quarter (+9.6% expected), consumer prices added 0.2% on month in October (+0.1% expected) and jobless rate rose to 8.3% in September (8.2% expected).
Germany's GDP increased 8.2% on quarter in the third quarter (+7.3% expected), while retail sales declined 2.2% on month in September (-0.6% expected).
France's GDP jumped 18.2% on quarter in the third quarter (+15.0% expected), and consumer prices edged down 0.1% on month in October (+0.0% expected).
GBP/USD added 0.14% to 1.2949. In the U.K., the Nationwide Building Society House Price Index rose 0.8% on month in October (+0.4% expected). Meanwhile, investors should beware the impact on the pound of the U.K. government's latest announcement of a new round of pandemic-induced lockdown measures.
USD/JPY edged higher to 104.66, while both AUD/USD and USD/CAD closed flat at 0.7028 and 1.3322 respectively.
S&P 500 Index (Daily Chart) : Downside Prevails
Sources: GAIN Capital, TradingView
Investors became cautious ahead of the November 3 presidential election, and remained concerned over the record-breaking COVID-19 cases around the world.
At the weekend, U.K. Prime Minister Boris Johnson announced a second lockdown for England in order to curb rising coronavirus cases. Pubs, restaurants, gyms and non-essential shops will have to close for four weeks, while schools, colleges and universities can stay open.
Technology Hardware & Equipment (-4.52%), Retailing (-3.7%) and Semiconductors & Semiconductor Equipment (-1.94%) sectors lost the most. Facebook (FB -6.31%), Amazon.com (AMZN -5.45%) and Apple (AAPL -5.60%) were down heavily despite posting better-than-expected results. Alphabet (GOOGL +3.80%) ended higher.
Twitter (TWTR -21.11%) was the top loser after third-quarter daily active-user amount missed market expectations.
Approximately 60% (58% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 16% (12% in the prior session) were trading above their 20-day moving average.
Regarding U.S. economic data, Personal Income rose 0.9% on month in September (+0.4% expected) and Personal Spending increased 1.4% (+1.0% expected). The University of Michigan's Consumer Sentiment Index advanced to 81.8 in October (81.2 expected), and the Market News International Chicago Business Barometer slipped to 61.1 in October (58.0 expected).
European stocks ended mixed. The Stoxx Europe 600 added 0.18%, France's CAC 40 climbed 0.54%, while Germany's DAX 30 slipped 0.36% and the U.K.'s FTSE 100 dipped 0.08%.
U.S. Treasury prices remained under pressure, as the benchmark 10-year Treasury yield charged higher to 0.855% from 0.835% Thursday.
Spot gold gained $11 (+0.60%) to $1,878 an ounce.
U.S. WTI crude futures (December) sank a further $0.57 (-1.58%) to $35.6 a barrel.
On the forex front, the U.S. dollar was still firm against other major currencies. The ICE Dollar Index has regained the 94.00 level.
EUR/USD declined 0.24% to 1.1646 extending its losing streak to a fifth session. Official data showed that the eurozone's GDP grew 12.7% on quarter in the third quarter (+9.6% expected), consumer prices added 0.2% on month in October (+0.1% expected) and jobless rate rose to 8.3% in September (8.2% expected).
Germany's GDP increased 8.2% on quarter in the third quarter (+7.3% expected), while retail sales declined 2.2% on month in September (-0.6% expected).
France's GDP jumped 18.2% on quarter in the third quarter (+15.0% expected), and consumer prices edged down 0.1% on month in October (+0.0% expected).
GBP/USD added 0.14% to 1.2949. In the U.K., the Nationwide Building Society House Price Index rose 0.8% on month in October (+0.4% expected). Meanwhile, investors should beware the impact on the pound of the U.K. government's latest announcement of a new round of pandemic-induced lockdown measures.
USD/JPY edged higher to 104.66, while both AUD/USD and USD/CAD closed flat at 0.7028 and 1.3322 respectively.
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Price Forecast: XAU/USD Plunges 12.4% Toward Critical Support 10 1 2026
Softer inflation has revived expectations for a Fed pause, but Friday’s payrolls could put gold’s recovery prospects to the test.


Dow Jones forecast: Stock markets under pressure from multiple sources
When looking at the major tech-heavy US indices like the S&P 500 or the Nasdaq 100, you wouldn’t think that the stock market is particularly weak. Yet, beneath the surface, the market is far from healthy right now. Investors are evidently just piling into the big tech and AI names, and as a result, market breadth is deteriorating. Other indices like the small cap Russell 2000 and the Dow Jones are starting to reflect that weakness.


Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.