


AU Q2 inflation surges but fears ease over supersized 75bp RBA rate hike
June quarter Australian inflation data has surged to 6.1%, but below consensus expectations easing fears of a supersized 75bp rate hike when the RBA meets next week.
Share this:
June quarter Australian inflation data has surged to 6.1%, but below consensus expectations easing fears of a supersized 75bp rate hike when the RBA meets next week.
Headline CPI rose by 1.8% QoQ and 6.1% YoY. This was the highest reading since the introduction of the Goods and Services tax in the early 2000s.
The RBA's preferred measure of inflation, the trimmed mean, increased by 1.4% QoQ and 4.9% YoY, above the market's expectations of 1.2%QoQ and 4.7%yoy.
Core inflation is now 190bp above the top of the RBA's 2-3% target band, and the annual trimmed mean was the highest since the ABS first published the series in 2003.
The most significant price rises were in
- New Dwelling purchases by owner-occupiers (+5.6%) driven by high building construction activity, combined with ongoing materials and labour shortages
- Automotive fuel (+4.2%) rose for the eighth consecutive quarter
- Furniture (+7.0%) due to increased transport and manufacturing costs.
- Vegetables (+7.3%) rose due to heavy rain flooding in Queensland and New South Wales, damaging crops and farm infrastructure.
While the trend of higher inflation towards the RBA's 7% target remains intact, the softer than expected headline print has prompted the interest rate market to erase all chances of a 75bp rate hike.
In its place, the interest rate market is cleanly priced from a 50bp rate hike when the RBA meets on Tuesday which would take the cash rate to 1.85%. The real surprise would be the delivery of a 25bp rate hike.
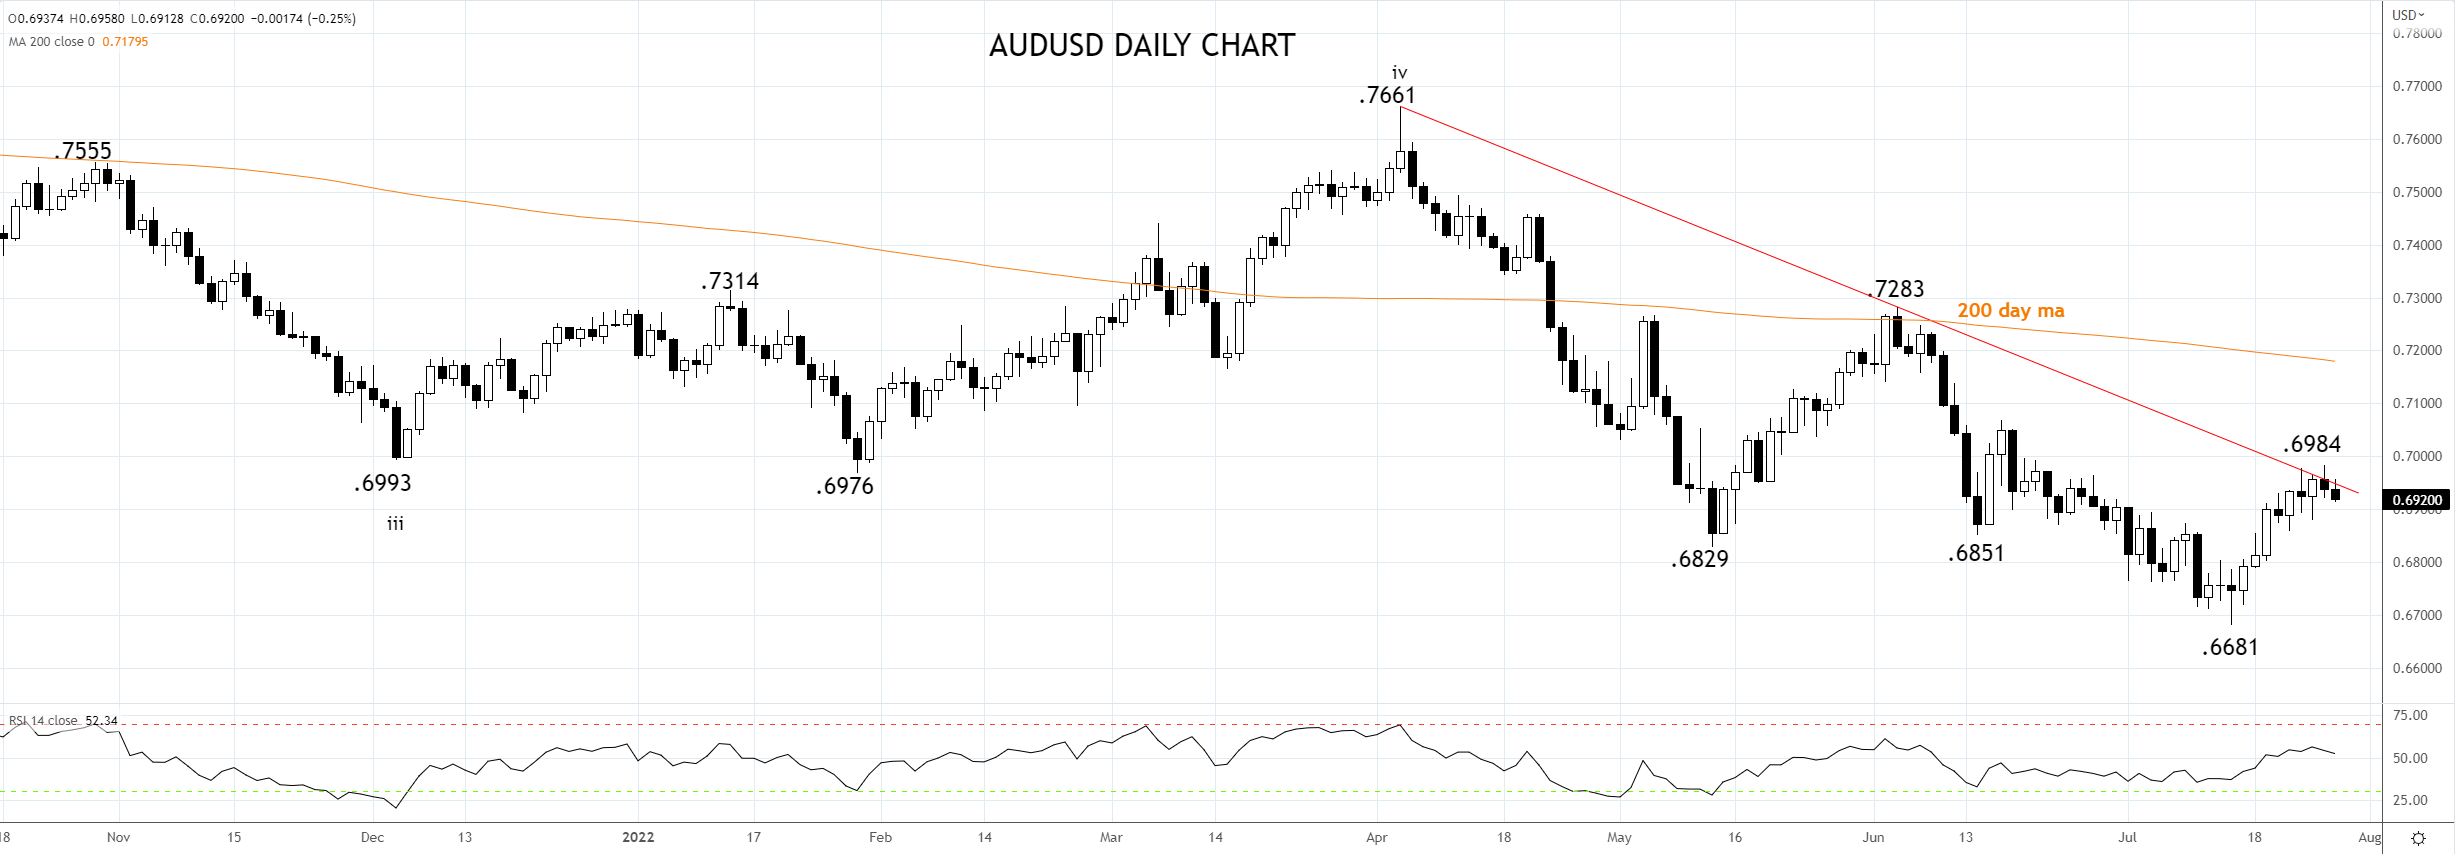
Following the release, the AUDUSD fell from .6950 to a low of .6917, retreating from the resistance band at .6960/85, which includes the downtrend from April 2022 .7661 high.
While the AUDUSD remains below .6960/85 (closing basis), the downtrend remains intact. Aware that a sustained break/close at the end of this week (Post FOMC and Q2 US GDP) above .6985c would be an initial indication a tradable low is in place at .6681 and that a more substantial rally can develop.
Source Tradingview. The figures stated are as of July 27th ,2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
June quarter Australian inflation data has surged to 6.1%, but below consensus expectations easing fears of a supersized 75bp rate hike when the RBA meets next week.
Headline CPI rose by 1.8% QoQ and 6.1% YoY. This was the highest reading since the introduction of the Goods and Services tax in the early 2000s
The RBA's preferred measure of inflation, the trimmed mean, increased by 1.4% QoQ and 4.9% YoY, above the market's expectations of 1.2%QoQ and 4.7%yoy.
Core inflation is now 190bp above the top of the RBA's 2-3% target band, and the annual trimmed mean was the highest since the ABS first published the series in 2003.
The most significant price rises were in
- New Dwelling purchases by owner-occupiers (+5.6%) driven by high building construction activity, combined with ongoing materials and labour shortages
- Automotive fuel (+4.2%) rose for the eighth consecutive quarter
- Furniture (+7.0%) due to increased transport and manufacturing costs.
- Vegetables (+7.3%) rose due to heavy rain flooding in Queensland and New South Wales, damaging crops and farm infrastructure.
While the trend of higher inflation towards the RBA's 7% target remains intact, the softer than expected headline print has prompted the interest rate market to erase all chances of a 75bp rate hike.
In its place, the interest rate market is cleanly priced from a 50bp rate hike when the RBA meets on Tuesday which would take the cash rate to 1.85%. The real surprise would be the delivery of a 25bp rate hike.
Following the release, the AUDUSD fell from .6950 to a low of .6917, retreating from the resistance band at .6960/85, which includes the downtrend from April 2022 .7661 high.
While the AUDUSD remains below .6960/85 (closing basis), the downtrend remains intact. Aware that a sustained break/close at the end of this week (Post FOMC and Q2 US GDP) above .6985c would be an initial indication a tradable low is in place at .6681 and that a more substantial rally can develop.
Source Tradingview. The figures stated are as of July 27th ,2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Weekly Outlook: Bulls Eye Higher Range After Historic Rate Shock
A historic US rate shock has sent USD/JPY above 160, but with intervention risks rising and few major economic catalysts ahead, AI sentiment could hold the key to the next move.

US Dollar Price Action Setups: EUR/USD, USD/JPY
The US Dollar broke out to a fresh yearly high after the CPI report, and that Dollar strength was on full view in pretty much all major pairings with a particular push in EUR/USD.


US dollar forecast: USD/JPY and USD/CHF in focus | Forex Friday
Sticky US inflation and a hawkish Fed have kept the dollar firm across the majors, with USD/JPY pressing on the 160 handle. Here are the levels that matter on USD/JPY and USD/CHF as next week's retail sales, Nvidia results and FOMC minutes approach.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.