



AUD/USD, ASX 200: An inverse play on what happens with US 2-year bond yields
For cyclical assets that have run hard on the lower rates, stronger growth narrative, such as the ASX 200 and AUD/USD, a meaningful unwind of US rate cut bets could lead to an ugly and abrupt air pocket for these markets.
Share this:
- ASX 200 and AUD/USD have rallied hard following the Fed’s dovish pivot
- Both charts are basically the inverse of the US 2-year Treasury note yield, underlining the importance Fed rate expectations may have on their future performance
- Given strength in the US economy, the potential for rate cut bets being pared appears an unappreciated risk
Australia’s ASX 200 and the AUD/USD remain driven by sentiment on the prospects for a soft landing for the global economy, reflecting their exposure to early stages of supply chains through Australia’s vast commodity wealth. And when it comes to what could determine whether we see a soft landing, much will come down to what the Federal Reserve does with interest rates given its proxy role as the world’s central bank.
ASX 200, AUD/USD surge following Fed’s unexpected early pivot
Both the ASX 200 and AUD/USD rallied hard in late 2023 as the Fed introduced financial conditions as a driver of monetary policy in mid-October, paving the way for the FOMC “pivot” towards signalling rate cuts in December. The pre-emptive dovish move – at odds with warnings issued by Fed Chair Jerome Powell previously about declaring victory over inflation too quickly – was perceived by markets as the Fed prioritising growth over inflation, resulting in cyclical assets ripping higher.
But now that’s priced. And there remains unease that progress in returning inflation back to the Fed’s target may stall, especially with the US economy continuing to grow above potential with tight labour market conditions helping to fuel wage pressures, providing the environment that could leave services inflation at uncomfortably high levels.
But economic models suggest US growth, inflation and wages remain strong
You only need to look at the GDPNow, Inflation Nowcast and Wage growth tracker from the Atlanta and Cleveland Fed to see why doubts remain as to whether the FOMC will cut rates as much as six times this year, as markets are currently priced.
The Atlanta Fed GDPNow suggests the US economy grew at a seasonally adjusted annual rate of more than 2% in Q4, adding to the momentum reported in the three months to September. That’s the kind of growth that would normally add to inflationary pressures.
Source: Atlanta Fed
And based on the Cleveland Fed Inflation Nowcast, core PCE inflation may increase 0.26% and 0.25% respectively in December and January, lower than those seen for much of 2022 and early 2023 but not compatible with the Fed returning inflation to 2% on an annual basis.
Source: Cleveland Fed
The Atlanta Fed wage growth tracker also shows the prior deceleration in wage pressures stalled in late 2023, suggesting average hourly earnings grew 5.2% from a year earlier with rates for job leavers and stayers either remaining steady or increasing from a month earlier. That, too, is incompatible with the Fed achieving its inflation mandate unless we see an unlikely surge in productivity growth to accompany it.
Source: Atlanta Fed
While these are models and not infallible, they conflict with markets who refuse to let go of the view that widespread and large-scale rate cuts are coming in the United States, providing fuel for the soft landing narrative. Much of the progress in reducing inflation has come from volatile goods prices. But if that trend was to reverse with services inflation remaining strong, it would make it incredibly difficult for the Fed to cut rates by as much as 150 basis points. Right now, rather than a hard landing, that comes across as the more realistic tail-risk.
Trapdoor risk for cyclical assets appears elevated
For cyclical assets that have run hard on the lower rates, stronger growth narrative, such as the ASX 200 and AUD/USD, a meaningful unwind of US rate cut bets could lead to an ugly and abrupt air pocket for these markets. When you look at both, they’re basically the inverse of the US two-year yield, underlining the importance of US rate cut expectations in helping to sustain or promote further gains.
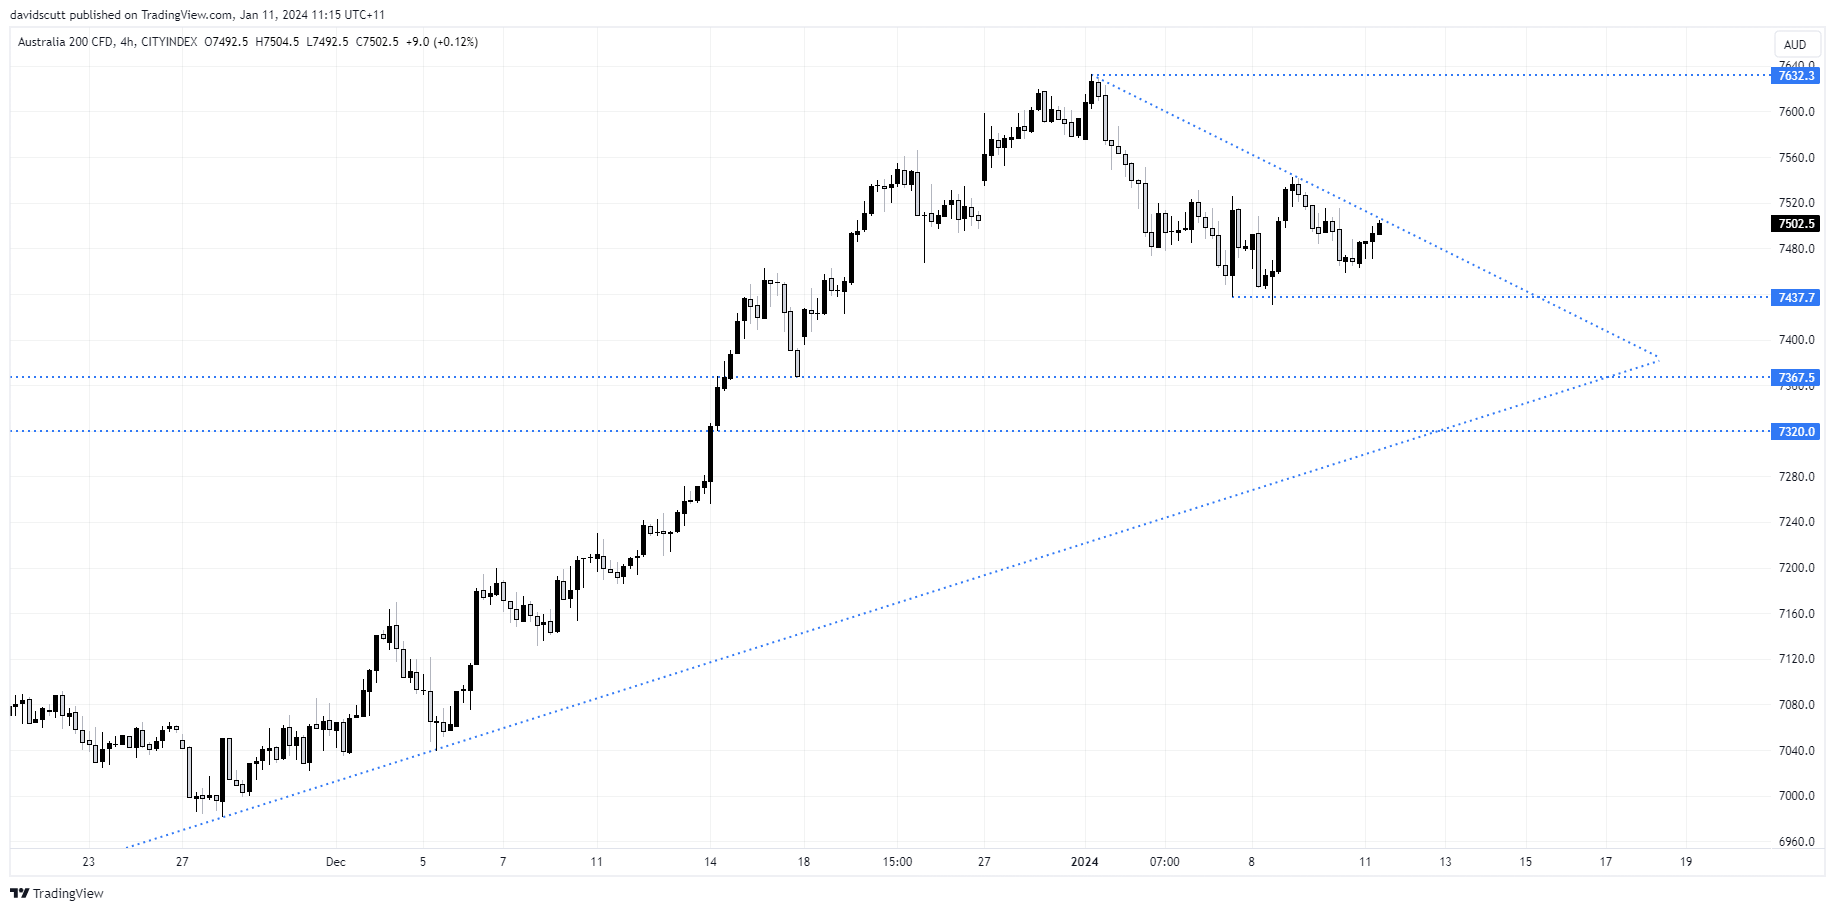
The ASX 200 sits in a descending triangle on the 4-hourly chart, testing downtrend resistance ahead of the US inflation report for December later In the session, an event that carries the potential to deliver a meaningful shift in Fed rate expectations despite it not being its preferred inflation measure.
A break to the topside would being a retest of the December high above 7630 into play, and likely an attempt at record highs after that. On the downside, minor support is found around 7438, 7368 and 7320, the latter the intersection with uptrend support running from late October.
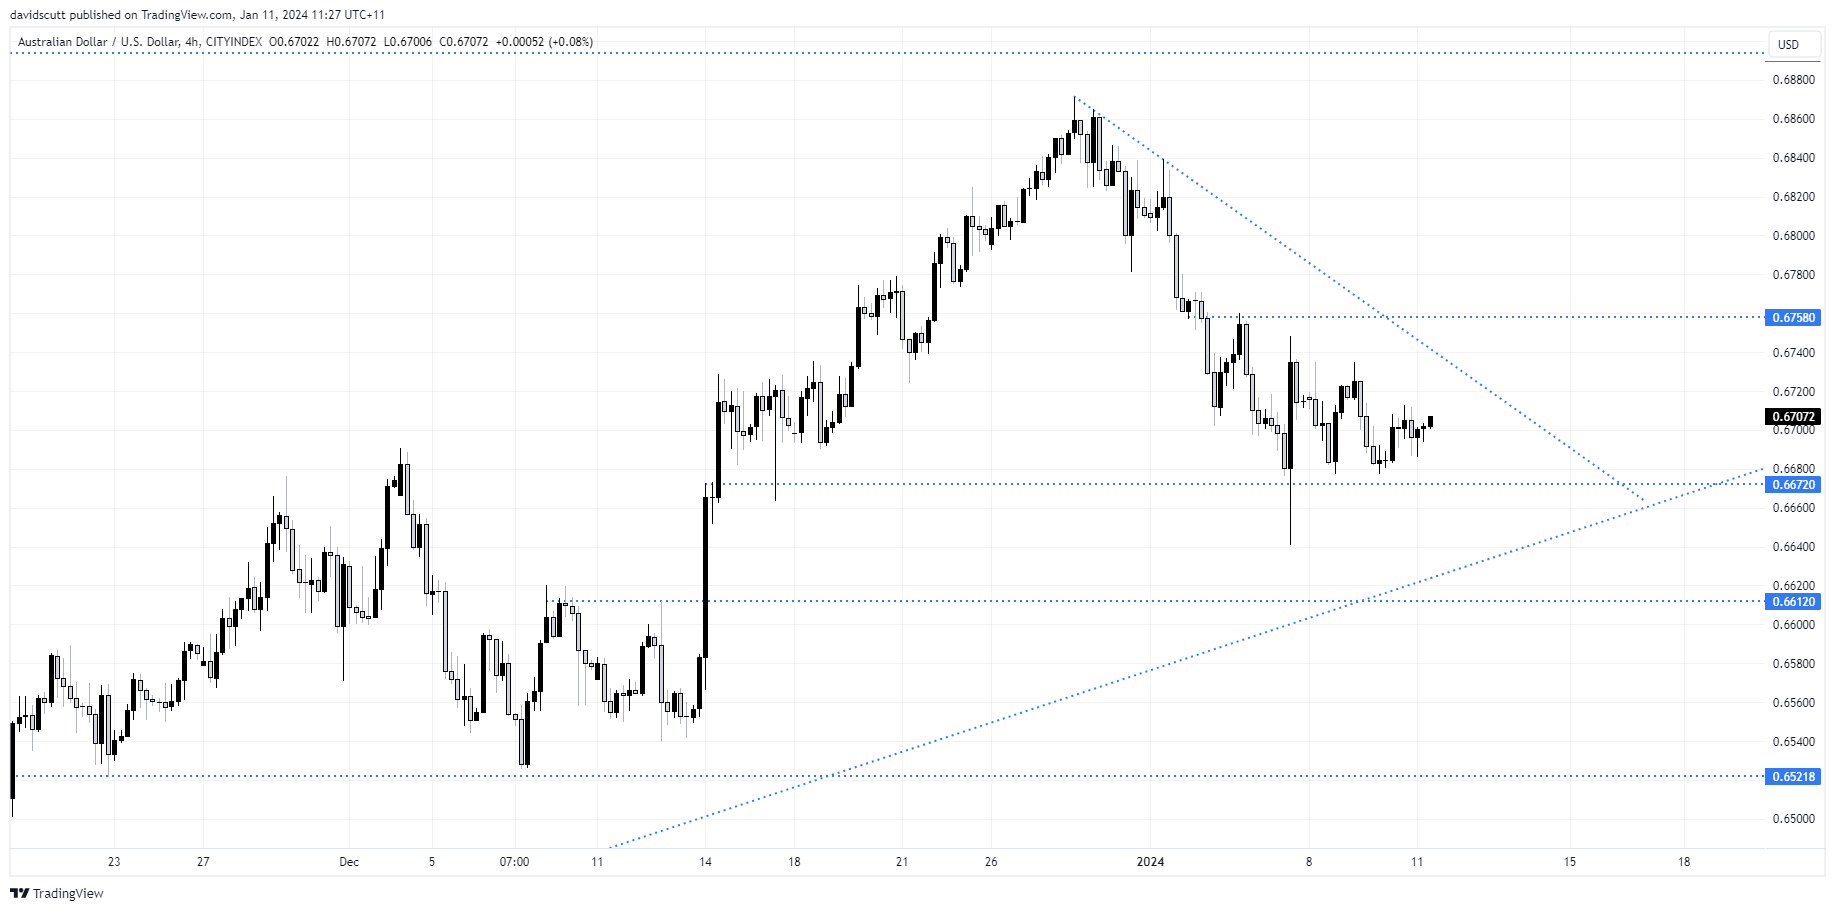
For the AUD/USD, the setup is not too dissimilar, trading in a descending triangle having pulled back from multi-month highs struck in late December. On the downside, the pair has attracted strong buying on probes below .6672 dating back to the middle of last month. Below, uptrend support running from late October kicks in around .6620 with minor support near .6610 just below.
-- Written by David Scutt
Follow David on Twitter @scutty
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.


RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

AUD/USD Analysis: What's Next for the Australian Dollar After the RBA Decision?
Recent trading sessions have reflected a more neutral tone around the Australian dollar. This can be seen in AUD/USD price action, which has posted moves of roughly 0.2% over the last two sessions without establishing a clear direction. Much of this lack of momentum is linked to expectations surrounding the next policy moves from both the Reserve Bank of Australia (RBA) and the Federal Reserve.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.