

Australian Dollar Outlook: AUD/USD Sentiment Sours Into RBA Mins, Jobs
The Australian dollar slid as trade-war tensions resurfaced and domestic data softened, leaving AUD/USD exposed ahead of RBA minutes and employment figures.
Share this:
The Australian dollar endured a volatile week, sliding sharply on Friday as renewed U.S.–China tariff tensions triggered a global risk-off move. President Trump’s 100% tariff threat reignited trade-war fears and hit commodity currencies hard, though the market reaction suggests traders doubt the escalation will stick. With U.S. data releases frozen by the government shutdown and Australia’s labour market showing fresh cracks, AUD/USD remains vulnerable to downside pressure in the near term.
View related analysis:
View related analysis:
Trump’s Tariff Threat, Weak Consumer Sentiment Hits the Australian Dollar
The Trump-tariff theme has reared its ugly head once again, sparking a bout of volatility and risk-off sentiment on Friday that saw the Australian dollar fall 1.7% by the close. President Trump threatened China with an additional 100% tariff on its goods in response to Beijing’s newly announced rare-earth export controls. Given the US imports roughly 80% of its rare earths from China, Beijing has struck the US where it hurts.
While the direct impact on Australia is limited, fears of a global slowdown and renewed trade-war tensions tend to weigh on commodity currencies such as the Aussie. Still, the fact that AUD/USD fell only 1.7% suggests markets aren’t taking this round of tariff threats too seriously — especially with TACO in mind (“Trump Always Chickens Out”).
Earlier in the week, the Australian dollar was already under pressure as the US dollar extended its bullish run, Wall Street experienced a brief risk-off wobble, and consumer confidence weakened in Australia. According to the Westpac–Melbourne Institute survey, consumer sentiment fell to a six-month low — down 6.5% over the past two months — effectively reversing all the optimism gained since the RBA’s last rate cut.


AUD/USD Implied Volatility Spikes, Risk-Reversals Move Lower
Still, the 1-week and 1-month annualised implied volatility level rose to a 3-month high on Friday, while AUD/USD endured its worst day since April, just like Wall Street indices. Risk-reversals fell to a 4-month low to show a rise of bearish bets against the Australian dollar. Given the rise of realised and expected volatility, AUD/USD is vulnerable top whipsaws amid US-China headlines this week.
Ultimately, traders may want to remain nimble and investors allow plenty of wriggle room for choppy, two-way trade.

Chart analysis by Matt Simpson, Source: LSEG
US Economic Data? Not So Fast…
We’re now roughly 10 days into the US government shutdown, which makes it longer than usual — though not as bad as the 35-day shutdown from December 2018 to January 2019. That means the US economic data schedule is shot to pieces. Not only are high-level government releases such as nonfarm payrolls paused indefinitely, but also third-party reports (such as from the Census Bureau) that rely on government inputs to calculate their data series.
Even if the government were to reopen this week, there will be bottlenecks to clear, and data will be released sporadically. Using history as our guide, weeks two to three after reopening are when we can expect a staggered backfill of data, while weeks four and beyond are when we begin to see data normalisation. Which is a shame because we would have had NFP and CPI data to mull over ahead of this month’s Fed meeting. And the lack of data brings into question as to whether the Fed really can cut.
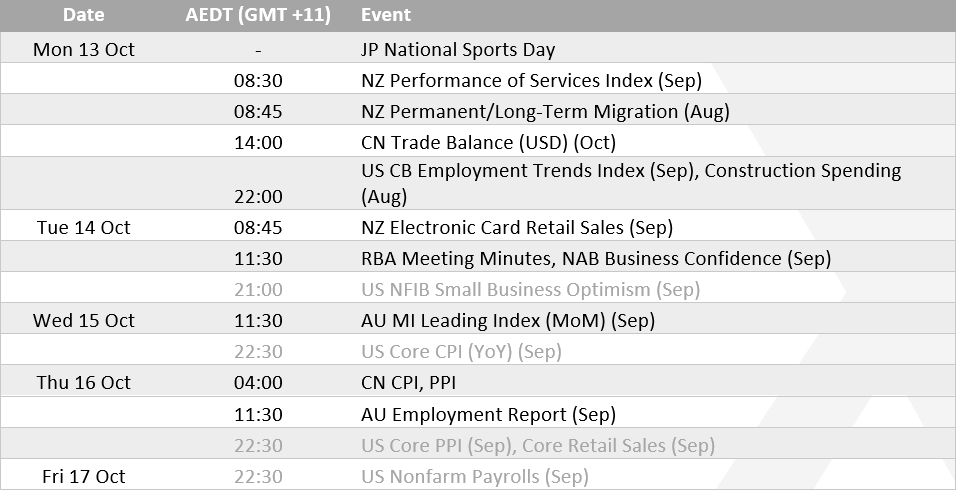
Chart prepared by Matt Simpson - data source: Investing.com


Australian Employment Softens as RBA Weighs Policy Caution
Australia’s employment situation continues to lose its shine, with unemployment edging higher and the participation rate appearing to have peaked. Full-time employment has fallen by around 40k in two of the past three months, marking the second contraction in headline job growth this year — albeit a modest -5.4k. So far in 2025, the cumulative rise in full-time employment stands at 74.9k jobs. Employment is still growing, but clearly at a slower pace than last year.
RBA cash rate futures currently imply a 42% chance of a rate cut at next week’s meeting, a probability that could rise if Thursday’s employment data disappoints. However, if trade war risks resurface, it could give the RBA yet another reason to remain cautious on policy changes. I expect the RBA minutes to maintain their cautious tone, without offering anything new or particularly revealing.
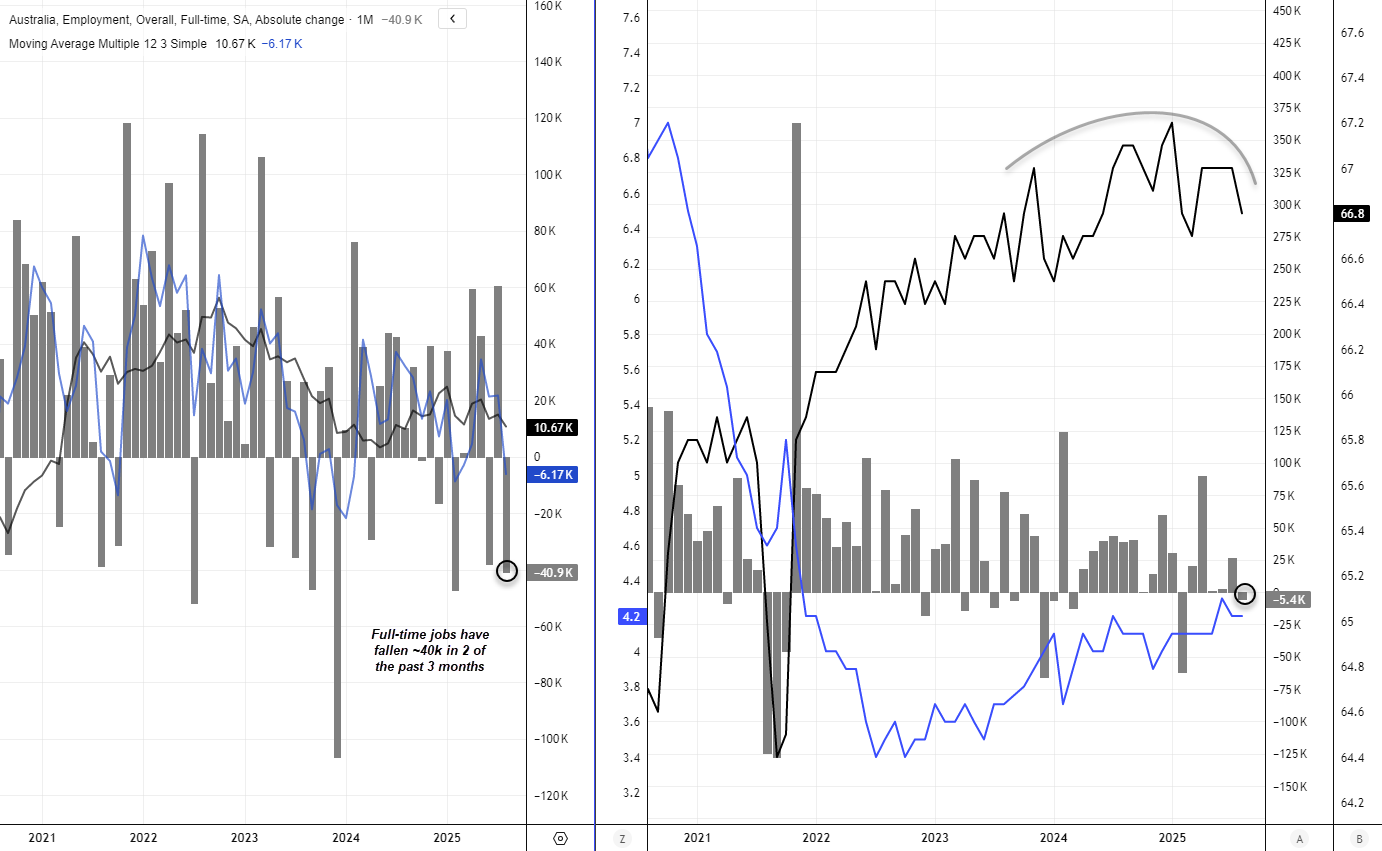
Chart prepared by Matt Simpson - data source: LSEG
AUD/USD Correlations
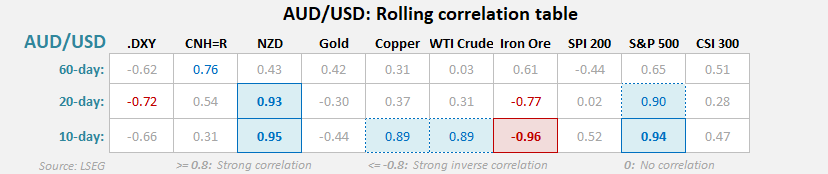
Chart prepared by Matt Simpson - data source: LSEG
AUD/USD Futures Positioning – COT Report
- Large speculators increased their net-short exposure to AUD/USD futures by 8.4k contracts last week, bringing total net shorts to 59.6k contracts.
- Gross shorts rose by 10.1k contracts (+11.1%), while gross longs increased by 1.7k contracts (+4.3%).
- Asset managers also expanded their net-short exposure by 8.4k contracts, driven by a 9% rise in shorts and a 2% reduction in longs.
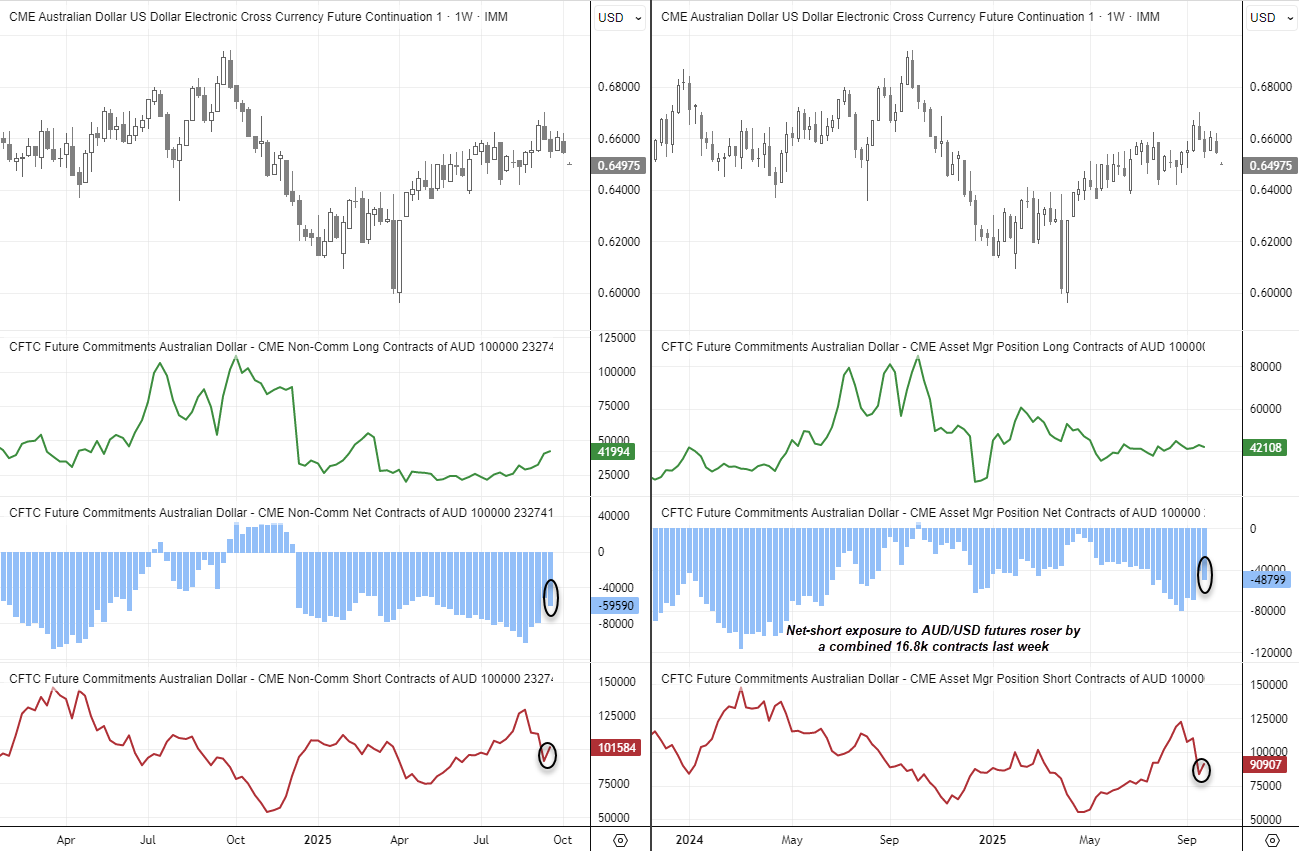
Chart prepared by Matt Simpson - data source: CME, IMM, LSEG
AUD/USD Technical Analysis
Friday’s sell-off saw a daily close below the lower Keltner band — an area the pair rarely spends much time beneath. With AUD/USD bouncing at the open, traders are already questioning how seriously to take Trump’s tariff threat. Still, overall momentum remains firmly to the downside, and bears may look to fade into such bounces.
For now, my bias is for another lower high to form on the AUD/USD daily chart, with bears eyeing the August and July lows near the high-volume node (HVN) just above 0.64.
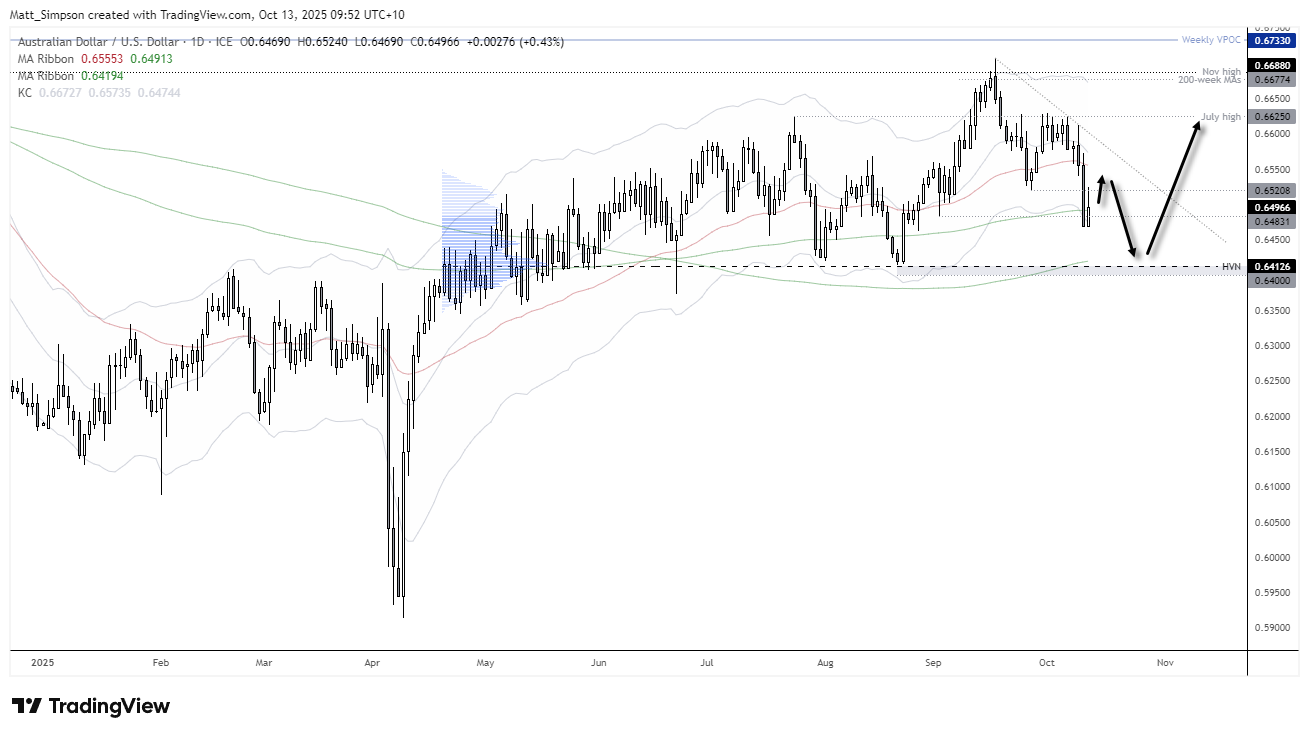
Chart analysis by Matt Simpson - data source: TradingView, AUD/USD
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Forecast: AUD/USD Support Reversal Sparks Monthly Range Breakout 10 23 2026
A sharp reversal off key support has fueled the AUD/USD recovery, with resistance now in focus ahead of next week’s Fed decision and Australian CPI.
Japanese Yen Surges Across FX Majors as Risk Aversion Intensifies
Safe-haven demand sent the Japanese yen higher across FX majors, while USD/JPY broke lower ahead of Japan's CPI release and next week's BOJ meeting.
AUD/USD Bears Denied a Big, Bearish Breakout via Hawkish RBA, Weak USD
AUD/USD defies a potential head-and-shoulders breakdown as RBA rate hike bets surge and a weaker US dollar fuels an Australian dollar rally.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.