



Can US PMI surveys and employment reports sway bonds? The Week Ahead
Last week we noted that bond yields could trump economic data this week, and for the most part they did. We can also extend that comment into next week, especially if they continue to retreat and loosen their grip on bearish sentiment and allow risk assets to rebound. Highlights in next week’s calendar include the NFP and ISM PMI reports, RBA and RBNZ monetary policy meetings, the quarterly Tankan survey for Japan and Canada’s employment report.
Share this:
Can US PMI surveys and employment reports sway bonds? The Week Ahead
Last week we noted that bond yields could trump economic data this week, and for the most part they did. We can also extend that comment into next week, especially if they continue to retreat and loosen their grip on bearish sentiment and allow risk assets to rebound. With China on holiday all next week the trading volumes may be lower than usual (and the faltering gold market may find it has fewer buyers to support it than usual). With that said, notable economic events in next week’s calendar include the monthly Nonfarm payroll and ISM PMI reports, RBA and RBNZ monetary policy meetings, the quarterly Tankan survey for Japan and Canada’s employment report.
The week that was:
- US bond yields continued to surge in the first half of the week with the long end of the curve leading the way (otherwise known as a bear steepener, as bond prices at the long end were falling the fastest)
- A multitude of concerns including higher oil prices, hawkish Fed comments, expectations of higher-for-longer Fed rates and rising risks of a US government shutdown fuelled the bond rout and sent the US dollar to YTD highs
- Kashkari hinted at a 60% chance of a soft landing for the US economy, a backing for another 25bp hike with a risk that they may need to hike further
- Global bonds followed the US and the rise of Australian yields saw the RBA’s cash rate futures imply a 96% chance of a 25bp hike by June 2024
- Yet what could have simply been profit-taking triggered a pullback on the US dollar and yields on Thursday, which allowed risk assets such as Wall Street indices and AUD/USD recoup some losses from their cycle lows
- The Swiss National Bank (SNB) reiterated their commitment to no further tightening in their quarterly bulletin, saying that their “significant tightening of monetary policy over recent quarters” is reigning in inflation
- The DAX fell to a 6-month low following another weak Ifo business sentiment report
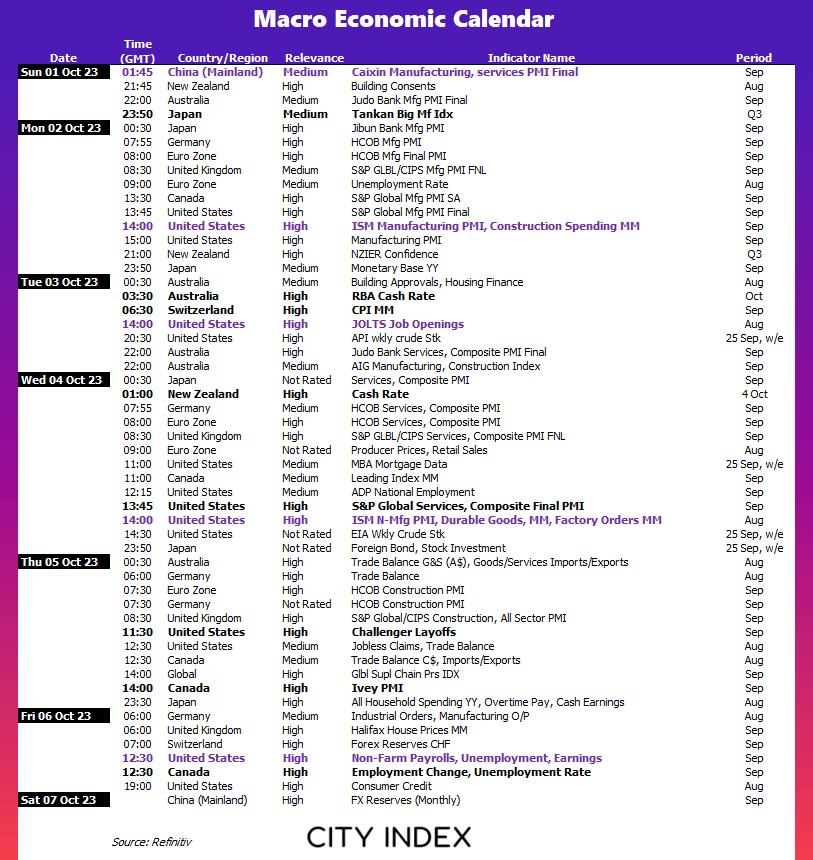
The week ahead (calendar):
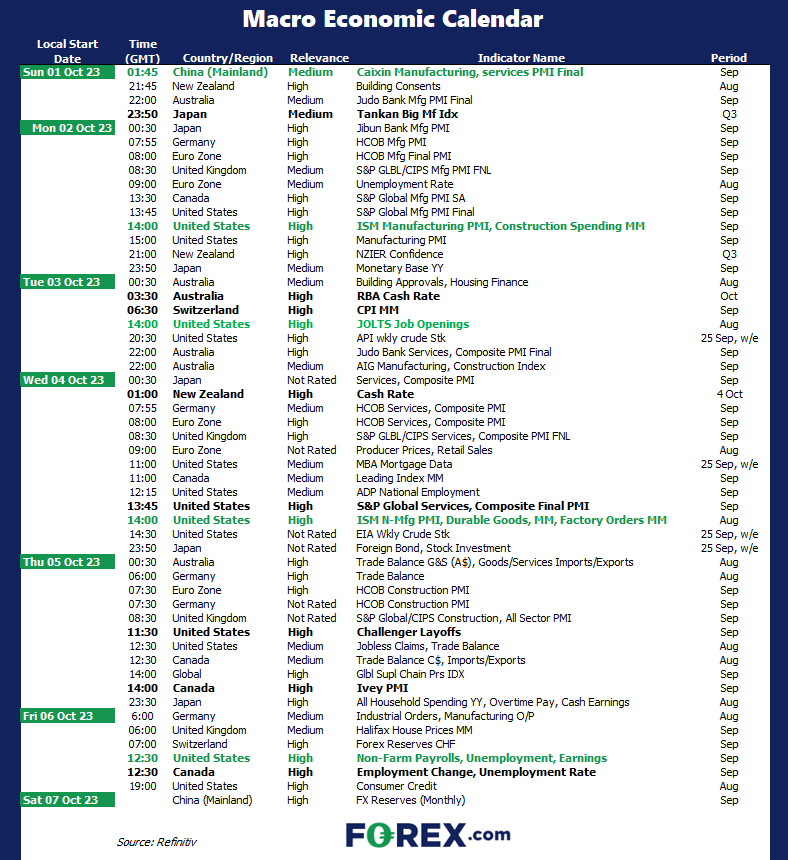
This content will only appear on City Index websites!
Earnings This Week
Look at the corporate calendar and find out what stocks will be reporting results in Earnings This Week.
The week ahead (key events and themes):
- USD strength, bond rout
- US employment (Nonfarm payroll, JOLTS job openings, jobless claims)
- ISM manufacturing, services PMI
- Canadian employment data
- Japan Tankan
- RBA and RBNZ cash rate decisions
- China PMIs (manufacturing, services, composite – Caixin)
- China public holiday (all week)
US data: (ISMs, PMIs, NFP, jobless claims, job layoffs and openings)
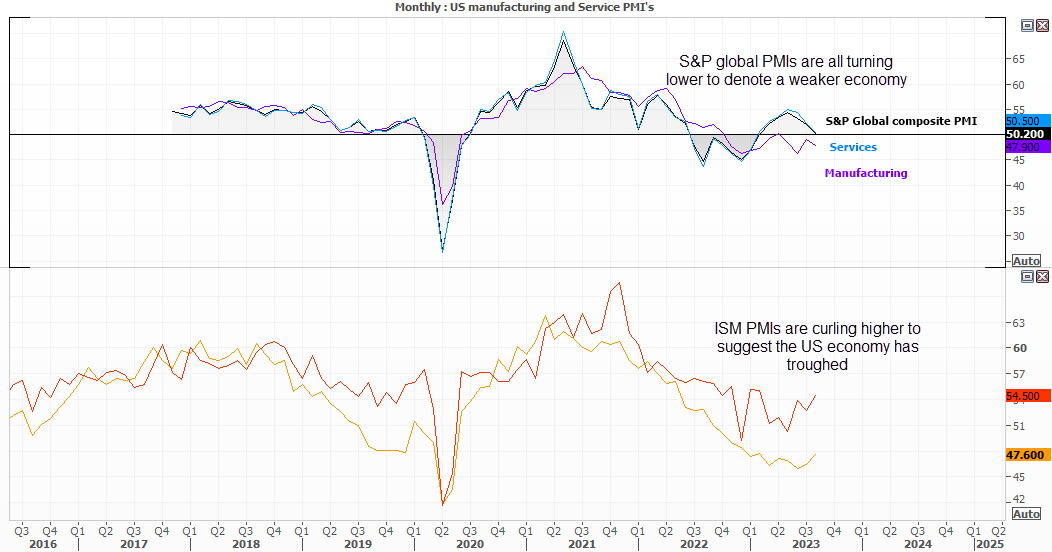
The key US data point can be split into two main groups; employment and business surveys. S&P global release their final revisions of their PMIs, all of which are pointing lower to show a soft economy. The Composite and services are on the cusp of joining manufacturing in contraction (below 50) which is at odds with the ISM surveys. The ISM services expanded at its fastest pace in six months whilst ISM manufacturing is curling higher and contracting at a slower pace. So which one is correct?
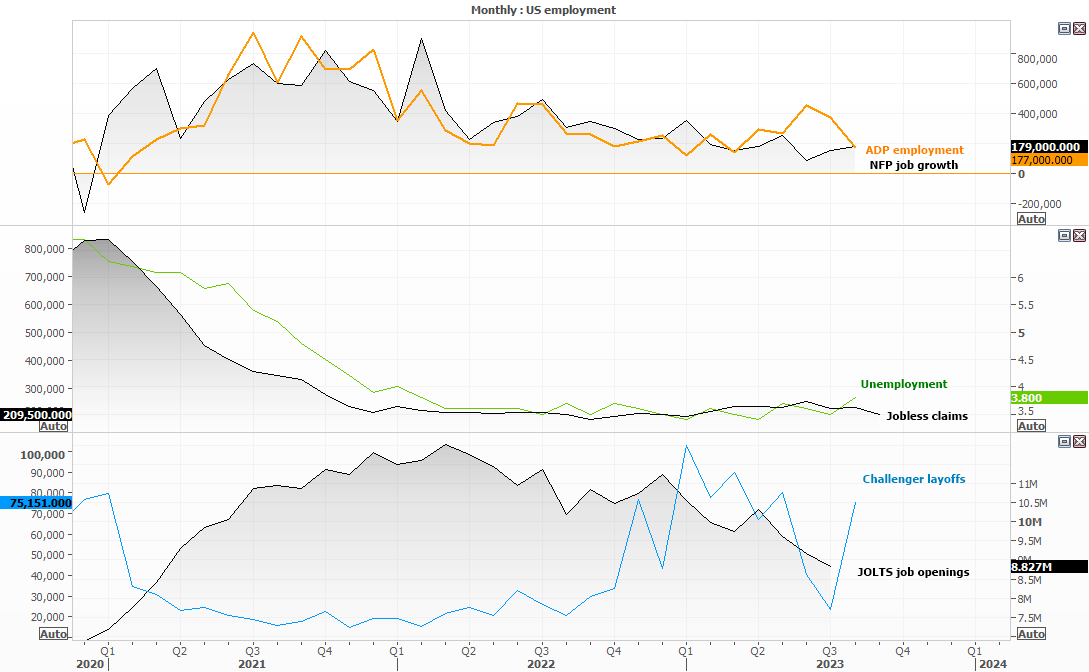
The US employment situation is also providing slightly missed signals. NFP Job growth is trending lower yet remains at healthy ‘expansive’ levels, and whilst unemployment has curled high it remains historically low at 3.8%. Job openings fell to a 48-month low, yet significantly elevated relative to its long-term average, and whilst layoffs rose over 50k last month it still pales in comparison to the times of covid. Overall, employment is remains tight but slightly softer and we’re going to have to see some surprisingly soft figures to bring the ‘higher for longer’ narrative into question. And if employment remains firm but business surveys pick up, if anything it could further fuel the bond rout and send yields and the US dollar higher.
Market to watch: EURUSD, USD/JPY, WTI Crude Oil, Gold, S&P 500, Nasdaq 100, Dow Jones
RBA and RBNZ cash rate decisions
It’s unlikely we’ll see the RBA or RBNZ change their policy next week, although it will be the first meeting for the new RBA governor Michell Bullock. It’s difficult to say whether she’ll make a mark, given there is only the joint statement of the board members to go off of. But perhaps it leaves more wriggle room for it being less of a ‘cut and paste’ job.
With markets having now prices in a 96% chance of a 25bp RBA hike by June thanks to rising bond yields, it will be interesting to see if the RBA somehow tip their hat towards it and give away another “further tightening” clue. But with household spending and retail sales pointing lower, it’s difficult to justify a hike this year.
The RBNZ are likely to change policy given their forecasts have essentially confirmed the peak rate a 5.5%.
Market to watch: AUD/USD, NZD/USD, AUD/NZD, NZD/JPY, AUD/JPY, ASX 200
China PMIs (manufacturing, services, composite – Caixin)
With China’s PMIs being released over the weekend and China on a public holiday all next week, the data really serves for sentiment outside of the region. And is the case with most data out of China this year, it likely requires an upside surprise for it to be considered a surprise at all.
Market to watch: USD/CNH, USD/JPY, S&P 500, Nasdaq 100, Dow Jones, VIX, AUD/JPY
Canadian employment data
The Bank of Canada (BOC) may have another hike up their sleeve given the return of inflation, at already elevated levels. And another hot employment report could tip them over the edge. That it is released alongside US nonfarm payrolls makes USD/CAD a candidate for unhealthy levels of volatility, but traders can also consider crosses such as CAD/JPY for a potentially cleaner move.
Market to watch: USD/CAD, CAD/JPY, NZD/CAD, AUD/CAD
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?

Gold Analysis: Resilient U.S. Labor Market Continues to Pressure XAU/USD
Recent trading sessions have not been particularly favorable for gold in the short term. XAU/USD has fallen nearly 2.5% over the last three sessions, reflecting that selling pressure is once again gaining relevance and that the metal continues to struggle to regain momentum.


Gold, silver outlook: Sandwiched between bullish bonds and AI angst
XAU/USD and XAG/USD may be approaching a bullish turning point as Treasury futures threaten a breakout. The problem? Both metals have recently been trading more like tech stocks than havens.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.