



Crude oil outlook: WTI eyes more gains as US-Iran stalemate continues
After a weaker start, crude oil prices bounced back during Monday’s London session, with Brent turning positive by mid-day. Oil prices climbed roughly 3% yesterday as markets further unwound earlier optimism surrounding a swift resolution to tensions in the Strait of Hormuz.
Share this:
After a weaker start, crude oil prices bounced back during Monday’s London session, with Brent turning positive by mid-day. Oil prices climbed roughly 3% yesterday as markets further unwound earlier optimism surrounding a swift resolution to tensions in the Strait of Hormuz. With negotiations still stalled and the key shipping route effectively closed, traders are increasingly being forced to increase the geopolitical risk premium into the market. For now, little else appears to matter. Although volatility has been somewhat subdued given the circumstance, oil remains the dominant macro driver, dictating sentiment across European equities, global bonds and currencies alike — particularly in economies heavily dependent on energy imports. Against that backdrop, the balance of risks in the crude oil outlook continues to point higher.
Will China’s XI help end the stalemate?
The US-Iran stand-off has now dragged on for more than two months and, despite the fragile ceasefire agreed in early April, there remains scant evidence that a durable settlement is close. Let’s see if China’s Xi comes up with a plan to end the war during Trump’s visit of China. But judging by comments from Trump earlier this week, investors remain cautious the US president described the truce as being “on life support”, citing continued disagreements over Tehran’s core demands.
As long as the Strait of Hormuz remains disrupted, the market will remain acutely sensitive to any further escalation. Physical supply concerns are growing, and that is feeding directly into price action. The longer the impasse drags on, the greater the risk that crude prices grind higher simply through attritional pressure.
How is oil impacting other markets?
The knock-on effects are already becoming visible elsewhere. European equities have softened again in recent days, global bond markets remain uneasy, and the euro continues to struggle against a firmer dollar backdrop. Higher energy prices are effectively acting as a tax on growth expectations, particularly across import-reliant economies.
At this stage, the central question for markets is how long both sides are prepared to tolerate elevated oil prices before political pressure forces compromise. Tehran appears willing to absorb considerable economic pain in pursuit of longer-term guarantees, while Washington continues to reject several of Iran’s key conditions outright. For now, the stalemate persists — and the market is losing confidence that a breakthrough is imminent.
Crude oil outlook: WTI technical analysis and levels to watch
From a technical analysis point of view, WTI continues to carve out what increasingly resembles a medium-term base. Spot WTI has now pushed back towards the psychologically important $100 per barrel region, with momentum remaining firmly constructive in the near term. WTI futures have already broken through that level by a good $2 or so.
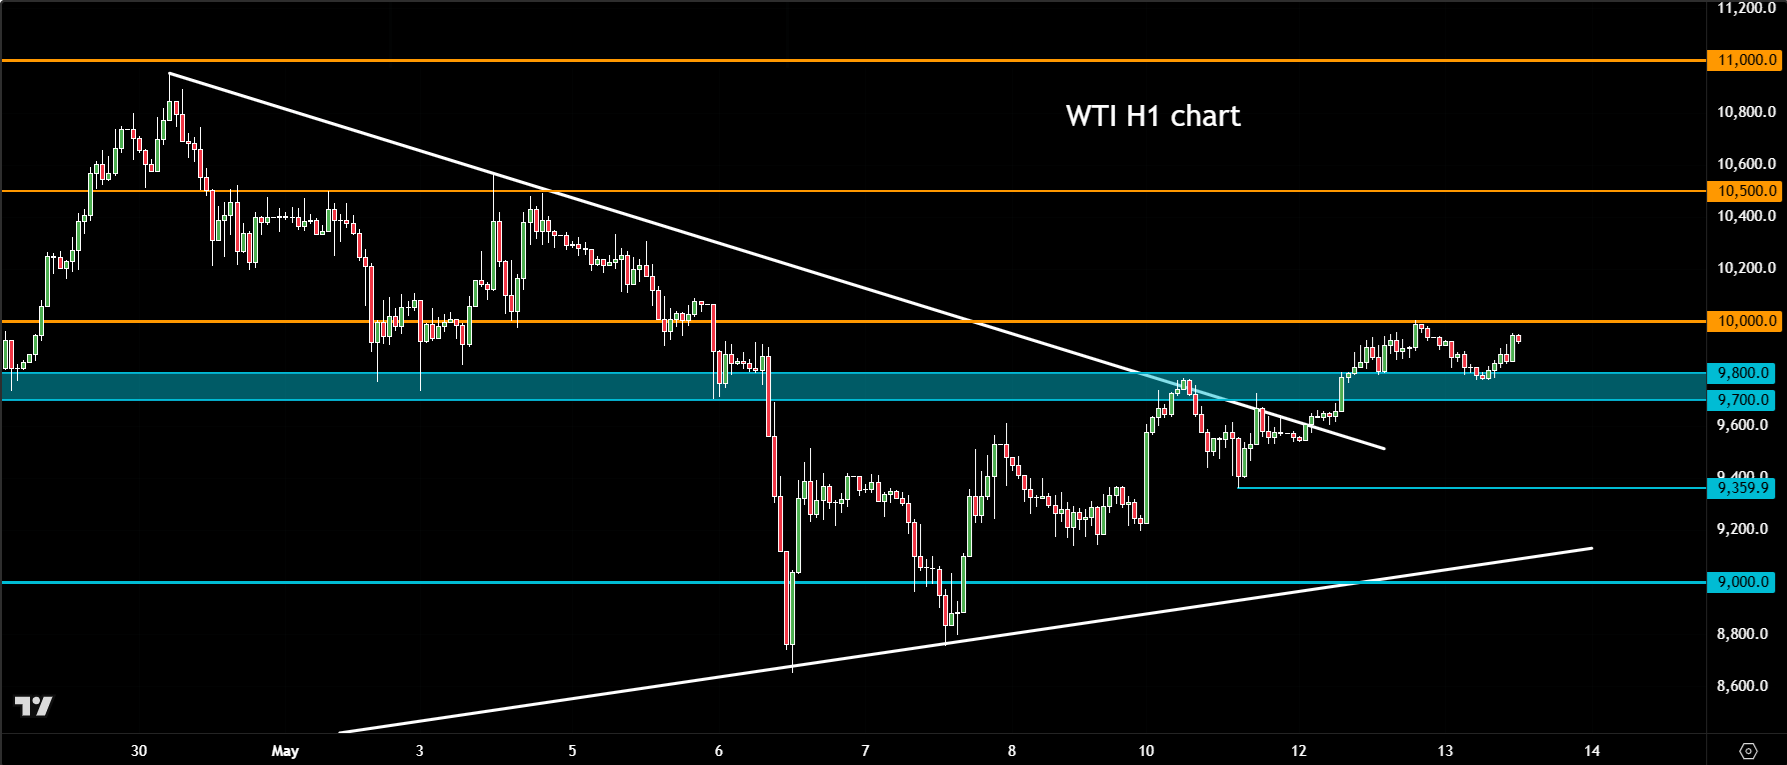
On WTI, the $97-$98 area is particularly important for the direction of oil prices. Previous resistance in that region has now been cleared, and this area has now acted as support following the earlier retracement. As long as prices remain above that band, buyers are likely to retain control of the broader trend.
Below there, the next key support sits around $95, followed by the recent swing low near $93.60. A move beneath that level would weaken the immediate bullish structure and would probably require a meaningful de-escalation in the US-Iran situation to materialise.
On the topside, resistance around $100 was already yesterday, and another test or two could lead to a potential breakout. A sustained break above triple digits would likely reinforce bullish momentum and could open the door for a retest of the recent highs seen earlier this year.
Should that occur, the wider financial markets may begin to feel more pronounced strain, particularly risk-sensitive assets already struggling with slowing global growth expectations.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.


Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.